Market brief · Europe
Investing in Czechia
The first listings in Czechia are being prepared with our partners. Members hear about them first, and the markets below are open now.
Buying in Czechia
 Country guide · 24 minCzech Republic Investor GuideNavigate Central Europe's most stable post-transition market, zero transfer tax, EU access, and growing yields in Prague, Brno and OstravaEU MemberStable MarketNon-EurozoneRead the guide
Cities2 guides
All Czechia city guides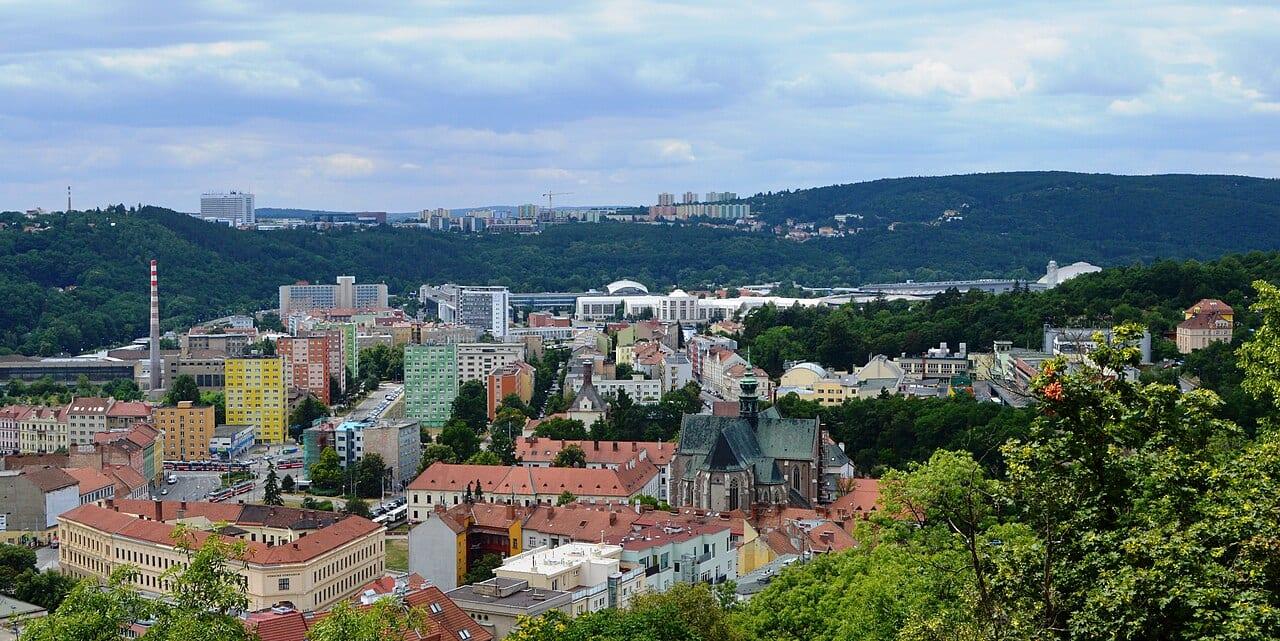 City guide · 7 minBrnoThe Czech Republic's second city and its leading technology and university hub, Brno pairs a deep, low-vacancy rental market with appreciation that has lately outpaced Prague in percentage terms. Average apartment prices crossed CZK 116,400 per square metre (about EUR 4,750) in 2025, with a typical flat reaching CZK 9.3 million, still meaningfully cheaper than the capital, where comparable stock sells for roughly 40% more. Demand is driven by the Brno University of Technology, Masaryk University, and the Brno Technology Park, home to IBM, Red Hat, and other multinationals; the student and skilled-professional pipeline keeps the central districts tightly occupied. Kralovo Pole, adjacent to the campuses and tech park, is among the fastest-rising neighbourhoods in the country with 8-12% annual price growth, while the historic centre (Brno-stred), Veveri, and Zabovresky offer characterful pre-war stock. Czech secondary-market prices surged around 21% year-on-year nationally in Q3 2025 amid a supply shortage, and Brno's own new-build asking prices reached CZK 141,000 per square metre. With a population near 384,000 and a structural housing deficit, Brno enters 2026 as the country's strongest regional investment market.
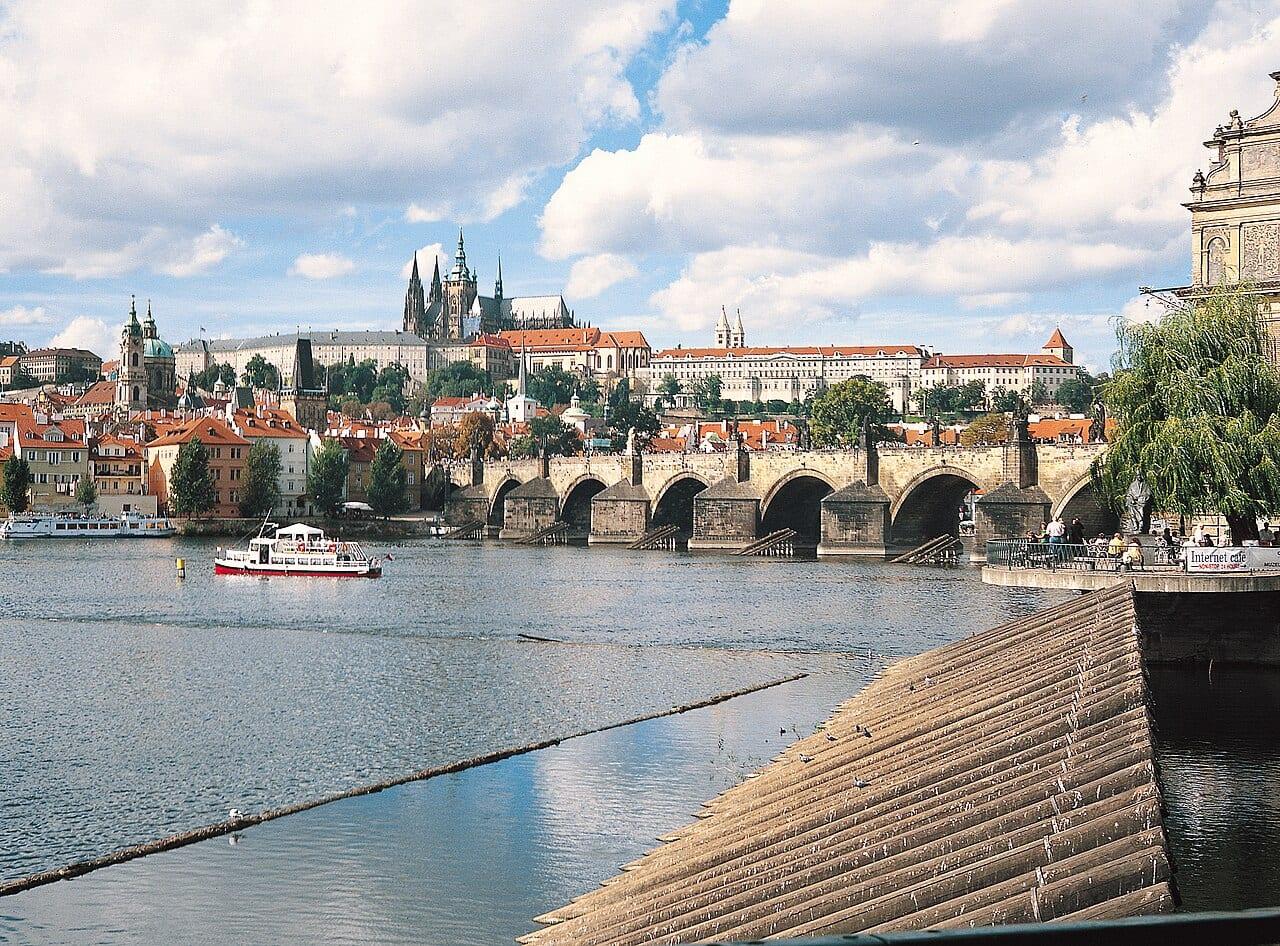 City guide · 8 minPraguePrague is Central Europe's most expensive residential property market and one of its least affordable relative to local incomes. After a brief 2022–2023 cooling, the market resumed a strong upswing through 2024–2025, with the national house price index growing roughly 10% year-on-year, driven by a chronic housing shortage, slow building-permit approvals, falling mortgage rates and persistent demand. New-build asking prices hit record highs of about €6,700/m² at end-2024, transaction prices for all apartment types reached roughly €5,400/m², and prime central districts (Prague 1 and 2) regularly exceed €8,200/m². The flip side of high prices is low income for investors: Prague's gross rental yields are among the lowest in the CEE region, around 2.8–3.0% citywide, and its price-to-income ratio of roughly 18–19 makes it one of the least affordable capitals in Europe. Prague is therefore a capital-appreciation and capital-preservation play rather than a cash-flow market, buyers accept thin running yields in exchange for a stable EU economy, strong long-term value retention and limited supply that supports prices. For foreign investors the legal environment is unusually open: since 2011 there are no restrictions on foreigners (including non-EU citizens) buying Czech real estate, and the Czech Republic abolished its 4% real-estate-acquisition tax in 2020, lowering entry costs. The main headwinds are the low yields, an emerging crackdown on short-term (Airbnb) letting, and an affordability ceiling that limits how much further prices can run.