City guides
City guides (402)
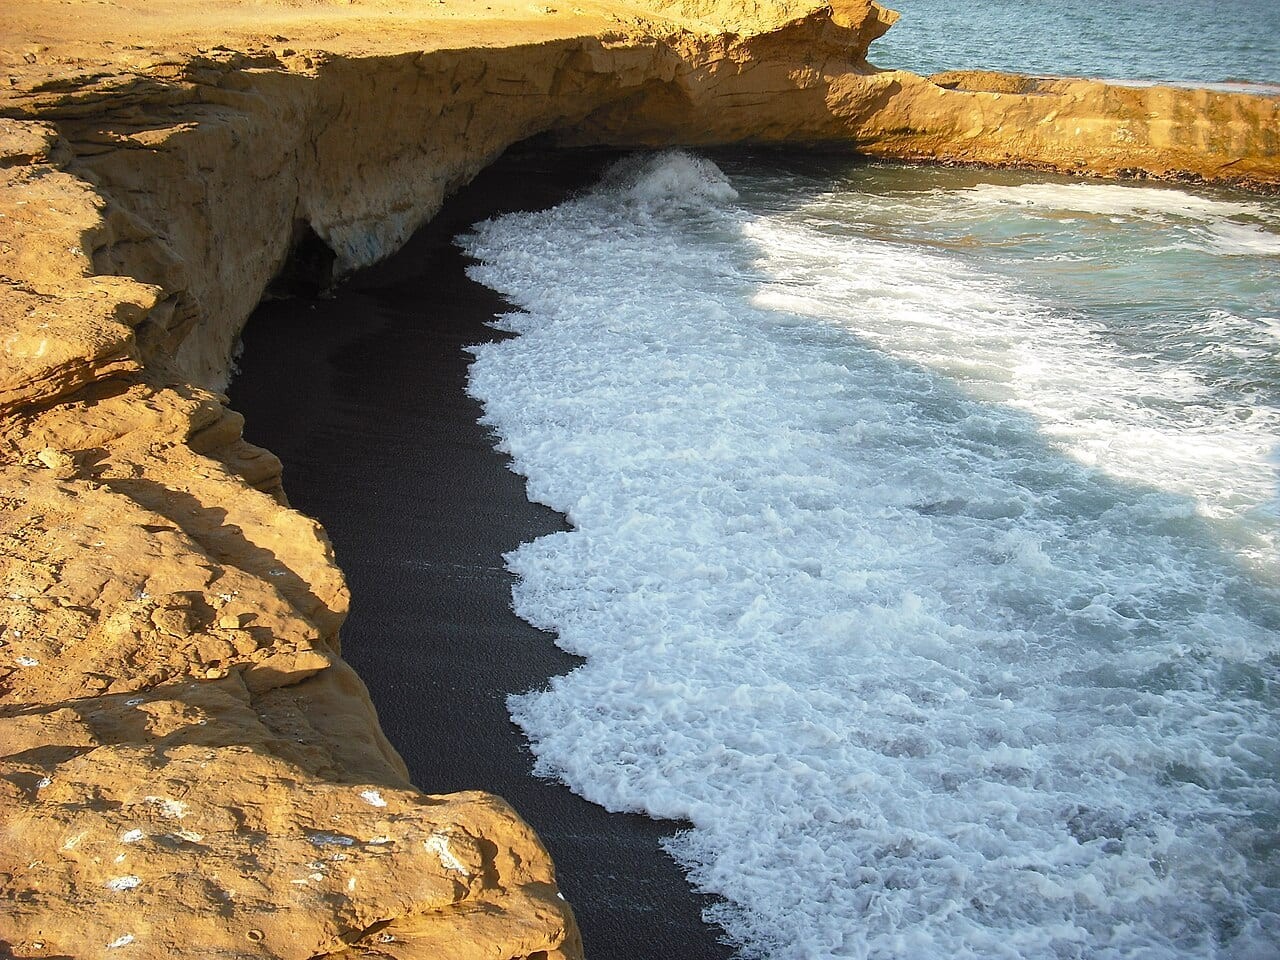

Paracas
Peru
Paracas, on the desert coast of Ica region about four hours south of Lima, is Peru's marquee upscale beach-and-nature resort, anchored by the Paracas National Reserve and the wildlife-rich Ballestas Islands. It is a planned, second-home and tourism market rather than a residential city, with developments like Condominios Nauticos and marina-side projects setting the tone. In 2026 the median condo sells for roughly USD 185,000 at about USD 1,265 per square meter, with two-bedroom waterfront units averaging higher; modern seafront apartments rent for around 2,500-3,500 soles per month, and short-let demand from Lima weekenders and international visitors supports gross yields that can reach 5-7%. Supply is limited and seasonality is pronounced, concentrated around summer and long weekends. Foreign buyers receive full freehold title registered at SUNARP with the same protections as Peruvians, and Paracas sits on the central-south coast far from any 50km border restriction, though buyers must verify clean titles and any reserve-related zoning setbacks. Year-on-year appreciation runs in the mid-single digits as Lima-driven second-home demand grows and the resort's hospitality base expands. The permanent population is small, around 7,000, swelling heavily in peak season.
Trujillo
Peru
Trujillo, Peru's third-largest city and capital of La Libertad on the northern coast, is the country's strongest value-and-yield market among major cities. Famous for its colorful colonial center, the Chan Chan archaeological complex and a thriving agro-industrial and services economy, it offers some of the cheapest entry among Peru's agglomerations: residential prices run roughly USD 800-1,000 per square meter, and 50-70 m² apartments can be found in the USD 35,000-50,000 range. Crucially, gross rental yields are among the country's highest, with Numbeo data showing around 7.2-7.4% in and outside the center, supported by steady demand from local professionals and a large student population. The metro is also a recognized appreciation story: secondary cities like Trujillo have posted 4-9% annual price growth on infrastructure investment and supply constraints, with a forward outlook near 3-5% real annual gains. Foreign buyers enjoy full freehold ownership registered at SUNARP with the same rights as nationals, and Trujillo's central-coast location sits far from any 50km border restriction. Mortgage rates near 7.4% make financing comparatively accessible. The metro population is approximately 1 million, giving the market depth and liquidity unusual for a Peruvian regional city.
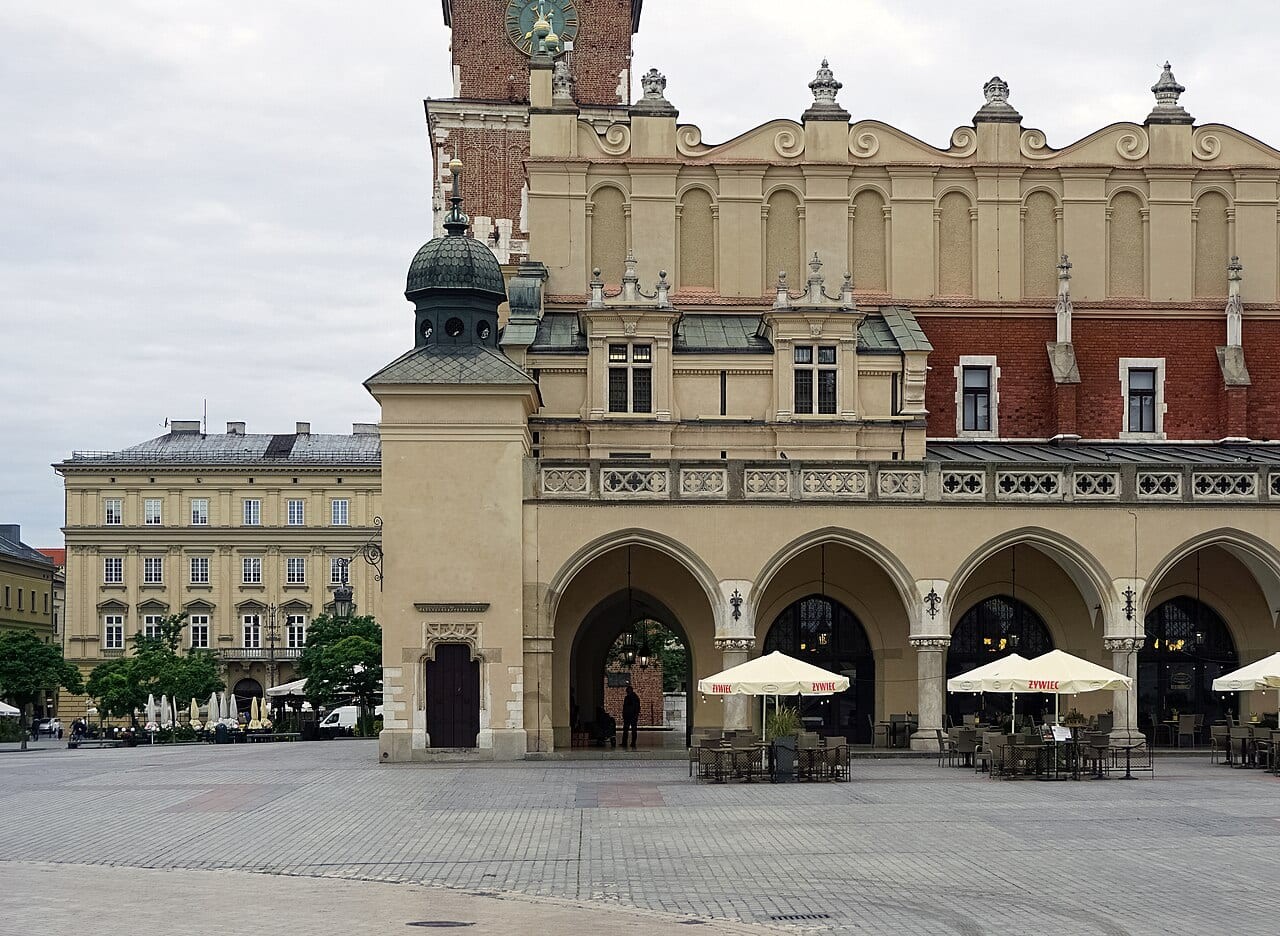

Kraków City Guide
Poland
Kraków is Poland's second-largest city (~804,000 in the city, ~1.43 million metro) and the historic royal capital. Its medieval Old Town, anchored by the vast Rynek Główny (Europe's largest medieval market square) and Wawel Royal Castle, was inscribed on the UNESCO World Heritage List in 1978, among the world's first twelve sites. Heritage tourism is a defining economic force: Kraków drew roughly 7–9 million visitors a year in 2023–2024, sustaining one of Central Europe's deepest short-term-rental and hospitality markets. Beyond tourism, Kraków is a major technology, BPO and shared-services hub, frequently ranked among Europe's top outsourcing destinations, with 84,500+ IT professionals and operations for IBM, Google, Cisco, Ericsson and others. This is underpinned by a huge student population: ~23 higher-education institutions and roughly 130,000–150,000 students, led by the Jagiellonian University (founded 1364, Poland's oldest) and AGH University. For investors, Kraków combines the demand-side strengths of a top tourist city, a deep graduate/young-professional rental pool, and a constrained, heritage-protected central housing supply. It is Poland's 2nd-priciest residential market after Warsaw, and prices are quoted in PLN, currency risk vs the euro is a real consideration. Non-EU buyers can purchase standalone apartments without a permit (only land/houses need an MSWiA permit), and Poland has no golden visa, buying property grants no residency.
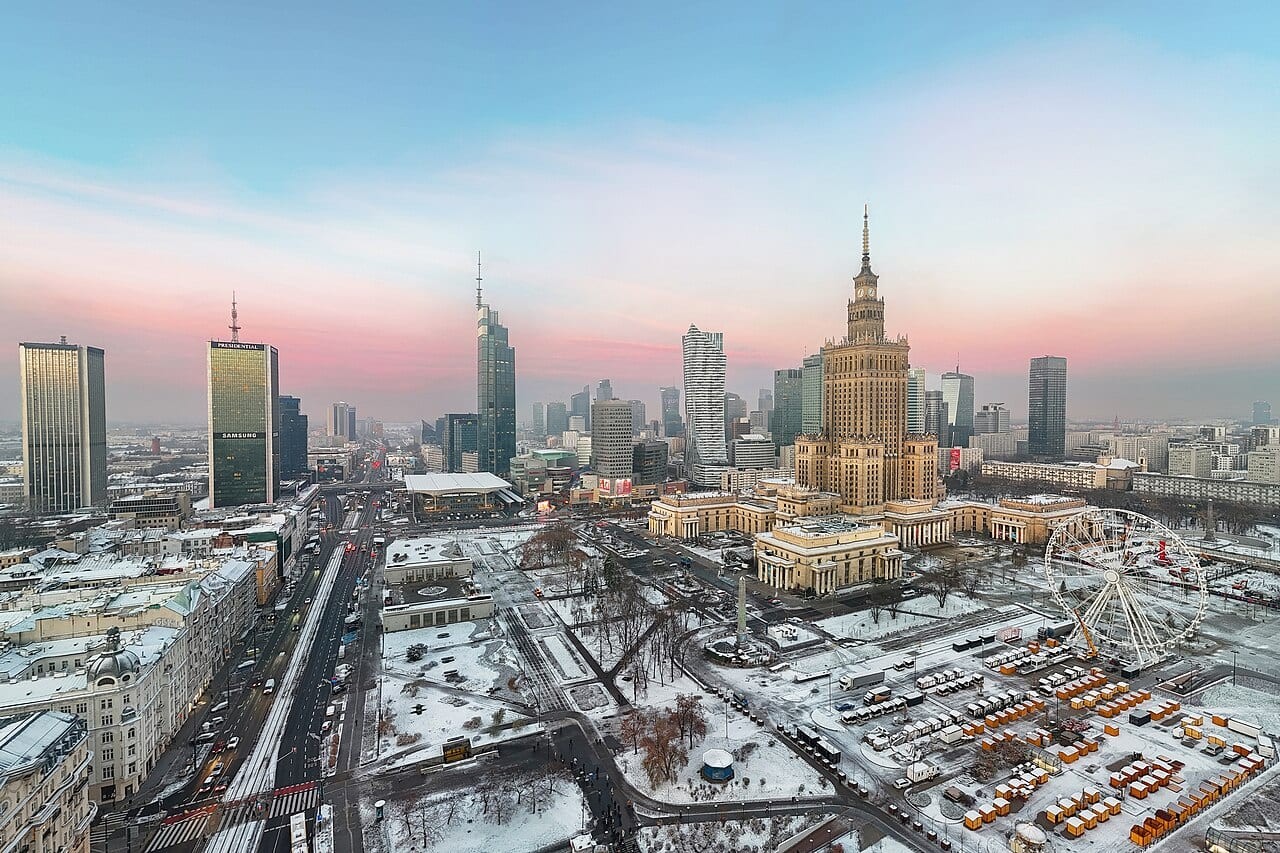
Warsaw City Guide
Poland
Warsaw is Central and Eastern Europe's most liquid and dynamic property market, anchored by Poland's standing as one of the EU's strongest-growing major economies. As the capital of a ~38-million-person nation that has avoided recession for three decades, the city combines deep domestic demand, a fast-expanding services and tech sector, and a maturing institutional investment scene. Residential prices have risen sharply since 2020 but remain well below Western European capitals, roughly €4,000–4,800/m² citywide versus €10,000+ in Paris or London, leaving room for the 'economic convergence' thesis that values and rents rise faster here than in mature markets. The market entered a stabilisation phase in 2025 after several years of double-digit growth: Q1 2025 resale prices averaged ~16,460 PLN/m² (+8.1% YoY), while the broader seven-city market cooled to roughly flat YoY by Q3 2025 as affordability and the end of subsidised-mortgage schemes tempered demand. Gross rental yields remain attractive by EU-capital standards at roughly 5–6.5%, supported by a structural rental shortage and strong student/expat demand. For foreign investors, Warsaw's appeal is reinforced by an open ownership regime, non-EU buyers can purchase standalone apartments with no permit, low transaction friction (2% transfer tax on resale), and a value gap against Western Europe. The main risks are PLN currency exposure, the recent cooling in price momentum, and a national short-term-rental registration regime taking effect from May 2026.

Dorado
Puerto Rico
Dorado, on the north coast about 30 minutes west of San Juan, is Puerto Rico's most exclusive and most expensive real estate market - anchored by the gated Dorado Beach resort, a Ritz-Carlton Reserve community built around a former Rockefeller estate. As a U.S. territory, Puerto Rico places no restrictions on foreign or mainland ownership: buyers acquire freehold in U.S. dollars with standard title insurance. Act 60 is the defining force here; qualifying new residents secure 0% capital gains on post-residency appreciation, a 4% corporate rate for eligible export-services businesses, and major income-tax exemptions, and they must buy a primary residence within two years of their decree - which is why the wealthiest relocatees cluster in Dorado Beach. Pricing reflects that: entry condos and villas start near $800,000-$1.5M, single-family homes in Dorado Beach East and Plantation Village run $2.5M to $12M, and trophy estates in Legacy, The Enclave, and Dorado Beach Estates command $10M to $25M-plus, with 2026 median asking around $6M-$8M. Constrained supply against relentless relocatee demand has driven 38%-65% appreciation since 2020, with the luxury segment still appreciating 6%-14% year-over-year. Short-term luxury rentals command $10,000-$200,000 per month. Outside the gates, the town of Dorado offers more attainable beach and residential stock.
Ponce
Puerto Rico
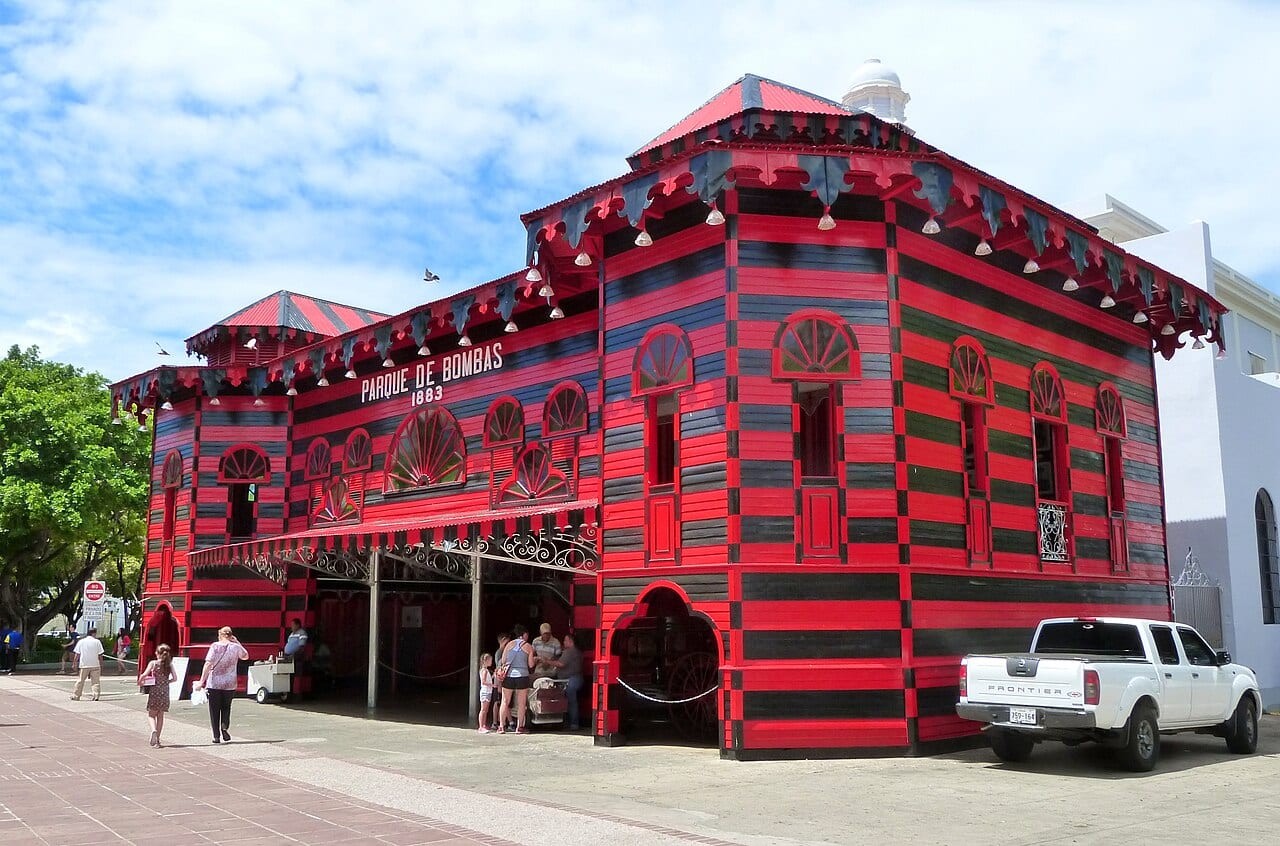
Ponce, the "Pearl of the South," is Puerto Rico's second city and the cultural capital of the south coast - a city of more than 130,000 known for neoclassical and Spanish-colonial architecture, the landmark red-and-black Parque de Bombas, and a well-preserved historic center. As a U.S. territory, Puerto Rico places no restrictions on foreign or mainland ownership; buyers acquire freehold in U.S. dollars with title insurance, and Act 60 incentives apply island-wide, though Ponce's appeal is value and rental fundamentals rather than ultra-luxury relocation. Pricing is dramatically more attainable than San Juan or the coastal resort towns: single-family homes average around $372,500, condos near $349,000, and the market hovers around $156 per square foot - among the best value on the island. A large resident population of over 130,000 provides a deep, stable long-term tenant base supporting gross yields commonly in the 6%-8% range. While island luxury appreciation ran 6%-14% year-over-year into Q1 2026, Ponce's mid-market has appreciated more modestly, offering a lower-cost, cash-flow-oriented entry. A decade of district renovation has revitalized residential areas and the colonial core, steadily attracting new residents and investors to the south coast.
Rincón
Puerto Rico
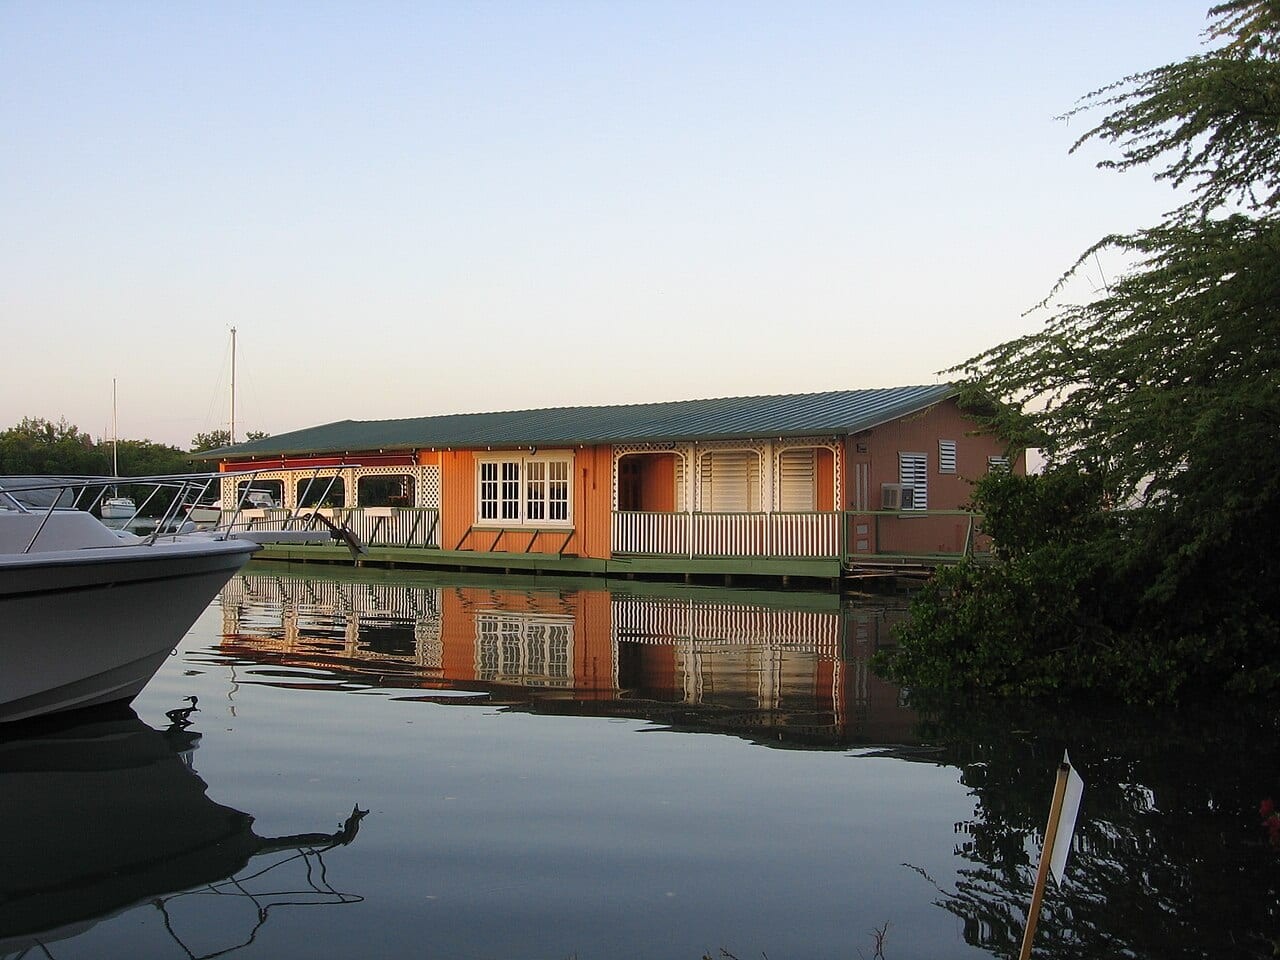
Rincón, on Puerto Rico's west coast, is the island's surf capital and most established vacation-rental town - a laid-back beach community famed for world-class waves, sunsets, and a steady influx of surfers, remote workers, and luxury vacationers. As a U.S. territory, Puerto Rico imposes no foreign-ownership restrictions; mainland and international buyers acquire freehold in U.S. dollars, and Act 60 tax incentives reach the west coast too, though Rincón's draw is lifestyle and rental yield more than ultra-luxury relocation. In 2026 the average condo trades around $1.66M at the high end, with condos selling near $310 per square foot; oceanview lots run $100,000-$400,000-plus and inland parcels start near $60,000, giving a wide range of entry points. The investment story is short-term rental performance: limited hotel infrastructure funnels tourists into private rentals, with STR datasets showing 43%-48% average occupancy and $255-$260 ADRs, while top-decile beachfront listings reach 79%-plus occupancy and $350-plus nightly in peak season. Prime beachfront and surf-adjacent property delivers the west coast's highest ROI. Appreciation tracks the island's broader 6%-14% luxury trend, supported by constrained coastal supply and rising remote-worker demand.
San Juan
Puerto Rico
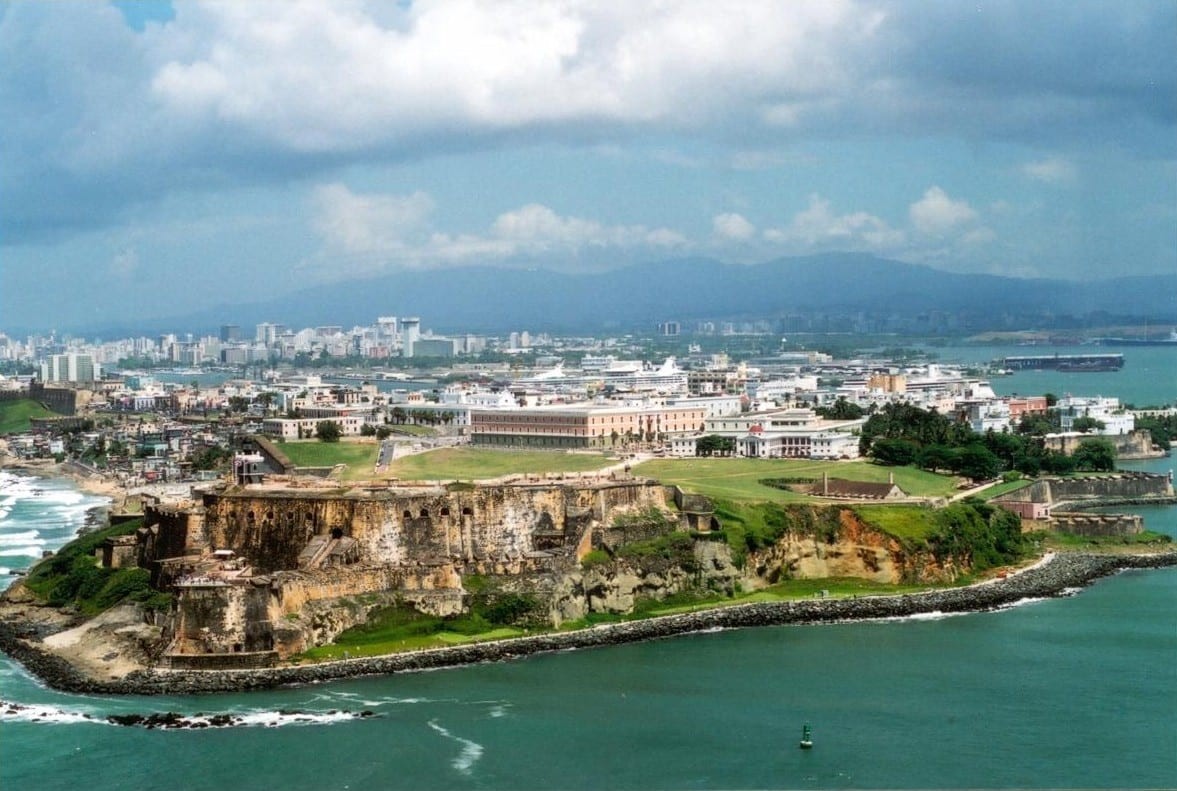
San Juan is the capital and economic heart of Puerto Rico, and the island's deepest, most liquid real estate market. As a U.S. territory, Puerto Rico imposes no restrictions on foreign or mainland ownership; non-residents buy freehold on identical terms to locals, closings run in English and Spanish, and the U.S. dollar is the currency. Act 60 (consolidating the former Acts 20 and 22) continues to draw high-net-worth relocatees, who must acquire a primary residence within two years of their decree, fueling demand in luxury enclaves like Condado. In 2026 the San Juan metro median sits near $654,000 with luxury oceanfront stock reaching $900,000-plus and an average around $527 per square foot. Gross apartment yields run roughly 3.5%-5.2% in the urban core (city average about 4.2%), while beachfront Isla Verde clears 6.7%-8% on short-term rental demand. Island-wide luxury appreciation held at 6%-14% year-over-year into Q1 2026, with Condado prices up 38%-65% since 2020. Short-term rental rules tightened under municipal registration requirements, but tourism volume keeps occupancy strong. San Juan blends colonial-era trophy property in walled Old San Juan with full-service oceanfront towers in Condado and Isla Verde, giving investors both heritage scarcity and resort-grade rental cash flow.
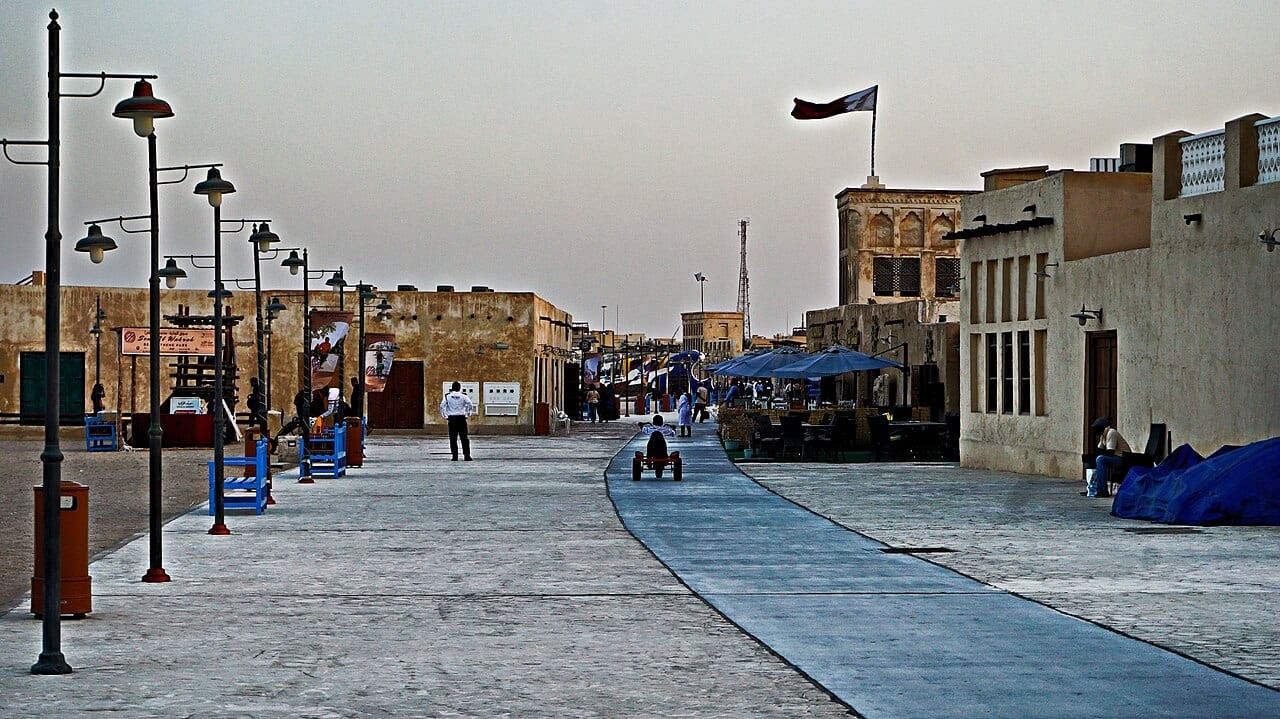

Al Wakrah City Guide
Qatar
Al Wakrah is Qatar's second-oldest and second-largest municipality, a coastal town just south of Doha that has grown from a pearling and fishing settlement into an affordable commuter and family destination, anchored by the restored 3 km Al Wakrah Old Souq and corniche. The market is value-oriented: mid-income housing is rising on the back of infrastructure spending, with prices up around 6% and gross rental yields typically in the 5-6% range. Foreign buyers should understand Qatar's zonal ownership system: under Law 16/2018, non-Qataris can own freehold only in designated zones and hold usufruct (up to 99 years) in others, and within Al Wakrah it is specific approved areas rather than the whole municipality that are open, so due diligence on the exact plot's status is essential.
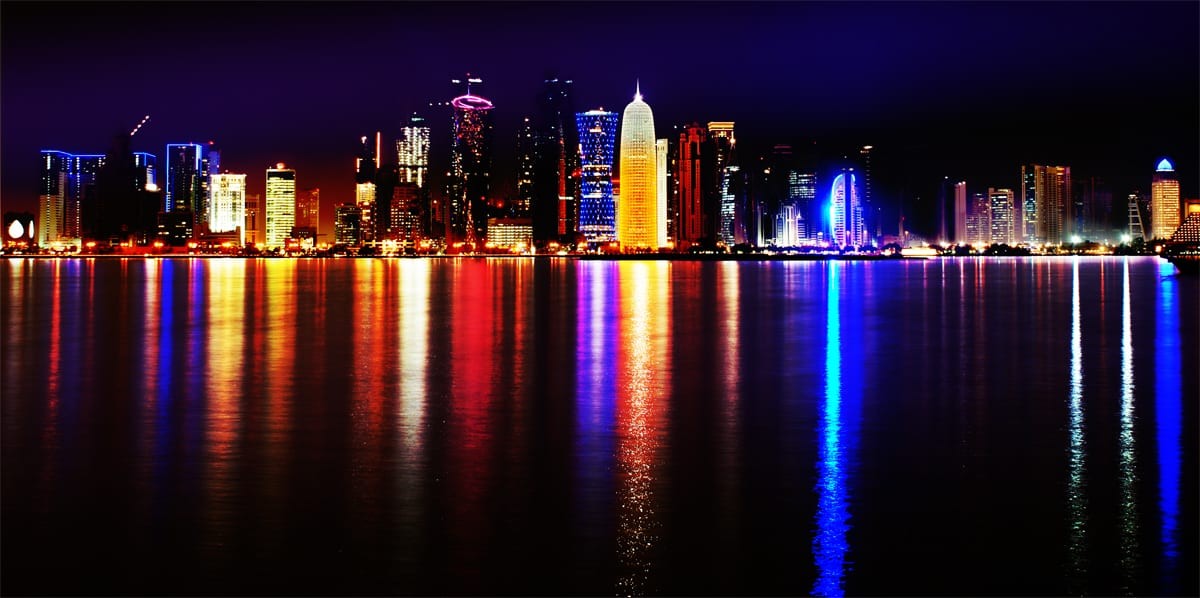
Doha City Guide
Qatar
Doha is the capital of Qatar and one of the Gulf's fastest-maturing investment markets, transformed by a decade of pre-World Cup infrastructure and now stabilising into a more sustainable cycle. For foreign buyers, Qatar's freehold framework concentrates opportunity in designated zones - above all The Pearl-Qatar and Lusail City, the master-planned waterfront developments that define the prime segment. Apartment capital values reached around QAR 10,420 per square metre in 2025, with one-bedroom units in The Pearl and Lusail starting near QAR 2.1 million (about USD 577,000), while mid-tier districts such as Al Sadd offer entry points from roughly QAR 1.2 million. Yields are healthy by global standards: Qatar's average gross rental yield was around 5.17% in early 2026, with The Pearl apartments averaging 4.57% (range 3.21-6.58%) and Lusail averaging 5.7% (up to 6.92%). The market turned a corner in 2025 - residential transactions rose 13.2% quarter-on-quarter and 67.1% year-on-year in Q1, and leasing activity accelerated through the year as rents stabilised. The principal headwind is supply: an estimated excess of more than 80,000 units lingers from the construction boom, so investors should favour premium waterfront stock in The Pearl, Lusail, and Qetaifan Island, which commands a 15-30% price premium and sells materially faster than inland units.
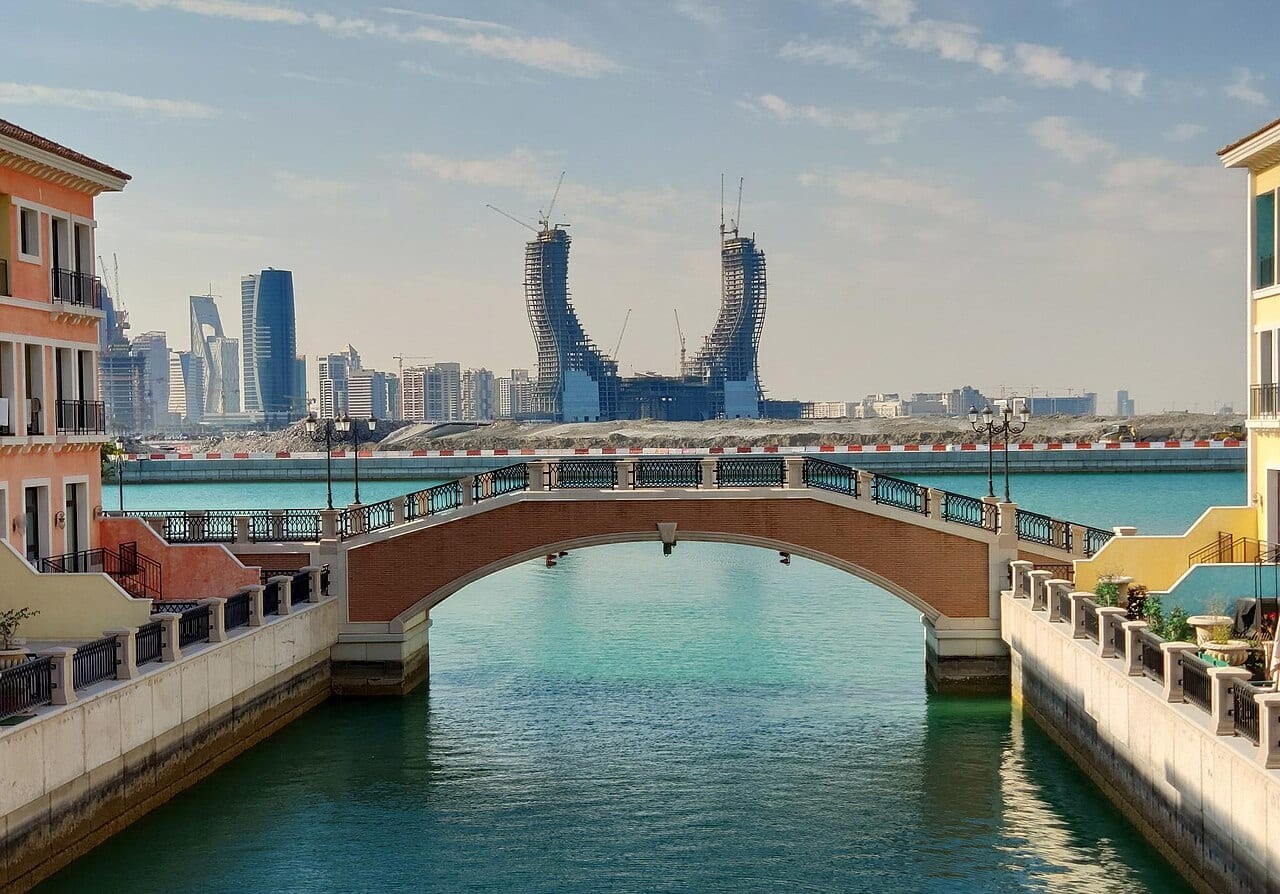
Lusail City Guide
Qatar
Lusail is Qatar's flagship planned smart city, a 38-square-kilometre development immediately north of Doha conceived around intelligent transport, district cooling, renewable power, and mixed-use waterfront districts. Designed to house more than 200,000 residents and employ around 170,000, it hosted the 2022 FIFA World Cup final at Lusail Stadium and is one of the Gulf's most ambitious urban projects. For foreign investors it is a designated freehold zone where non-Qataris can own property outright and qualify for residency tied to ownership. Apartment values held steady at roughly QAR 10,175 per square metre in Q1 2025, with marquee districts driving demand: the Marina District's waterfront towers, the more affordable Fox Hills mid-rise community, the Waterfront District (around 95% leased), and Energy City. Lusail residential prices rose about 7% in 2024, with luxury segments forecast to grow 10-12% in 2025 as delivery accelerates. Gross apartment yields average around 5.7%, with prime one- and two-bed units reaching 6-7%. Backed by Qatari Diar and billions in committed infrastructure, Lusail enters 2026 as the headline new-build investment address in Qatar, a stable, tax-light, US-dollar-pegged Gulf market.
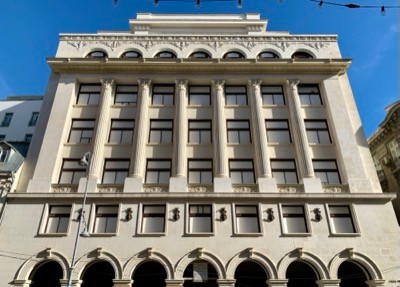

Bucharest City Guide
Romania
Bucharest (București) is Romania's capital and largest city — population 1.72M (city) / 2.27M (metro) — and the EU's 6th-largest capital. Founded ~14th century, the city earned the moniker 'Little Paris' for its Belle Époque + interwar modernist architecture before Communist-era construction layered massive boulevards + the Palace of the Parliament (world's heaviest building) onto the cityscape. Modern Bucharest combines this layered architecture with rapidly-growing IT/banking/professional services employment. Average property prices reached €2,204/m² in December 2025 (+16.6% YoY), with prime Sector 1 districts (Aviatorilor, Primăverii, Floreasca, Herastrau) at €4,600-€4,900/m² and yields among Europe's most attractive at 7.73-8.04% average.
Cluj-Napoca City Guide
Romania
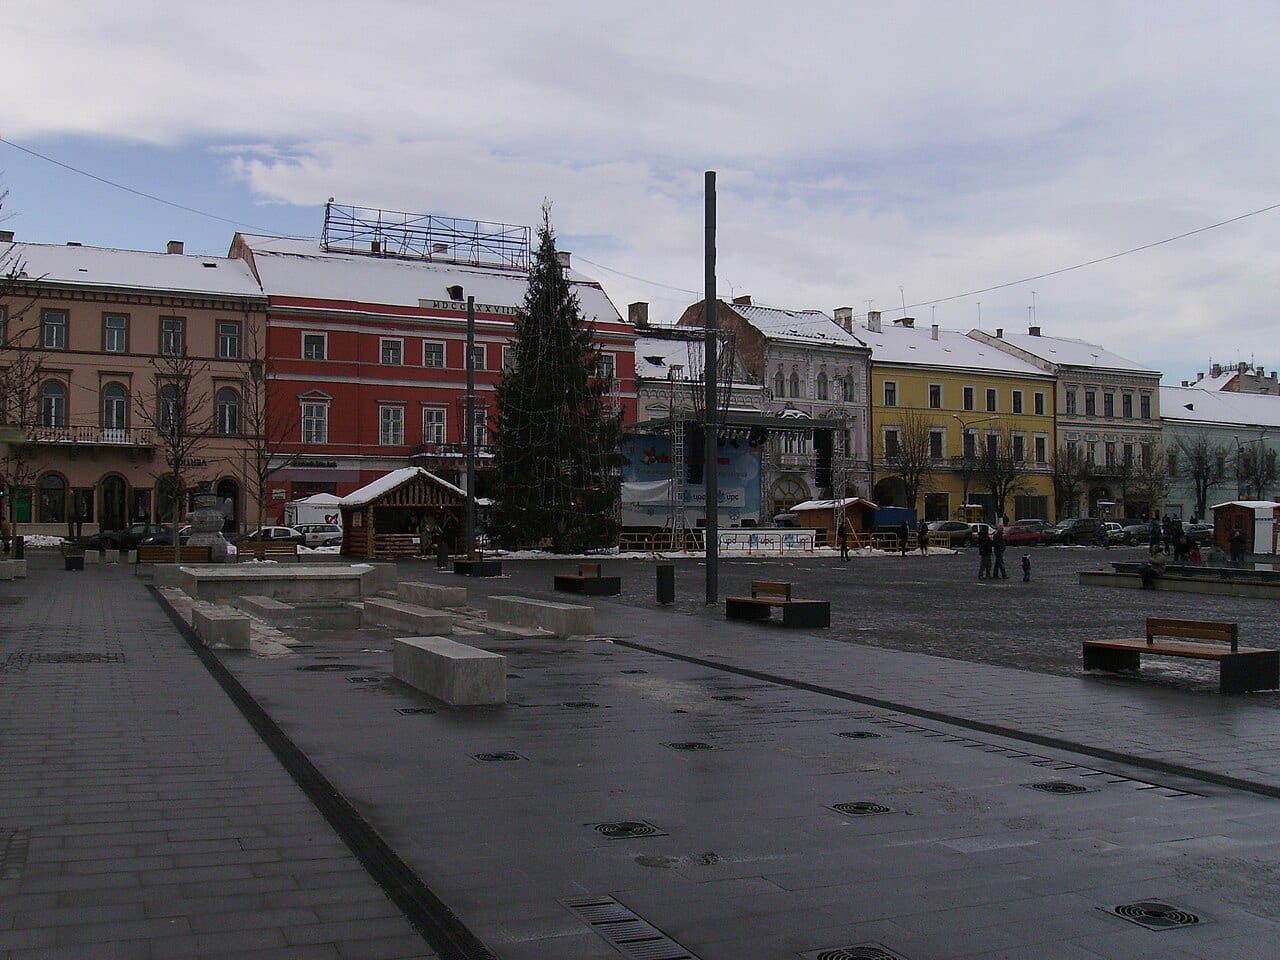
Cluj-Napoca is Transylvania's capital and Romania's leading tech and IT hub, home to 1,200+ tech companies and 20,000+ IT specialists, which has made it the country's most expensive housing market, the first Romanian city to break €3,000/m² (now ~€3,235/m²). A massive student base (Babeș-Bolyai University alone has ~50,000 students, plus five more universities) underpins year-round rental demand and the country's highest student-per-capita ratio. For investors it is a high-demand, tight-vacancy market: prime-area vacancy runs ~2–4% and well-priced units let in 7–15 days, with city-wide gross yields ~4.4% rising to 5–6.5% in value and student districts.

Belgrade City Guide
Serbia
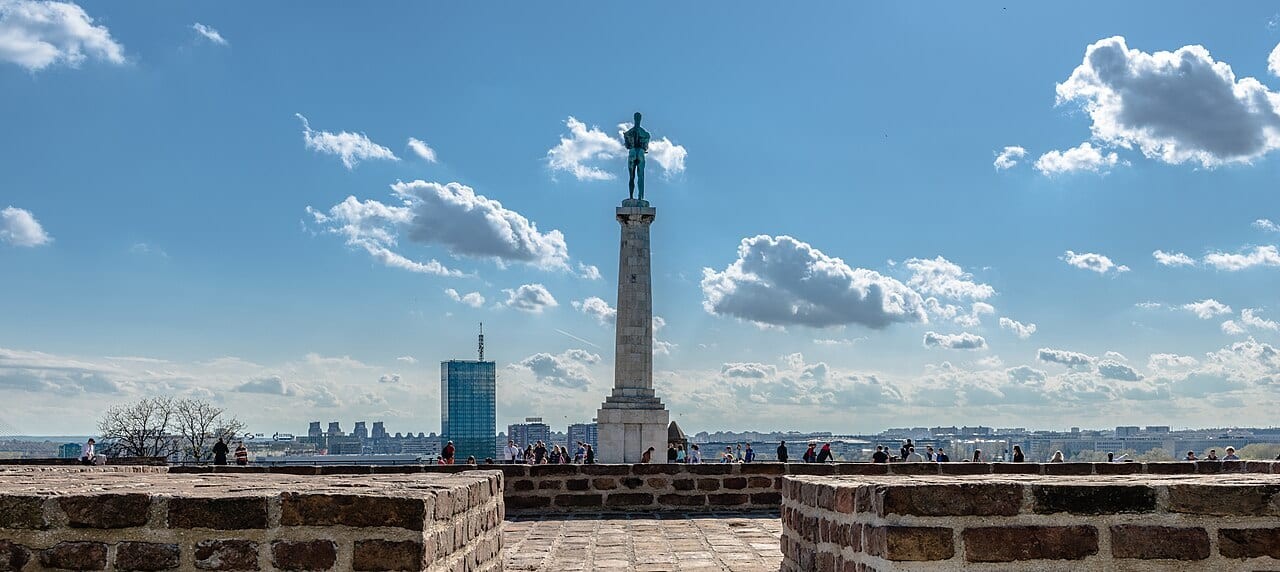
Belgrade is Serbia's capital and largest city, the economic and cultural heart of a metro area of roughly 1.4 million at the confluence of the Sava and Danube rivers. Over the past decade it has been one of the Balkans' most dynamic property markets, transformed by the multi-billion-euro Belgrade Waterfront (Beograd na vodi) regeneration of the riverfront, where penthouses have traded near EUR 9,800 per square metre. Citywide, average apartment prices sit around EUR 2,600 per square metre as of early 2026, with prime central districts, Stari Grad (the old town, near EUR 3,800/sqm) and Vracar (EUR 3,500-4,000/sqm), commanding the top end and the business-led Novi Beograd (New Belgrade) spanning roughly EUR 2,600-3,500/sqm. After several years of double-digit gains, the market has shifted to a steadier footing: prices rose about 5-6% year-on-year into the first half of 2026, with forecasts of moderate 4-7% growth and a central scenario near 5-6%. Gross rental yields in Belgrade average around 6.35%, with non-premium districts such as Zvezdara and Vozdovac offering stronger yield-to-price ratios than trophy central stock. A growing tech and services economy supports rental demand.
Novi Sad City Guide
Serbia
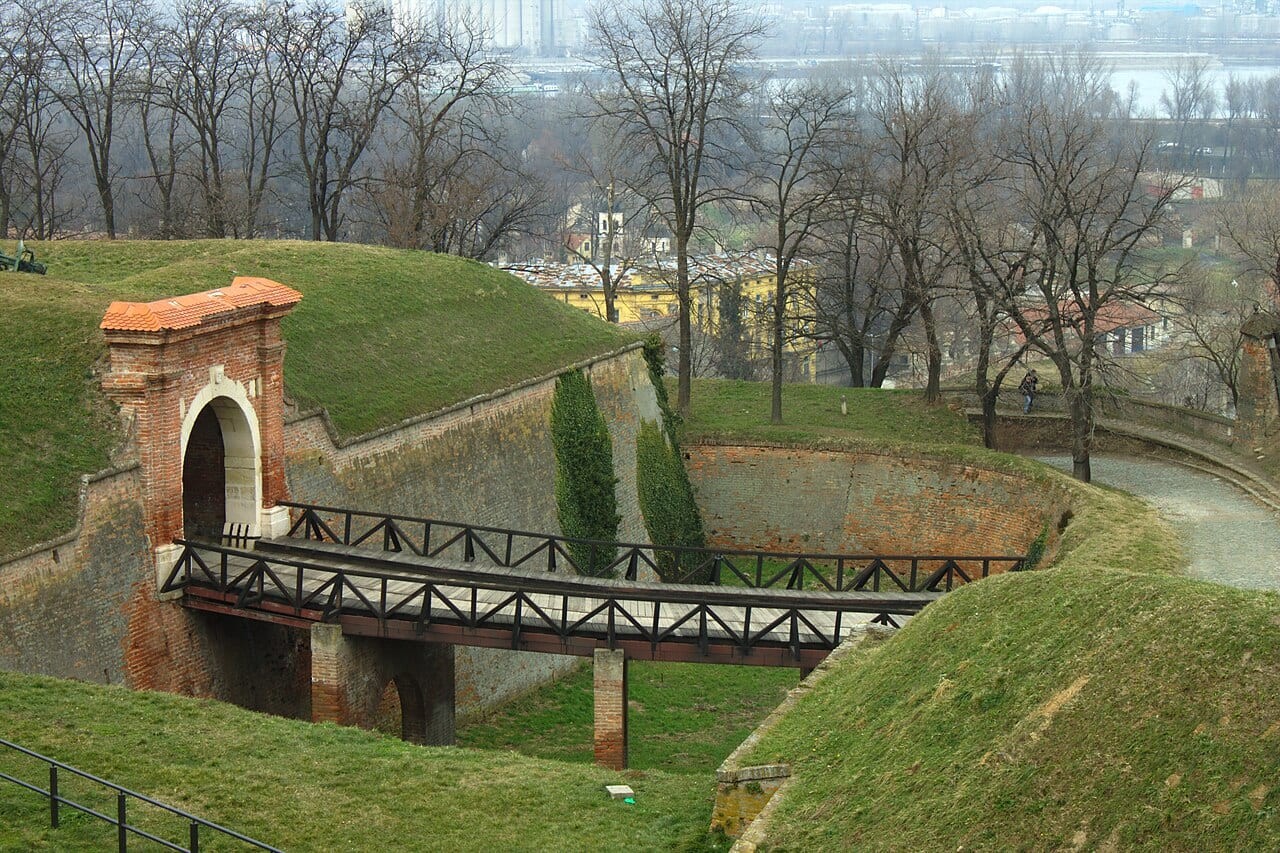
Novi Sad is Serbia's second-largest city and the capital of the autonomous province of Vojvodina, a Danube-side city of roughly 250,000 known historically as a cultural and university centre and increasingly as the country's fastest-rising technology hub. Its ICT sector employs an estimated 11,500-13,000 professionals across more than 380 companies, generating around EUR 420 million in annual revenue and accounting for roughly 28% of Serbia's IT exports despite the city holding about 12% of the national population. That tech-led growth, alongside the University of Novi Sad and the EXIT festival, is driving demand for modern apartments and office space. Average residential prices sit near EUR 1,800 per square metre as of 2025, well below Belgrade's EUR 2,600, making it a comparatively affordable entry point, with prices rising about 5-6% year-on-year in line with the national market. Asking rents run roughly EUR 10-12 per square metre, and gross rental yields average around 4.79%, lower than Belgrade's, reflecting Novi Sad's more end-user, owner-occupier character. The 2026 outlook is for broad stability with slower, steadier growth.

Victoria City Guide
Seychelles
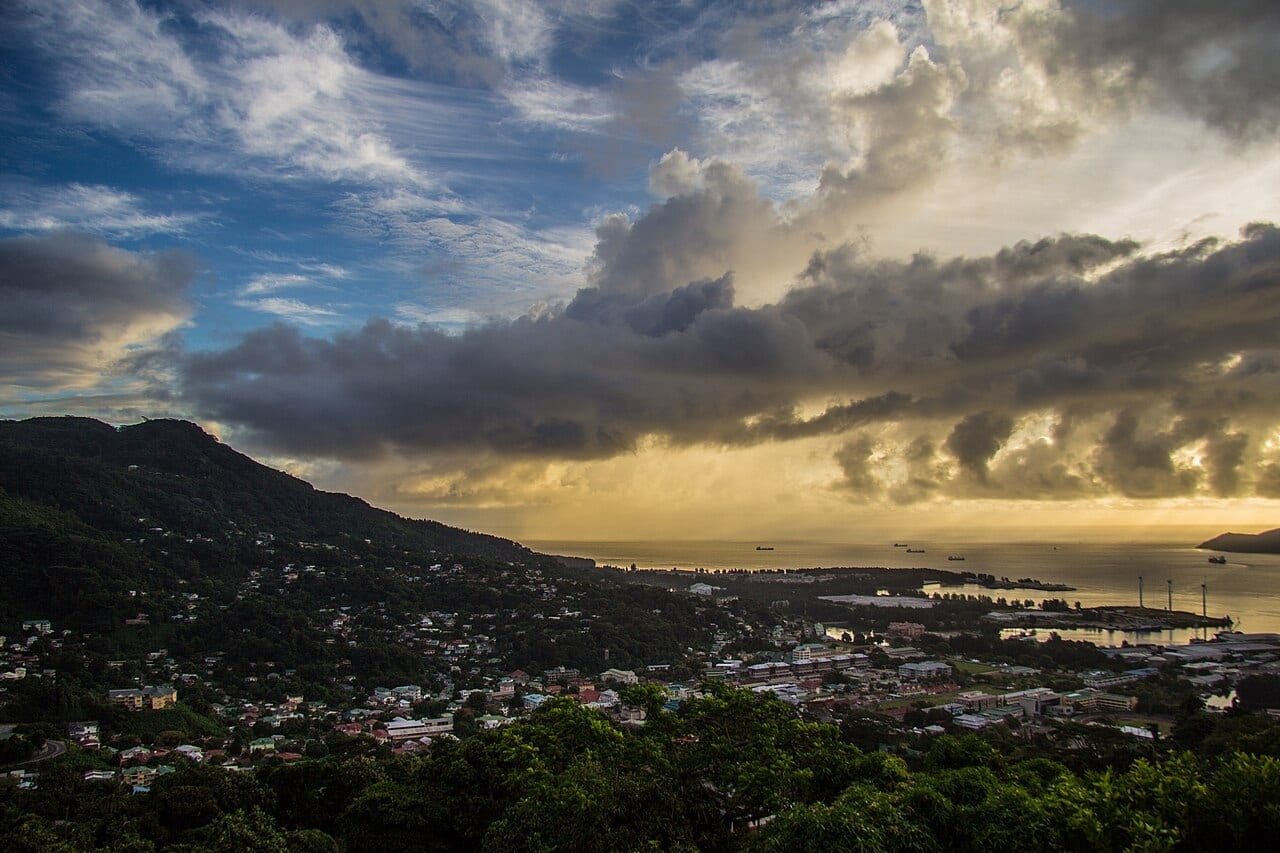
Victoria is the capital of Seychelles and one of the world's smallest national capitals, set on the north-east coast of Mahé, the largest island of the Indian Ocean archipelago. As the country's administrative, commercial, and port centre, Greater Victoria anchors the most accessible property market in a nation otherwise known for ultra-luxury resort villas. Listings across Seychelles average around US$1.3 million with a wide range from roughly US$480,000 to over US$25 million, and the marquee development for foreign buyers is Eden Island, a private, artificially created marina community off Mahé that is pre-approved for foreign ownership and reports strong rental demand and yields around 6–8%. The government lifted its foreign-ownership moratorium in January 2025; non-Seychellois must obtain a Government Sanction (typically a 5% fee), pay 5% stamp duty, and face an annual 0.5% property tax on foreign-owned property, but there is no capital gains or inheritance tax. Demand is underpinned by Seychelles' high-end tourism economy and political stability. The risks are the very small and illiquid market, the high entry price point, regulatory friction for foreigners outside designated developments, and exposure to tourism cycles and climate-related sea-level pressures.
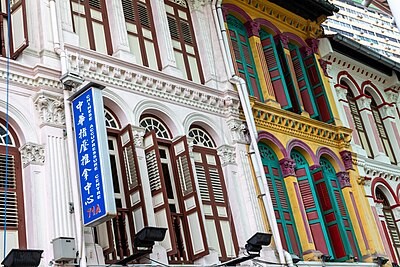

Rest of Central Region (RCR)
Singapore
Singapore's 'sweet spot' for property investment, the RCR spans Districts 3, 5, 7, 8, 12, 13, 14, and 15 — covering vibrant neighborhoods like Queenstown, Tiong Bahru, Toa Payoh, East Coast/Katong, and Bugis-Kampong Glam. Averaging SGD $1,896 PSF (Q1 2025), the RCR posted the strongest price gains of any region at +5.8% in 2024 and is forecast to grow 2.2-2.5% in 2026. Rich in Peranakan and Art Deco heritage, major government redevelopment plans, and excellent F&B culture, the RCR delivers the best balance of value, lifestyle, and capital growth potential.
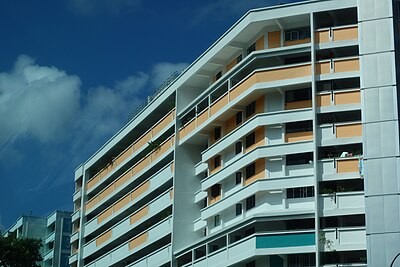
Outside Central Region (OCR)
Singapore
Singapore's most affordable and highest-yielding residential region, the OCR spans Districts 16 through 28 — covering major towns like Jurong East, Tampines, Woodlands, Punggol, and Sengkang. Averaging SGD $1,545 PSF (Q1 2025) with rental yields of 3.5-4.0% (the highest in Singapore), the OCR grew 3.7% in 2024 and is forecast to lead all regions at 2.8-3.0% in 2026. Backed by massive government infrastructure investment including the Jurong Lake District second CBD, Punggol Digital District, and new MRT lines, the OCR represents Singapore's most compelling long-term growth story.
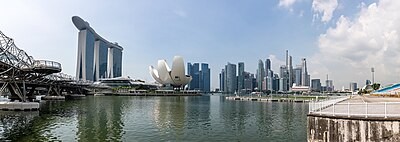
Core Central Region (CCR)
Singapore
Singapore's premium residential zone encompassing Districts 1, 2, 4, 6, 9, 10, and 11 — home to iconic addresses like Orchard Road, Marina Bay, Sentosa Cove, River Valley, Bukit Timah, and Novena. The CCR commands an average PSF of SGD $2,228 (Q1 2025) and attracts the highest share of foreign buyers of any region. After an 11.8% PSF correction following the 2023 ABSD hike, the CCR recovered with +4.5% growth in 2024 and is forecast to grow 1.8-2.0% in 2026. Luxury new launches regularly exceed SGD $6,000 PSF, with the strongest tenant demand from C-suite executives, finance professionals, and embassy staff.
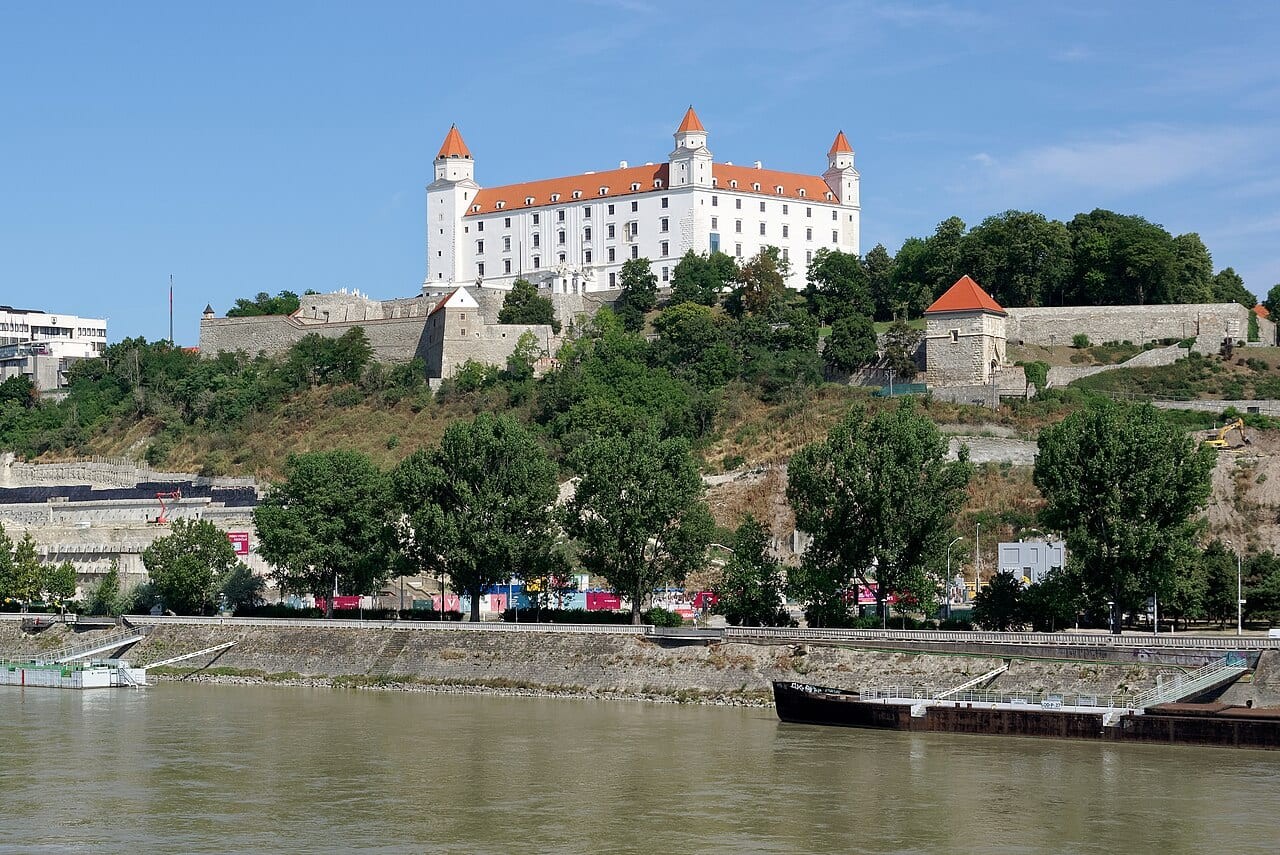

Bratislava City Guide
Slovakia
Bratislava is the capital and largest city of Slovakia, set on the Danube in the country's far southwest at the border of Austria and Hungary, roughly an hour from Vienna, making it half of one of Europe's closest capital-city pairings. The city proper holds ~475,000–480,000 registered residents (the municipality estimates over 500,000 actual), within a Bratislava Region of ~730,000 and a cross-border metro area approaching 1.3 million. Bratislava is the economic engine of Slovakia, generating roughly 26–30% of national GDP from under 10% of the population. Its economy is anchored by automotive manufacturing (Volkswagen Slovakia operates one of its largest plants here) alongside a fast-growing IT, shared-services and financial sector. The Bratislava Region has long ranked among the wealthiest in the EU by GDP per capita in purchasing-power terms. Slovakia joined the EU in 2004 and adopted the euro in 2009, giving Bratislava eurozone currency stability and frictionless capital access. Combined with open foreign-ownership rules (non-EU buyers can purchase residential property freely; only agricultural/forest land is restricted), low transaction costs (NO real-estate transfer tax), and the most liquid, highest-priced property market in the country, Bratislava is Slovakia's primary destination for domestic and international real-estate investment. Note: Slovakia has no golden-visa / residence-by-investment programme, buying property does not grant residency.