City guides
City guides (402)
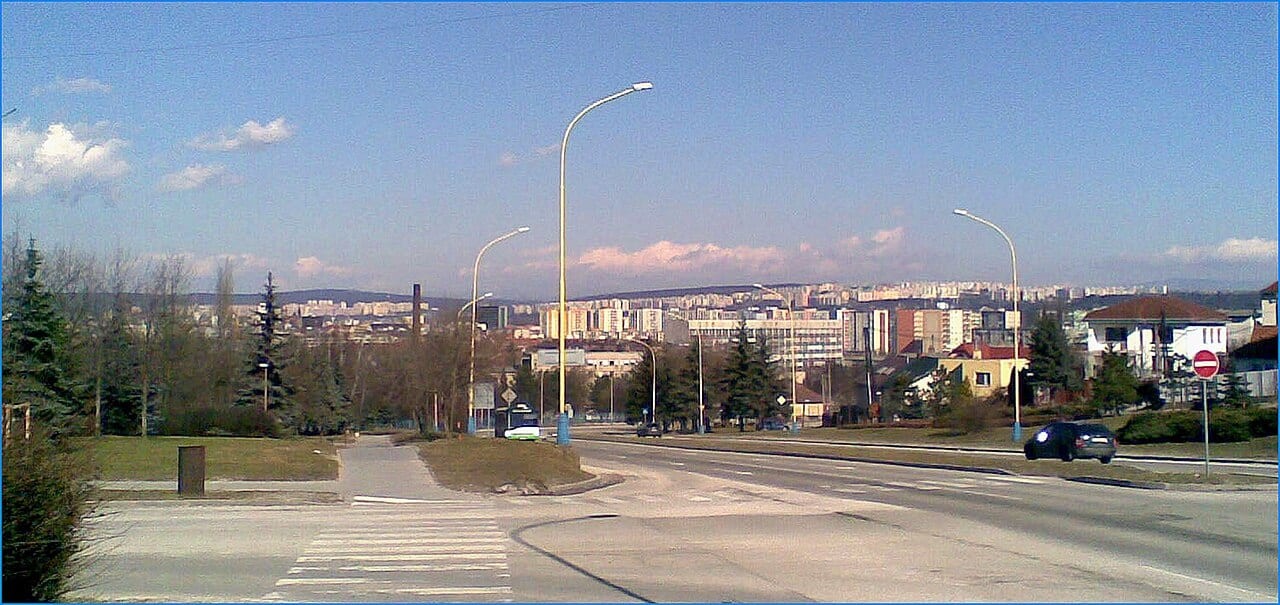

Kosice City Guide
Slovakia
Slovakia's second-largest city and the metropolis of the country's east, Košice has emerged as one of Central Europe's strongest catch-up property markets. With a population around 230,000, a Gothic old town centred on St Elizabeth's Cathedral, a major steelworks (U.S. Steel Košice), a growing IT and shared-services cluster, and over 50 recent startups, the city combines industrial heft with a young, mobile workforce. Property values surged in 2025, with prices per square metre rising about 20% year-on-year to roughly EUR 2,500, the fastest regional growth in Slovakia alongside neighbouring Presov, yet Košice remains markedly cheaper than Bratislava. Rental yields run above the national average at around 5.2%, with well-positioned two- and three-room apartments among the best performers; rents of roughly EUR 720 per month are the highest of Slovakia's regional cities, supported by an occupancy rate near 85%. As a Eurozone member, Slovakia offers currency stability, and a planned Volvo electric-vehicle plant in the wider eastern region (production targeted for 2027) is expected to add further housing demand. For investors, Košice offers Bratislava-adjacent fundamentals at a meaningful discount with clear appreciation momentum.

Ljubljana City Guide
Slovenia
Ljubljana is Slovenia's capital and largest city — population 295-297K (metro) — and one of Europe's most well-preserved Baroque-Art Nouveau-Modernist capitals. The city was substantially redesigned by Slovenian architect Jože Plečnik in the 1920s-1940s (the Triple Bridge, Žale Cemetery, National + University Library), giving Ljubljana a uniquely coherent architectural identity. Modern Ljubljana hosts Slovenia's government, central bank, university (founded 1919), a growing tech sector, and the EU's 3rd-greenest capital (Tivoli Park 5 km², plus Šmarna Gora + Rožnik hill access). Median property prices reached €4,510/m² for 2nd-hand apartments — making Ljubljana 55% more expensive per square metre than the Slovenian national median. The city is the highest-priced Slovenian market. Gross rental yields average 4.34%.
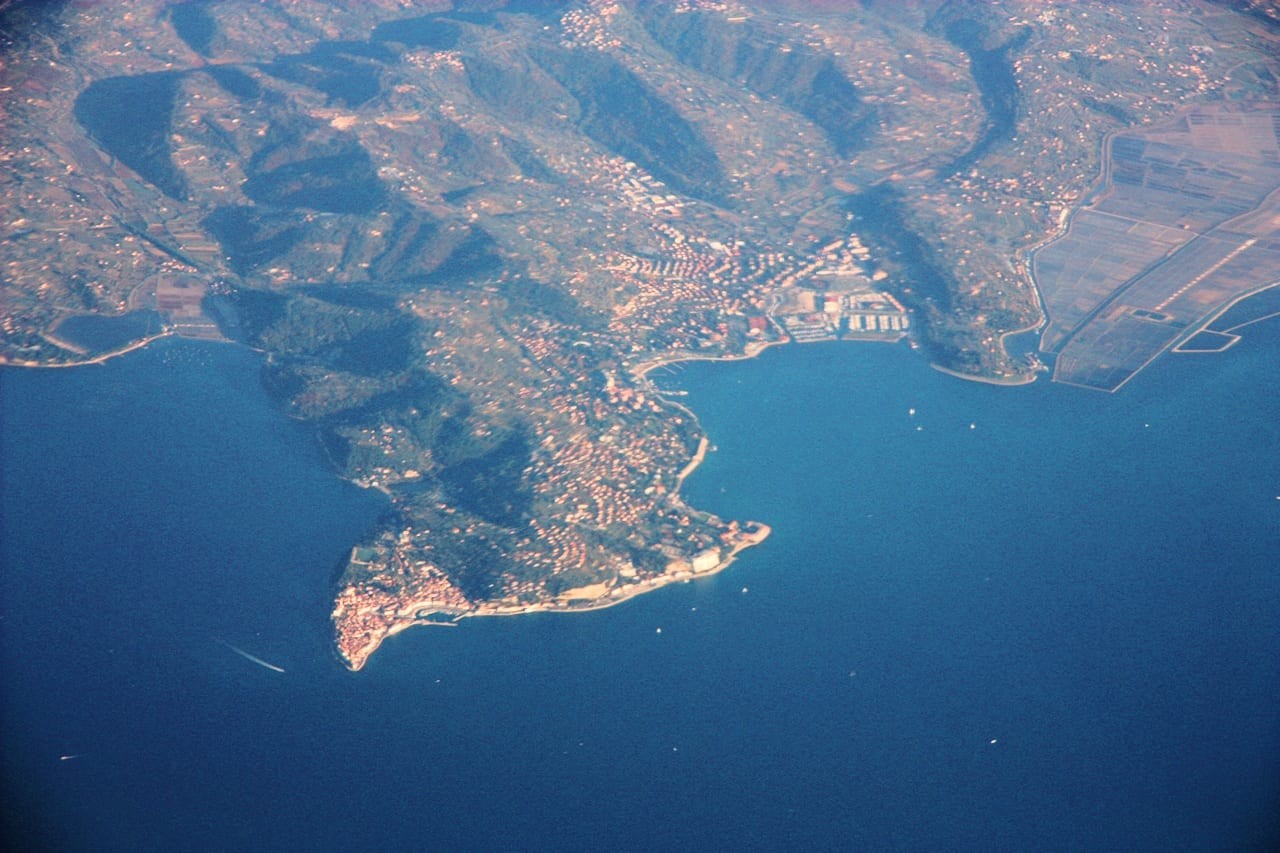
Piran City Guide
Slovenia
Piran is the jewel of Slovenia's short 47-kilometre Adriatic coast, a near-perfectly preserved Venetian-Gothic town of tile roofs, marble squares, and a medieval harbour that ranks among the most photogenic on the Mediterranean. As a protected heritage zone with almost no scope for new construction, its property market is defined by scarcity: Old Town apartments fetch roughly EUR 4,500-7,000 per square metre, and rare seafront or harbour-facing units reach up to EUR 8,500. Across the wider Obala coastal belt, which includes Koper, Izola, Portoroz, Ankaran and Piran, older apartments carried a 2024 median around EUR 4,320 per square metre, comparable to the capital Ljubljana. Demand is overwhelmingly lifestyle-led: second-home buyers, retirees, and capital-preservation investors drawn by the heritage setting, the adjacent Portoroz resort and marina, and Slovenia's Eurozone and EU stability. National prices cooled to about 2.7% year-on-year by Q3 2025 after a 7.6% gain in 2024, and Slovenia's average gross rental yield sits near 4%. Piran is therefore a capital-appreciation and lifestyle play rather than a high-income one. With a municipal population near 18,000 and tightly capped supply, it enters 2026 as Slovenia's premier coastal address.
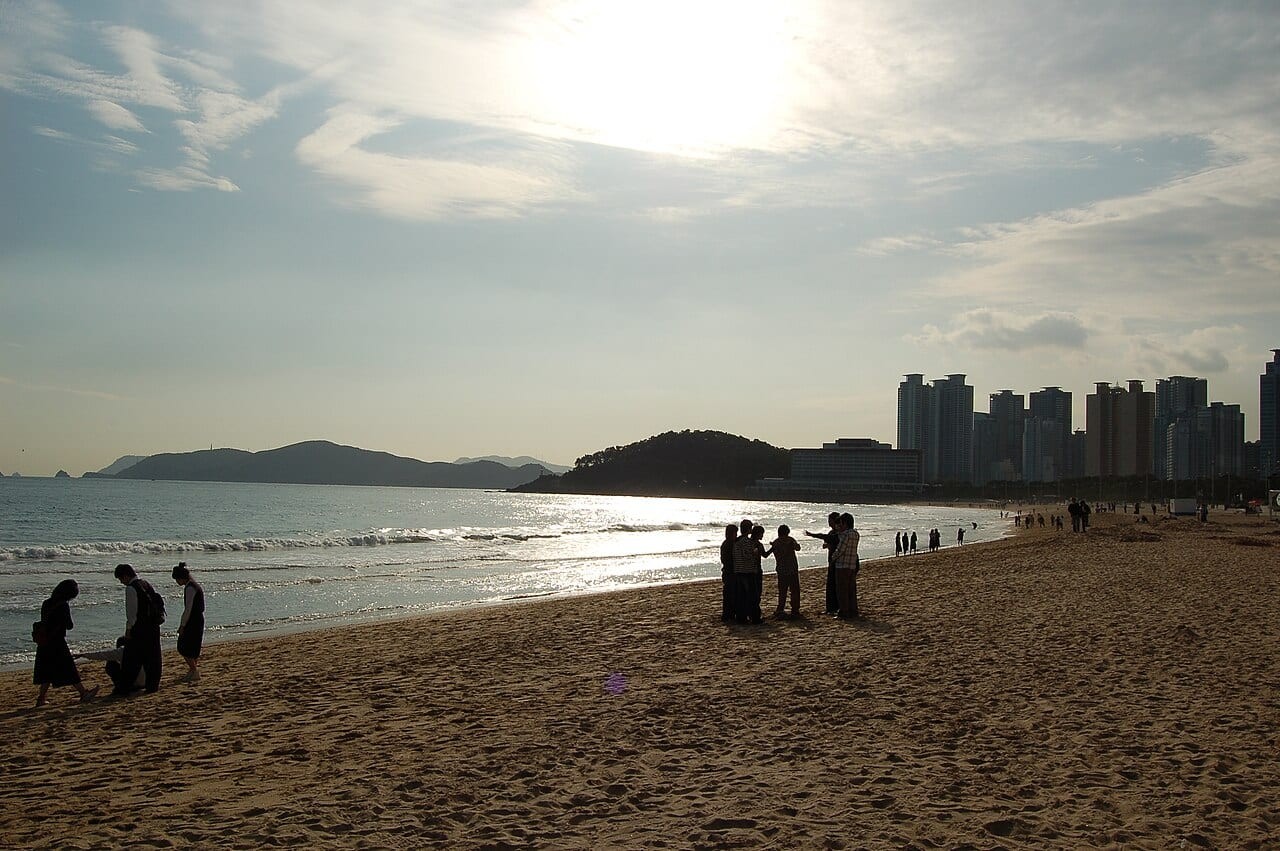

Busan City Guide
South Korea
Busan is South Korea's second-largest city and its maritime gateway, home to one of the world's busiest container ports and a coastal lifestyle that has made it the country's premier domestic and short-let tourism destination. For investors, Busan offers a markedly more affordable entry point than Seoul - average prices sit near KRW 6.69 million per square metre, so a standard 84-square-metre apartment typically falls in the KRW 420-500 million range (roughly USD 295,000-350,000), with living costs 10-25% below the capital. The marquee districts cluster along the coast: Haeundae, with its beachfront high-rises and the LCT skyscraper complex, and neighbouring Gwangalli, prized for its beach and the Gwangan Bridge skyline, command the city's top values and the strongest short-let demand. The central business and retail hub of Seomyeon in Busanjin-gu anchors long-term rental demand, while Marine City and Centum City reinforce Haeundae's status as the luxury core. After prices softened around 5% from their 2024 peak, 2025 turned modestly positive (individual housing prices up roughly 1.47%), creating a relative buyer's market. Long-term residential yields are thin at 1.5-2%, but studios and officetels in tourist hotspots can achieve 3-5% gross via short-let, supported by over 1.8 million foreign visitors and a booming Airbnb segment.
Seoul City Guide
South Korea
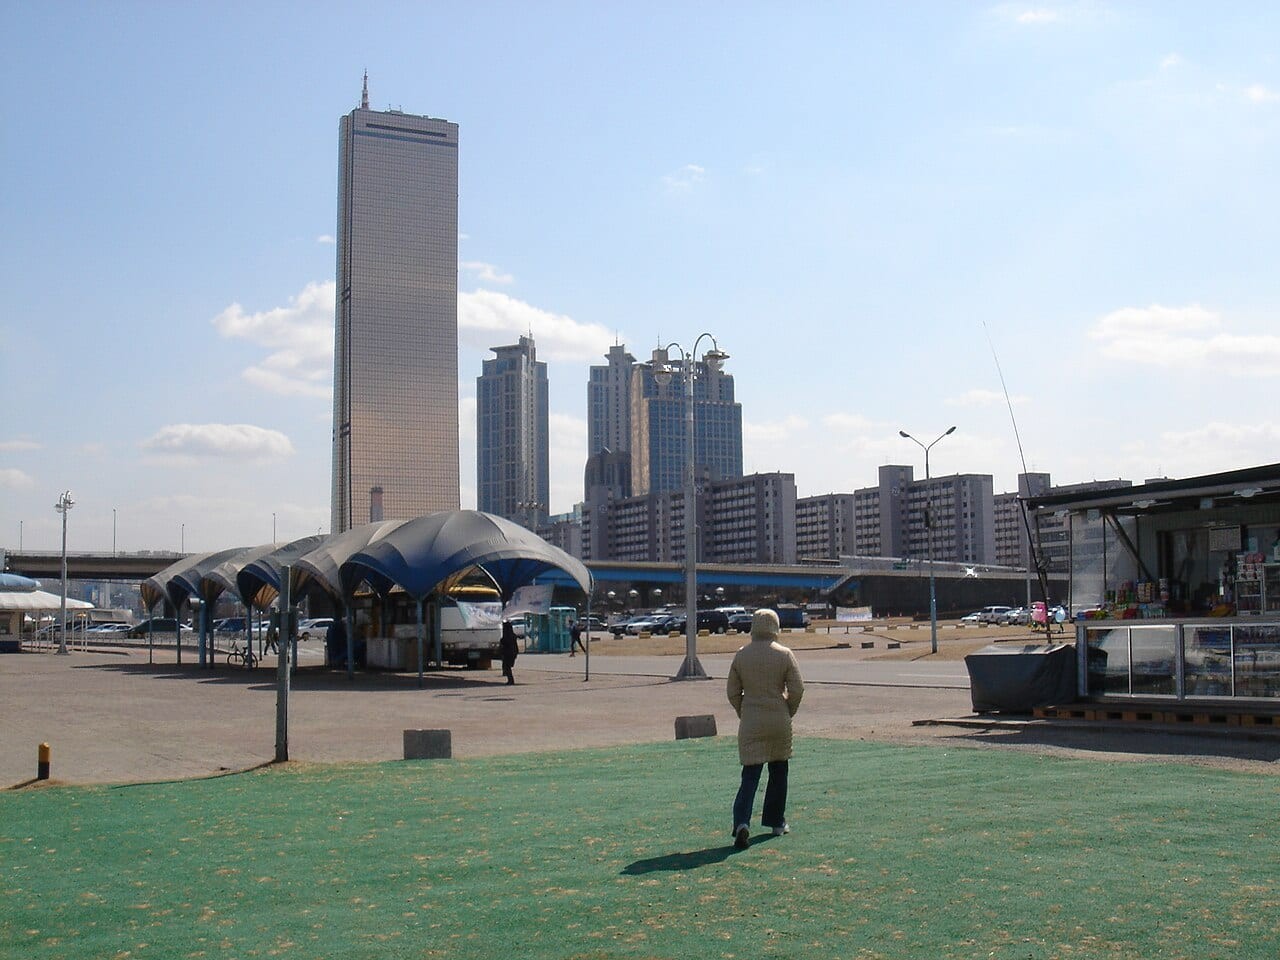
Seoul is the financial, technological, and cultural engine of South Korea, concentrating roughly half of the nation's economic output within its metropolitan region and hosting the global headquarters of Samsung, Hyundai, LG, and SK. For property investors, the capital pairs deep, liquid demand with one of Asia's most acute structural undersupply problems: limited new housing relative to household formation has continued to compress vacancies and push prices higher across the city's marquee districts. The luxury benchmark remains Gangnam, where prime apartments command KRW 25-40 million per square metre, alongside the riverside towers of Seocho and the redeveloping Yongsan district anchored by the International Business District. More accessible entry points exist in Mapo, home to the Hongdae creative cluster and Yonsei University, and in eastern districts such as Seongdong, where the Seongsu-dong tech and design scene has driven rapid gentrification. Citywide average prices sit near USD 9,272 per square metre, with Seoul homes averaging close to KRW 1.4 billion - roughly three times the national figure. After apartment prices rose approximately 8.7% in 2025, the fastest annual gain in nearly two decades, the Bank of Korea and macroprudential lending curbs have moderated the trajectory into 2026, leaving Seoul a high-conviction capital-growth market underpinned by scarcity rather than yield.

Basseterre City Guide
St Kitts and Nevis
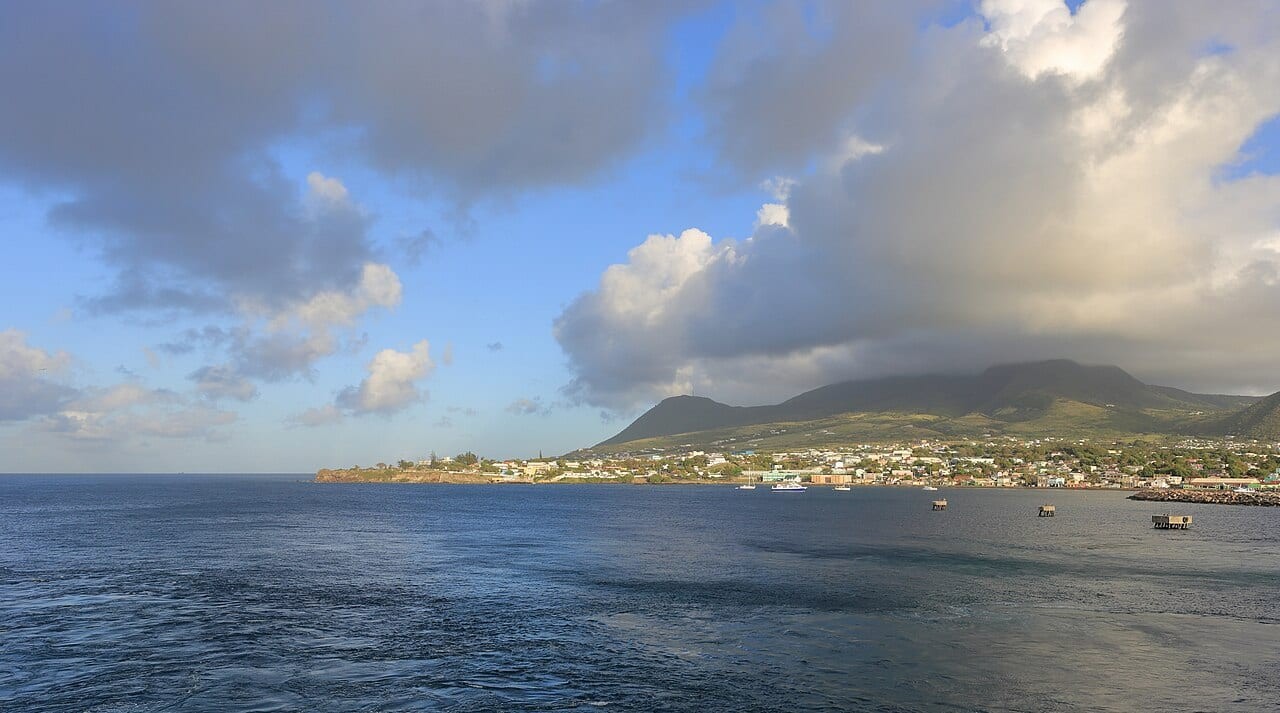
Basseterre is the capital of St Kitts and Nevis and the commercial and cruise gateway of the two-island federation, sitting on the south-western coast of St Kitts around the colonial-era Independence Square and the bustling Port Zante cruise terminal. Home to roughly a third of the nation's population within Saint George Basseterre Parish, the city anchors a property market built almost entirely around the world's oldest Citizenship by Investment programme, launched in 1984. Foreign demand concentrates on the Frigate Bay corridor and the South East Peninsula, where hotel-branded condos and resort residences start near US$325,000 and modern single-family homes with sea views run US$400,000 to US$1 million. Tourism is the dominant economic engine, the federation welcomed more than 800,000 visitors in 2025, the bulk arriving by cruise at Basseterre, which underpins short-let demand but also exposes the market to seasonality and cruise-traffic volatility. Buyers are drawn by US-dollar-pegged pricing (the EC dollar is fixed to the USD), no personal income tax, and a stable, English-speaking common-law jurisdiction, though the small, illiquid market and reliance on the CBI programme remain the central risks to capital values.

Castries City Guide
St Lucia
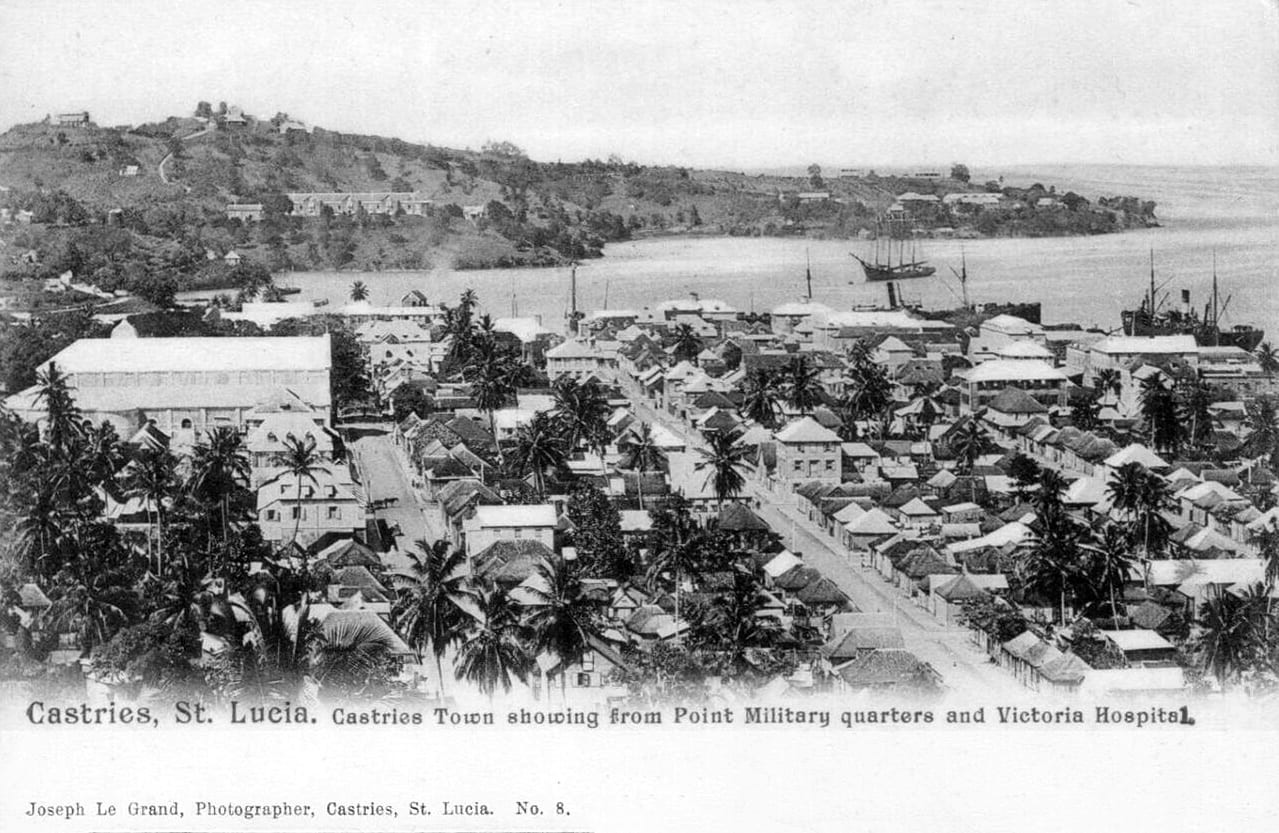
Castries is the capital and economic heart of St Lucia, set around a sheltered natural harbour on the island's north-west coast and serving as the country's main cruise port, administrative centre, and commercial hub. The Castries Quarter holds the largest concentration of urban housing, apartment buildings, and commercial property on the island, and the surrounding north-coast corridor toward Gros Islet and Rodney Bay carries the bulk of foreign-buyer and resort activity. Sea-adjacent one-bedroom apartments start around US$212,000 while colonial villas in the prime north can exceed US$5 million, with average prices roughly US$1,200 per square metre in the city and higher near the coast. Rental yields are seasonal and tourism-led, typically 3–5% on long lets but materially higher in peak season on well-placed short-term rentals. St Lucia's Citizenship by Investment programme channels much of the international interest, and a 2–5% property transfer tax applies. Castries is the most expensive place to live on the island; the key risks are the small, illiquid market, exposure to tourism cycles and hurricane season, and pricing that is the steepest in St Lucia.

Gothenburg City Guide
Sweden
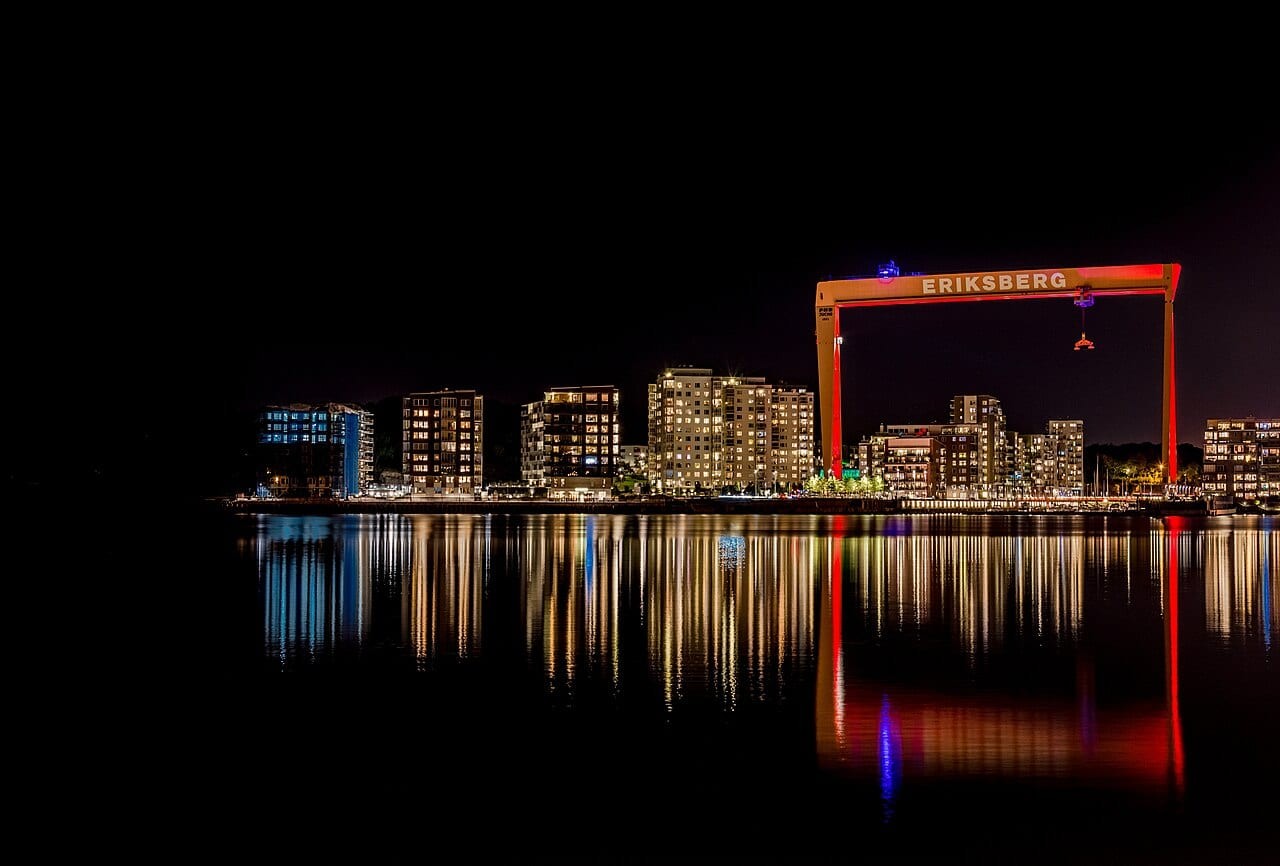
Sweden’s second city and the largest port in the Nordic region, Gothenburg pairs a deep industrial base, Volvo Cars, Volvo Group, SKF, and AstraZeneca all anchor here, with a fast-modernising innovation economy clustered around the Lindholmen Science Park on Hisingen island. For international investors the appeal is straightforward: entry prices materially below Stockholm’s, the strongest population growth of any major Swedish city (around 170,000 new residents since 2009), and a chronically tight rental market that keeps urban vacancies low. Central living revolves around the boutique-lined streets of Linnéstaden and Vasastaden, while gentrifying Majorna and the redeveloping waterfront of Hisingen, site of the multi-decade RiverCity / Älvstaden regeneration, are reshaping where younger professionals choose to live. The wider Gothenburg market priced in the mid-range nationally at roughly SEK 5,400 per square metre, sitting between Stockholm’s premium and Malmö’s discount. After two flat years following the 2022–23 correction, the Swedish market is forecast to recover in 2026, with national prices projected to rise around 5–6% as the Riksbank eases rates. With a metropolitan population of roughly 1.1 million and an economy diversifying from heavy industry into mobility, life sciences, and clean tech, Gothenburg offers a stable, liquidity-rich entry point into the Eurozone-adjacent Nordic property market.
Stockholm
Sweden
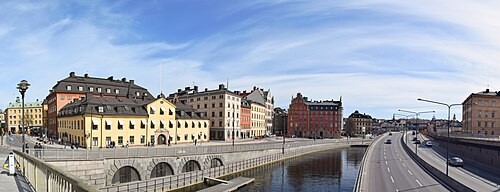
Stockholm is Sweden's capital, the largest city in the Nordics, and Europe's second-most active startup ecosystem on a per-capita basis -- producing Spotify, Klarna, King, Mojang, and a steady stream of unicorns. The city's 14-island archipelago, low-rise heritage, and aggressive municipal planning constraints make for one of Europe's most supply-restricted markets. Central residential (Ostermalm, Vasastan, Sodermalm, Kungsholmen) commands SEK 90,000-145,000 per square metre (EUR 8,000-13,000), with gross yields of 3.0-4.2%. Sweden's unusual rental market features dominant cooperative ownership (bostadsratt) and a regulated first-hand rental sector with long waiting lists -- making the cooperative market the de facto investment channel. For international buyers, Stockholm offers EU/EEA standing, English-friendly business culture, and a tech-heavy tenant base. Sweden has no restrictions on foreign property ownership. The catch: the bostadsratt system requires board approval, mortgage rates have only just started to ease (Riksbank cuts in 2025), and Swedish krona volatility adds FX risk for non-EUR investors.

Basel City Guide
Switzerland
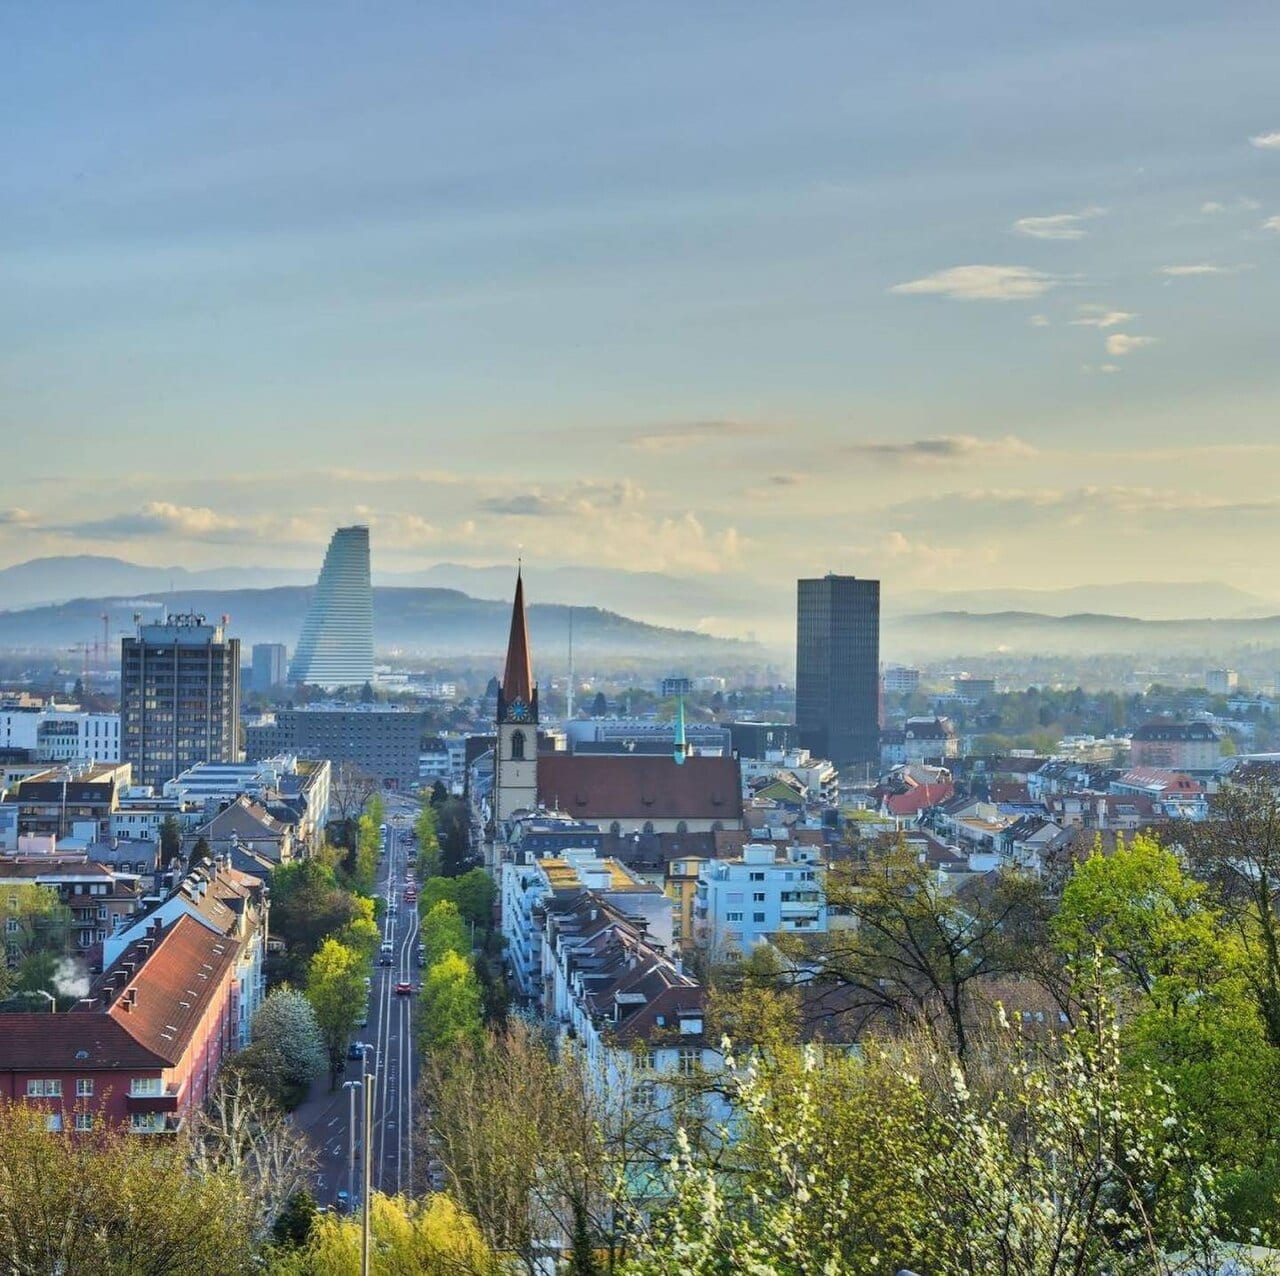
Switzerland's life-sciences capital and a tri-border hub where the country meets Germany and France, Basel anchors its property market on one of the world's most resilient employment bases: the global headquarters of Roche, Novartis and Lonza, plus a dense pharmaceutical and biotech cluster that draws high-earning international professionals. This translates into exceptionally tight housing, with citywide vacancy below 1.2% and the Gundeldingen and St. Johann quarters running below 0.5%. Residential prices average roughly CHF 8,500 per square metre, with prime hillside addresses such as Gellert, Bruderholz and St. Alban, and the ultra-prime suburb of Riehen, reaching CHF 9,500–CHF 10,500 and beyond. As is typical for Switzerland, yields are modest and income-led: gross rental yields range roughly 3.0–4.2%, with the strongest returns in mid-market areas like Kleinhüningen, Matthäus and parts of Iselin, while prime apartments compress toward 2.4%. Prices are expected to appreciate a measured 2–4% through 2026, tracking slightly below Zurich. Basel is not a market for aggressive capital growth or speculative flips; rather, its structurally stable pharma employment, sub-1% vacancy and Swiss-franc safe-haven status make it a premier choice for conservative investors prioritising capital protection and consistent rental income.
Geneva
Switzerland
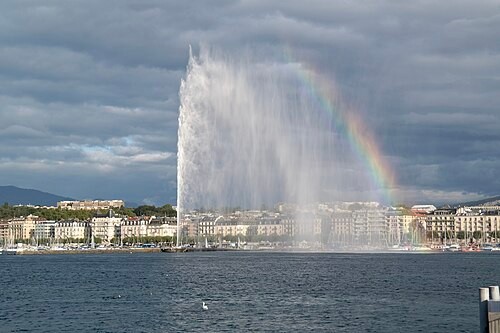
Geneva is Switzerland's second-largest city and its most international: home to the UN European HQ, WHO, WTO, ICRC, CERN, and 25+ other international organisations alongside major private banks and trading houses. The local market is among Europe's tightest -- Geneva's geographical constraints (Lake Geneva, the French border, the Alps) leave almost no room for expansion, sustaining permanent supply pressure. Residential prices run CHF 13,000-22,000 per square metre in central districts (Eaux-Vives, Champel, Old Town, Plainpalais), with gross yields of 2.5-3.5% -- among the lowest in Switzerland. The very high concentration of international civil servants, diplomats, traders, and private bankers underpins consistent rental demand at premium price points. Lex Koller applies as it does in Zurich: non-resident foreigners face restrictions. Best suited to international families relocating with Geneva-based work, or to high-net-worth buyers using authorized commercial structures. Yields are thin but rental stability is exceptional.
Lausanne City Guide
Switzerland
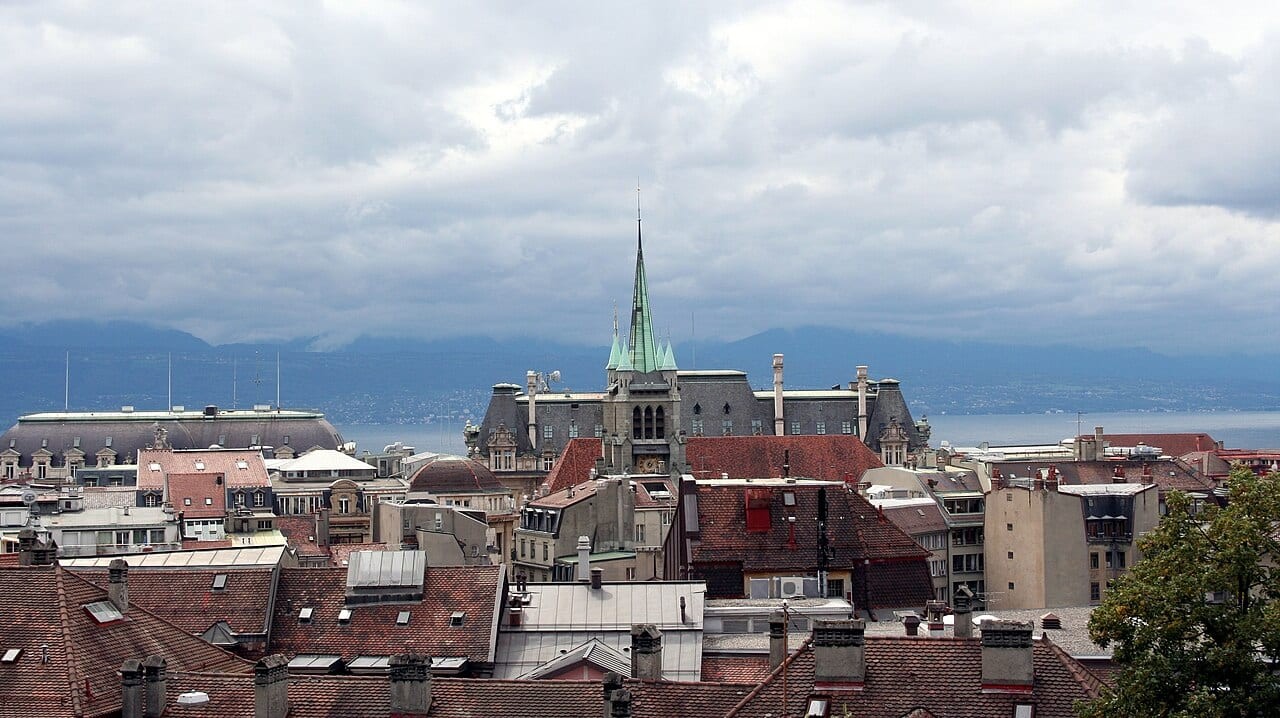
Rising steeply from the shores of Lake Geneva in the French-speaking canton of Vaud, Lausanne is the Olympic Capital, global home of the International Olympic Committee, and one of western Switzerland's most consistently demanded residential markets. The city blends an institutional economic base (the IOC and dozens of international sports federations), a world-class research and education cluster around EPFL and the University of Lausanne, and a thriving medtech and biotech corridor along the lakeshore. Prices are firmly in the Swiss top tier: residential stock averages around CHF 11,460–11,567 per square metre, with newer developments and lake-view properties in Ouchy and Vidy reaching CHF 13,000–14,500. Over the past year apartment prices rose about 2.5% (houses +0.7%), and a further 2.5–3.2% appreciation is projected over the next 12 months. As across Switzerland, yields are income-led and modest, gross yields range roughly 2.8–4.2%, with the highest returns in emerging and redevelopment districts rather than prime lakefront. With tight controlled inventory, high tenant quality anchored by students and international institutions, and the safe-haven Swiss franc, Lausanne offers conservative investors a stable, capital-preserving hold rather than a high-yield or speculative play.
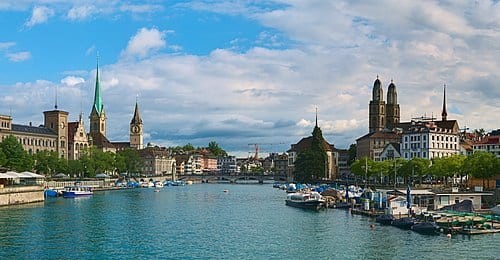
Zurich
Switzerland
Zurich is Switzerland's largest city, its financial capital, and consistently ranked among the world's top-3 cities for quality of life. The Lex Koller law restricts non-resident foreign ownership of residential property -- but EU/EFTA residents with Swiss work permits, holders of B/C permits, and qualifying buyers can access the market. Property prices and rents are among the highest in the world. Central districts (Kreis 1, 6, 7, 8) command CHF 17,000-28,000 per square metre, with peripheral areas at CHF 11,000-15,000. Gross rental yields are tight at 2.2-3.2% -- Switzerland's status as a global safe haven compresses yields heavily. The Swiss National Bank's 2024 rate cuts back to 0.5% have re-energised price growth after a brief 2022-23 pause. For international buyers, Zurich is the ultimate capital-preservation play: AAA sovereign rating, CHF strength, deep institutional liquidity, English-friendly banking, and a tenant pool of Google, UBS, Credit Suisse legacy operations, and major reinsurers. The catch: foreign ownership rules are restrictive, transaction costs are 5-6%, and yields are paltry. Treat as wealth storage, not yield.
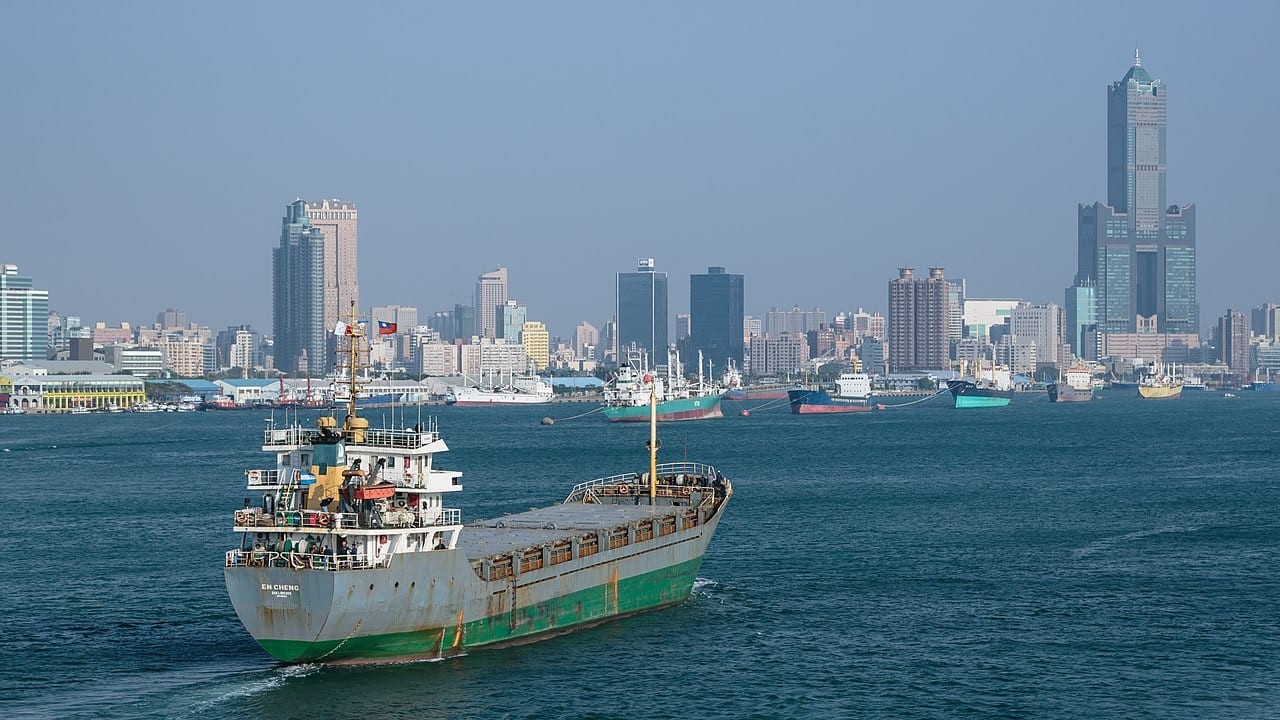

Kaohsiung City Guide
Taiwan
Kaohsiung is Taiwan's largest port city and its industrial powerhouse in the south, increasingly repositioned around advanced manufacturing as TSMC and its supply-chain partners build out fabrication capacity in the northern districts. New-home prices in 2025 ranged from roughly NT$419,600 to NT$540,800 per ping, with existing homes around NT$337,500 to NT$415,200 per ping - materially below Taipei and making Kaohsiung the most affordable of Taiwan's special municipalities. The standout growth story is the TSMC spillover: in Qiaotou District, average prices have surged from about NT$180,000 to NT$320,000 per ping in a single year - a near-70% jump - as semiconductor investment in Nanzih and Qiaotou shifts rental demand from blue-collar workers toward higher-paid tech professionals. Citywide gross yields average 2.43%, modestly above the national figure, ranging from 1.96% to 2.73%. The wider market remains soft - Kaohsiung house prices fell 7.33% year-on-year in Q4 2025, the city's steepest decline since 2009, though quarterly prices ticked up 0.95% - and a long-running population decline since 2018 caps broad-based demand. The investment case is therefore highly location-specific: TSMC-adjacent northern districts offer genuine structural upside, while the legacy core trades on affordability and a maturing waterfront lifestyle around the Asia New Bay Area.
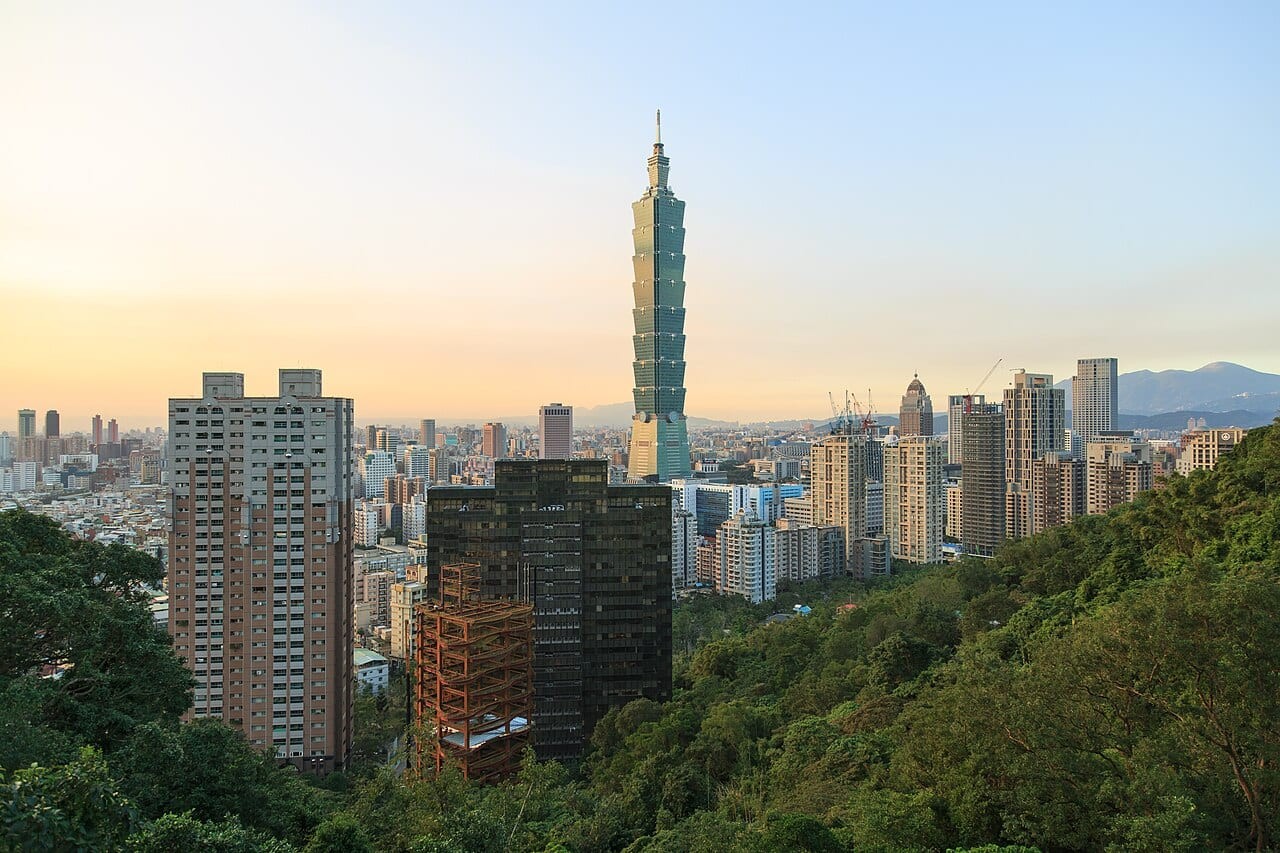
Taipei City Guide
Taiwan
Taipei is Taiwan's political, financial, and technology capital, the seat of government and the headquarters base for the island's world-leading semiconductor and electronics supply chain. The city's most prestigious addresses cluster in Xinyi - home to Taipei 101, the central business district, and luxury towers commanding NT$900,000 to NT$1.1 million per ping - and in adjacent Daan and Songshan, Taipei's most densely populated and sought-after residential districts. For investors, the defining feature of the Taipei market is its combination of very high prices and exceptionally low yields: gross rental yields ranged from just 1.66% to 2.13% across the city in Q4 2025, averaging around 1.93%, placing Taipei alongside Monaco among the lowest-yielding markets globally. The market has also cooled. House prices in Taipei City slipped 0.62% year-on-year in Q4 2025 - the capital's first annual decline since early 2020 - while island-wide transactions plunged 25.5% in 2025 to a nine-year low, driven by the central bank's selective credit controls and tighter mortgage rules. Taipei remains a wealth-preservation and prestige market for buyers prioritising a stable rule-of-law jurisdiction, deep liquidity, and proximity to the global tech economy, rather than rental income, with more affordable proximity plays available across the river in New Taipei City.
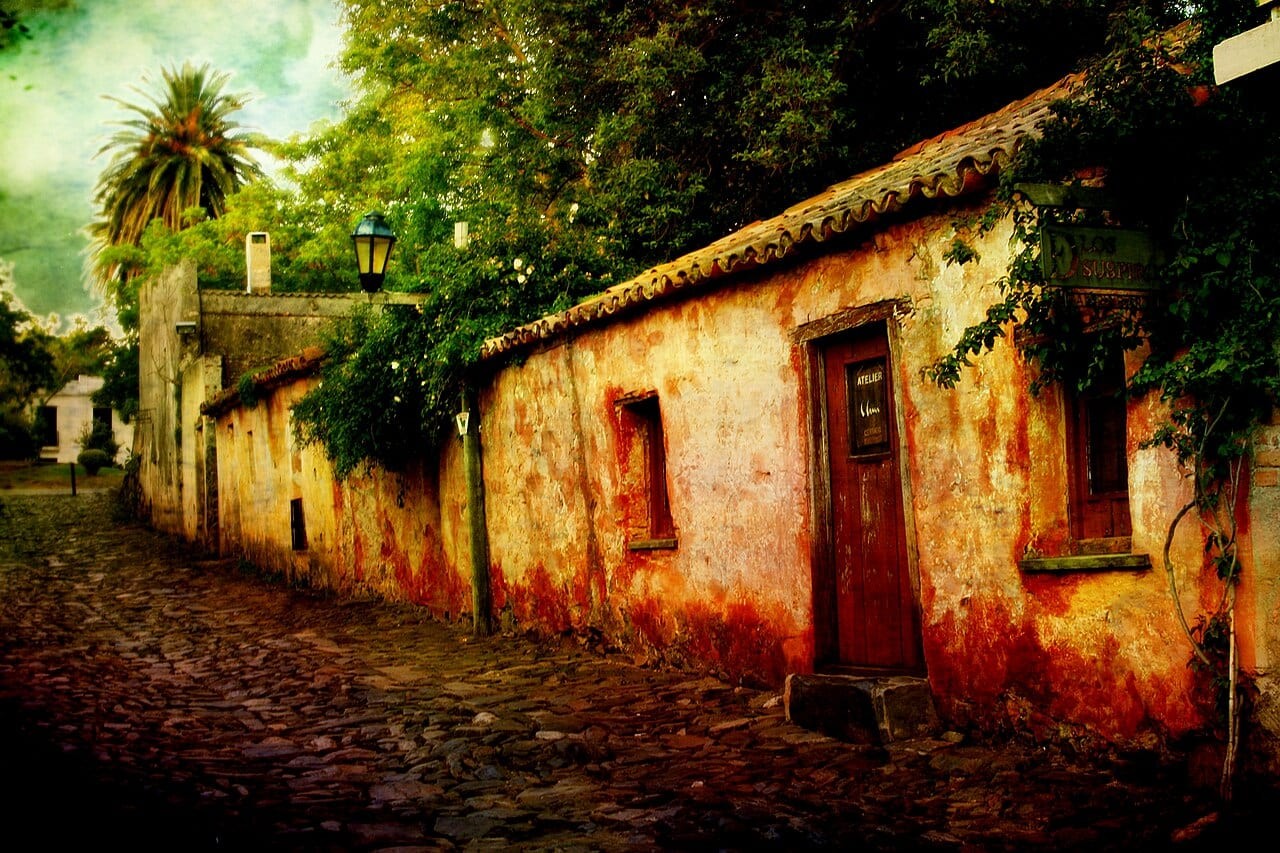

Colonia del Sacramento
Uruguay
Colonia del Sacramento is a UNESCO World Heritage city on the Rio de la Plata, an hour by ferry from Buenos Aires, blending Portuguese-Spanish colonial heritage with a fast-modernizing investment story. In 2026 median values sit near US$3,500/m2 in the cobblestoned Barrio Historico, while greater-Colonia apartments range US$1,800-3,000/m2 - well below Punta del Este's US$4,000+/m2 yet appreciating in double digits. The historic core's heritage zoning permanently caps new supply, pushing scarcity-driven gains, while the institutional-backed +Colonia smart-city expansion is drawing capital for modern build-to-rent stock. A one-bedroom in the center rents for roughly US$800/month and gross yields run 5-7%. Uruguay places no restrictions on foreign buyers: foreigners hold the same freehold rights as citizens, titles are registered publicly, and you can purchase as a non-resident on a tourist stay with no quotas or approvals. Uruguay's residency-by-investment tax holiday remains available, though from January 2026 the real-estate threshold for the offshore-income tax holiday rose to roughly US$2,000,000 (or US$100,000/year to the National Innovation Fund). Colonia suits investors who want heritage charm, Buenos Aires weekend tourism demand, and steady appreciation rather than ultra-prime coastal speculation.
José Ignacio
Uruguay
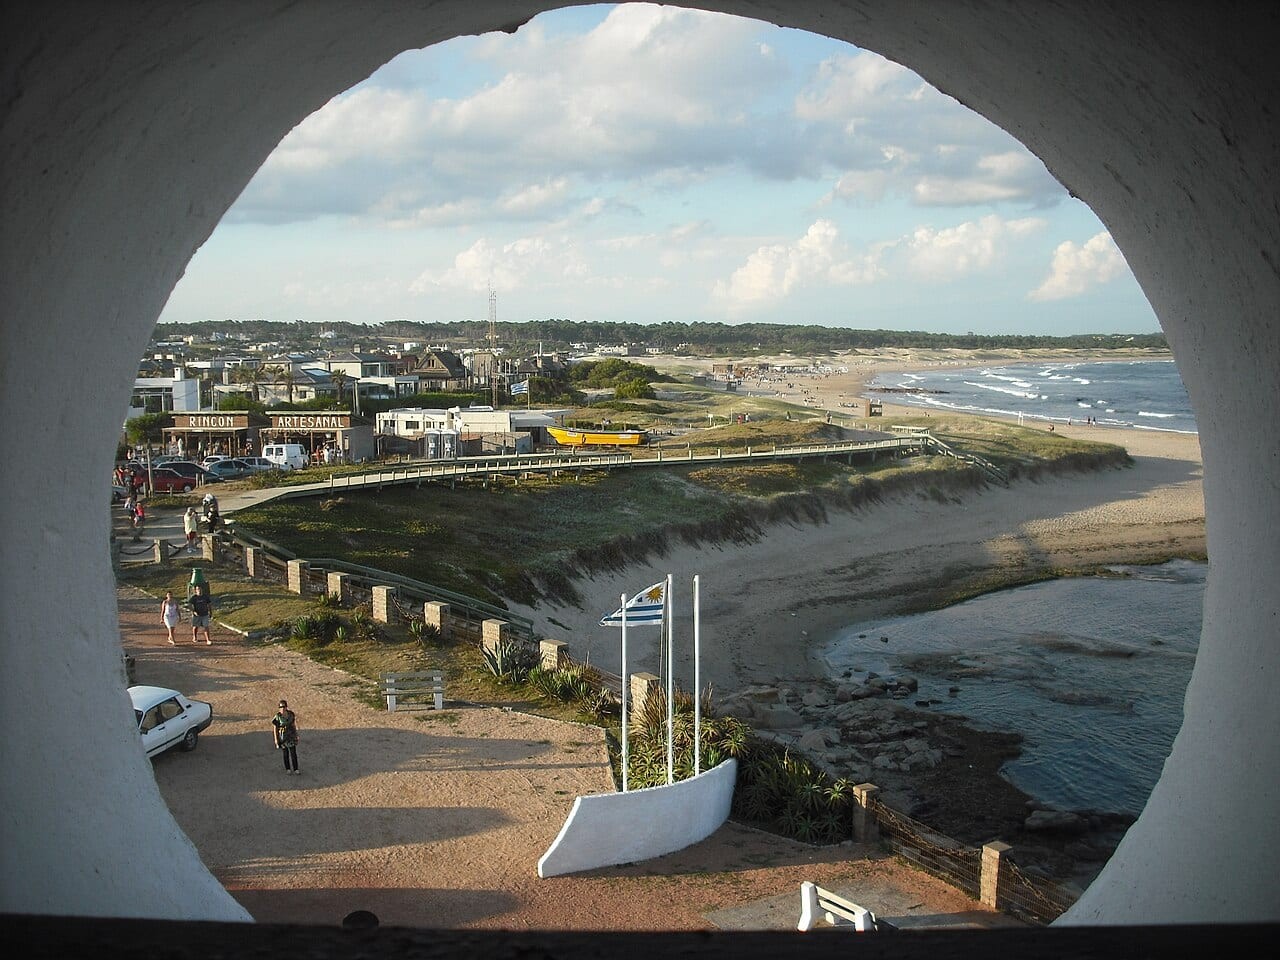
José Ignacio is Uruguay's ultra-prime beach village - a former fishing hamlet on the Maldonado coast turned billionaire playground, anchored by its white lighthouse, Playa Brava and Playa Mansa, and world-famous beach clubs. In 2026 it is the country's most expensive and most resilient submarket: prime beachfront villas start around US$2 million and climb into the multi-millions, with land and quality homes trading well above US$4,000/m2 and the rarest beachfront far higher. Scarcity and international luxury demand have driven roughly 8-12% annual appreciation. The rental story is exceptional: net yields of 6%+ on top projects, summer monthly income of US$3,500-5,000 for well-located apartments, and prestige villas earning over US$100,000 across a single high season. Uruguay imposes no restrictions on foreign buyers - full freehold title, no quotas, purchasable as a non-resident. The residency-by-investment tax holiday remains, though from January 2026 the qualifying real-estate threshold rose to about US$2,000,000, a bar most José Ignacio prime purchases clear comfortably. This is a market for high-net-worth lifestyle-and-appreciation buyers seeking South America's most exclusive coastal address.
La Paloma
Uruguay
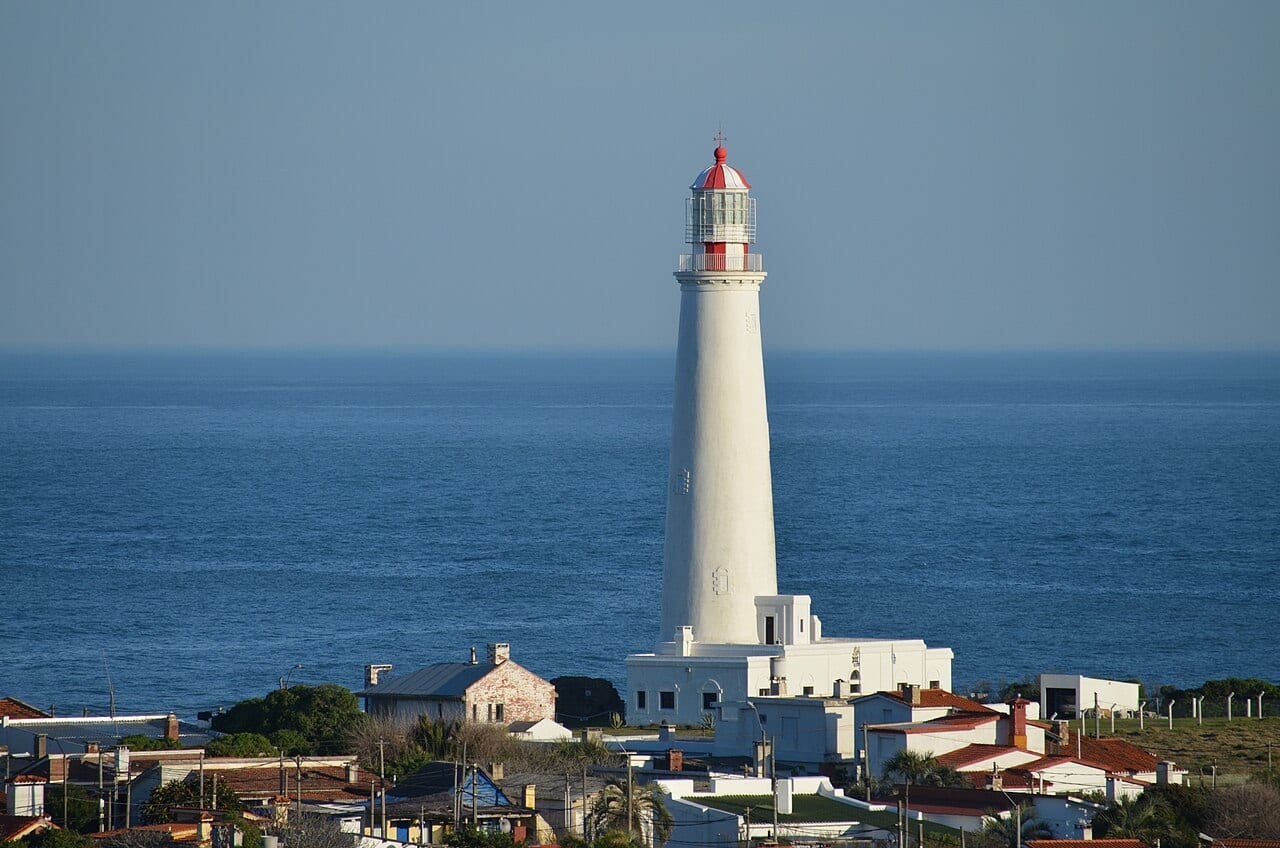
La Paloma is a relaxed Atlantic beach town in Uruguay's wild Rocha department, built around the Cabo Santa Maria lighthouse and ringed by beaches from the tranquil La Balconada to the surf-and-fishing energy of Los Botes. Home to about 3,500 year-round residents, it swells to 30,000 in summer. In 2026 it is a value-and-lifestyle market on the rise: beach houses generally sell for US$100,000-250,000, buildable lots run US$30,000-150,000 depending on sea proximity and services, and quality stock trades around US$1,800-2,600/m2 - far below Punta del Este. Gross rental yields run 4-6%, peaking sharply in the December-February high season. Rocha is riding an eco-tourism and slow-travel boom, with the Michelin Guide's 2025-2026 arrival in Uruguay lifting hospitality standards along the eastern coast and supporting appreciation. Uruguay imposes no restrictions on foreign buyers - full freehold rights including beachfront, purchasable as a non-resident with public title. The residency-by-investment tax holiday remains (real-estate threshold raised to ~US$2,000,000 from January 2026). La Paloma suits investors seeking affordable Atlantic beachfront, eco-tourism upside and an unspoiled coastal lifestyle.
Montevideo City Guide
Uruguay
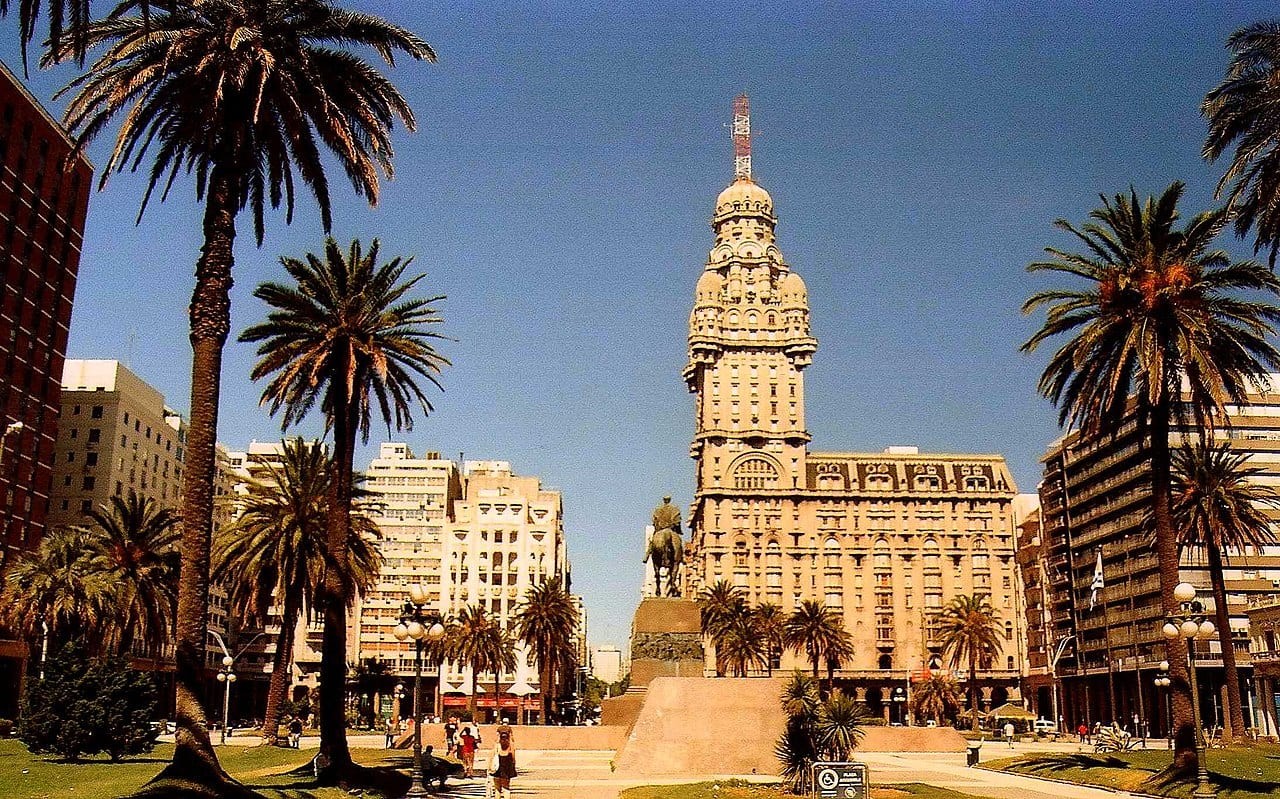
Montevideo is the capital of one of Latin America's most stable democracies, and its USD-priced property market functions as a regional safe-haven, Uruguay enjoys investment-grade credit, strong institutions and a tradition of respecting property rights, drawing Argentine and Brazilian capital fleeing currency and political risk. The city is defined by its 22 km Rambla, a continuous Río de la Plata promenade that anchors the most desirable residential corridor (Pocitos–Punta Carretas–Carrasco). Foreigners buy on fully equal terms with locals, and prices and many leases are denominated in US dollars, insulating buyers from peso volatility. Yields are moderate; the trade-off is liquidity, transparency and capital preservation rather than aggressive cash flow.
Piriápolis
Uruguay
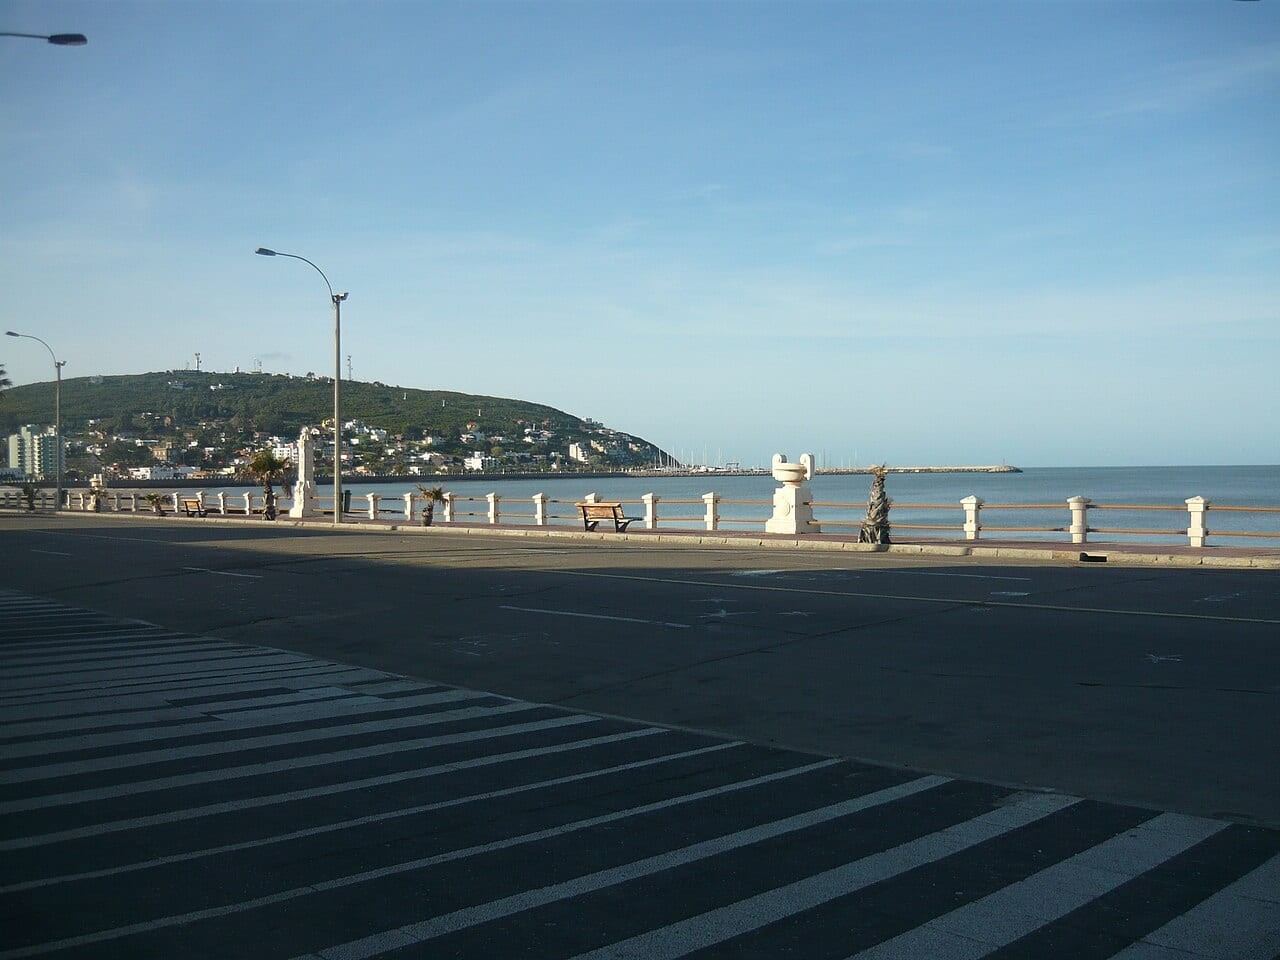
Piriápolis is a charming early-20th-century seaside resort on the Costa de Oro between Montevideo and Punta del Este, founded by visionary Francisco Piria around the landmark Hotel Argentino, the Rambla de los Argentinos and the hills of Cerro San Antonio and Cerro Pan de Azucar. In 2026 it is one of Uruguay's best value-beach plays: beachfront property runs US$1,800-2,500/m2 versus Punta del Este's US$4,000+/m2, and a two-bedroom waterfront unit downtown costs roughly US$190,000-220,000. Waterfront values have climbed steadily since 2008 (from ~US$75,000 to US$190,000+) and continue appreciating in the high single digits. Demand is strongly seasonal and family-resort driven, so annual occupancy averages 20-30% but summer rates are strong, producing gross yields around 5-7%. Uruguay places no restrictions on foreign buyers - identical freehold rights to citizens, beachfront included, purchasable as a non-resident with public title registration. The residency-by-investment tax holiday remains available (real-estate threshold raised to ~US$2,000,000 from January 2026). Piriápolis suits investors seeking affordable beachfront, a nostalgic family-resort atmosphere and steady appreciation close to the capital.