City guides
City guides (402)
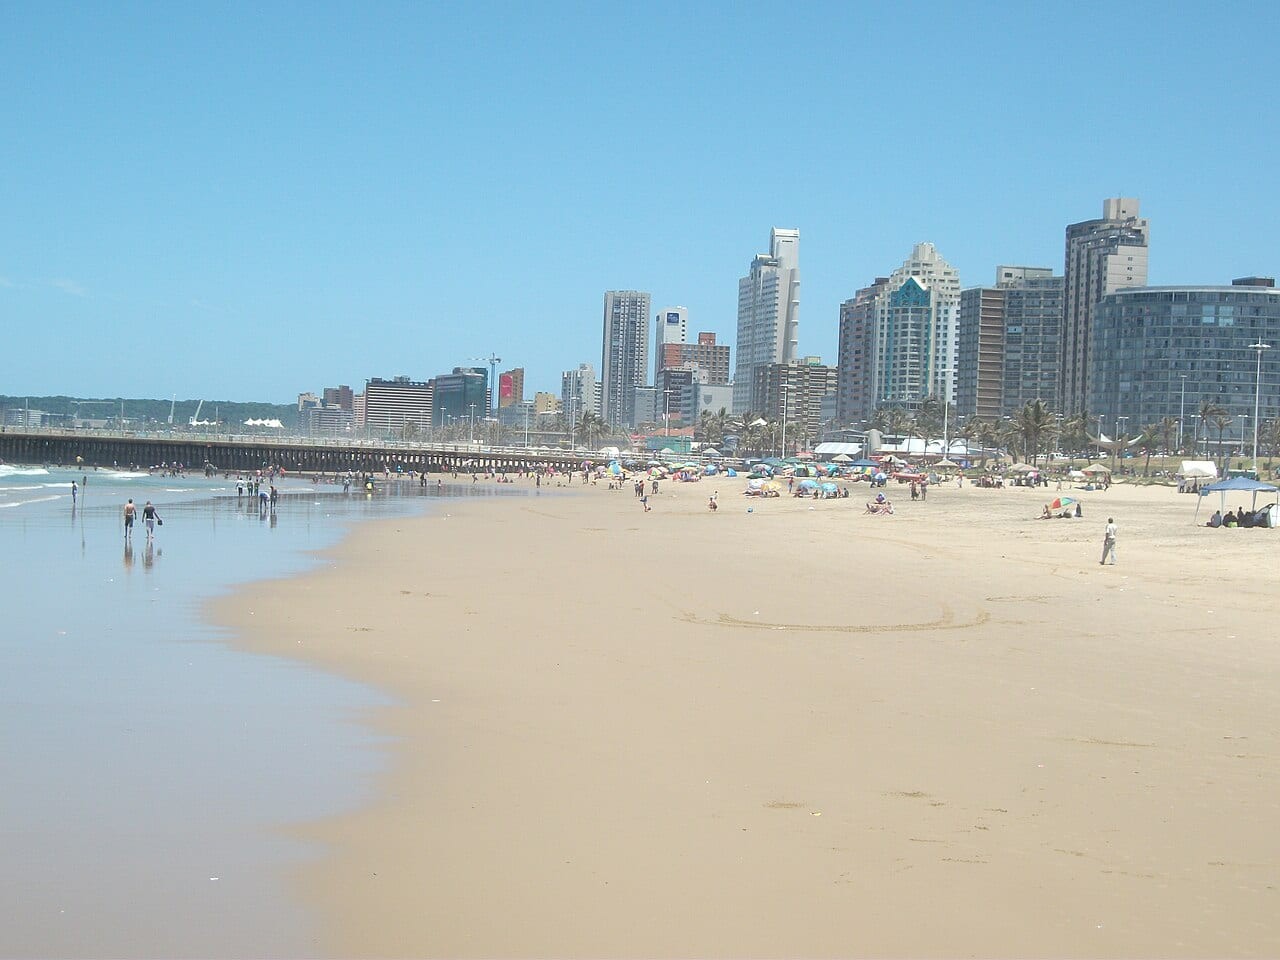

Durban City Guide
South Africa
Durban is South Africa's third-largest city and the warm-water gateway of the Indian Ocean coast, wrapped around the busiest port in Africa. Its signature is the Golden Mile, a long beachfront promenade of surf beaches and the uShaka Marine World complex, set against a humid, year-round-swimming climate that makes KwaZulu-Natal the country's domestic-holiday capital. At roughly half the per-square-metre cost of Cape Town's Atlantic Seaboard, Durban reads as a value-and-yield market rather than a capital-gains market. The investment story of the last decade has been a clear migration of money north of the old centre to the uMhlanga / La Lucia 'New Durban' growth node, anchored by the giant Gateway mall, the uMhlanga Ridge business district and the emerging Sibaya Coastal Precinct, which now functions as the de-facto premium CBD. Domestic 'semigration' from Gauteng to the KZN coast continues to feed demand here and up the N2 toward Ballito. Honesty matters: the boom is geographically uneven. The historic inner city and parts of the beachfront fringe have declined through service strain and the aftermath of the 2021 unrest and 2022 floods, while a multi-billion-rand regeneration (Point Waterfront, Rivertown) is still a work in progress. The reliable returns sit in the northern suburbs and the Berea ridge (Morningside, Musgrave, Glenwood), where strong rental demand and established schools offset slow headline price growth. Foreigners buy freely (non-residents ~50% local finance, exchange control); there is NO property golden visa. Investors come to Durban for income and lifestyle, not the appreciation curve.
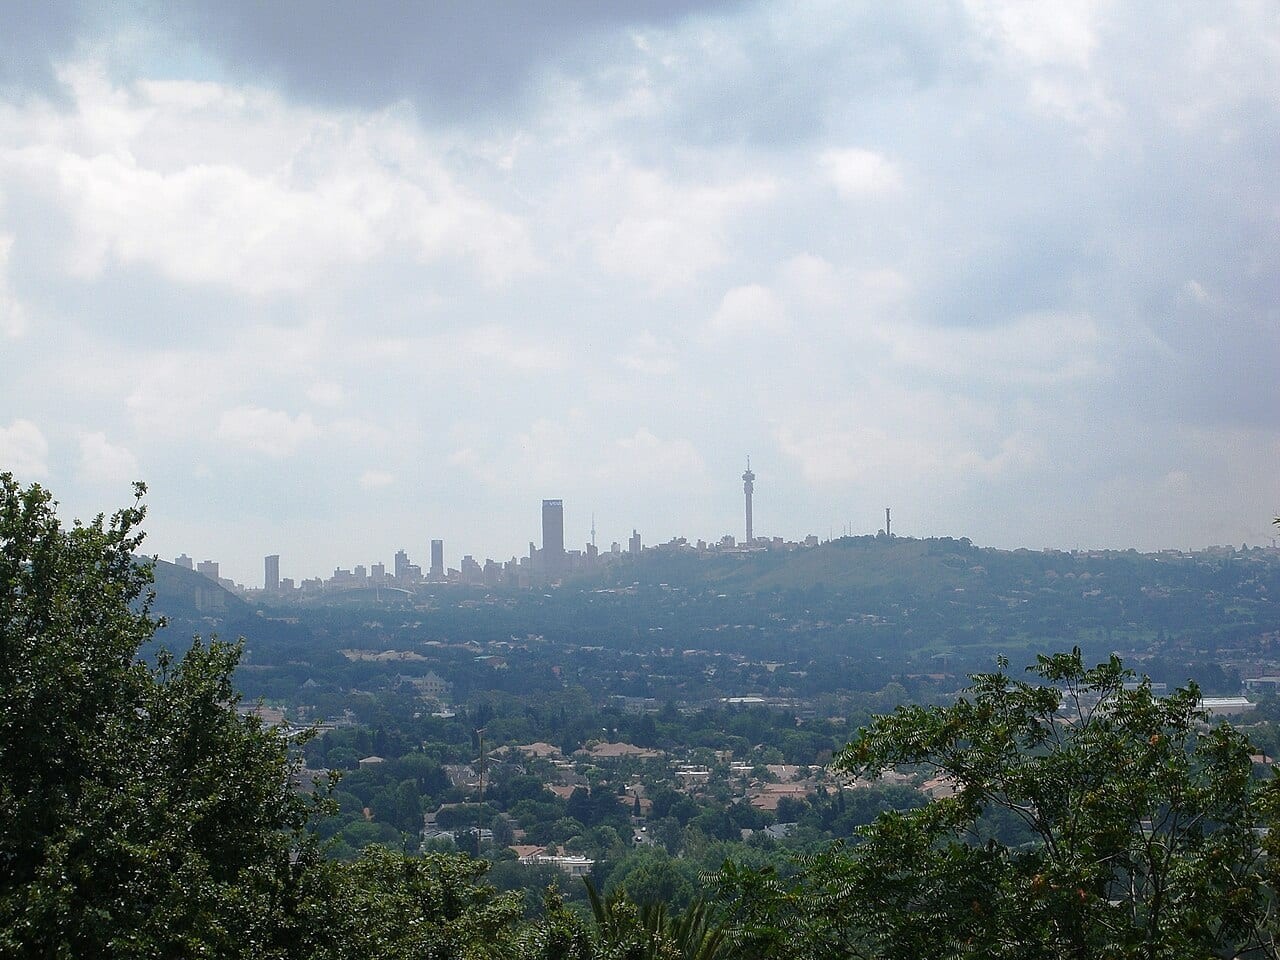
Johannesburg City Guide
South Africa
Johannesburg is the economic engine of South Africa and the wider sub-Saharan region, the country's largest city (metro ~6.45m) and seat of the Johannesburg Stock Exchange, Africa's largest bourse. Within it, Sandton functions as the de-facto financial capital, routinely branded the 'richest square mile in Africa'. Everything is priced in the rand (ZAR), a volatile emerging-market currency, the single most important variable for a euro investor, since local price growth can be erased or amplified by ZAR moves. Joburg's defining feature is its gated-estate and security-complex culture. Demand concentrates in the affluent northern suburbs (Sandton, Bryanston, Fourways, Rosebank, Houghton) where 24-hour access control, electric fencing and private patrols are standard and priced into the asset, a response to a genuinely high city-wide crime environment, so security is a real ongoing cost, not a marketing flourish. Two honest headwinds: 'semigration' out of Gauteng to the Western Cape has pushed Cape Town's price growth (~9–10% YoY) far ahead of Gauteng's (~3% YoY), so Joburg has lagged Cape Town on capital growth for years; and load-shedding, severe in 2022–24, had largely abated by early 2026 (300+ blackout-free days). The investment thesis is the mirror image of Cape Town's: lower capital growth, but materially higher rental yields and far cheaper entry prices. There is NO property golden visa, buying confers no residency.
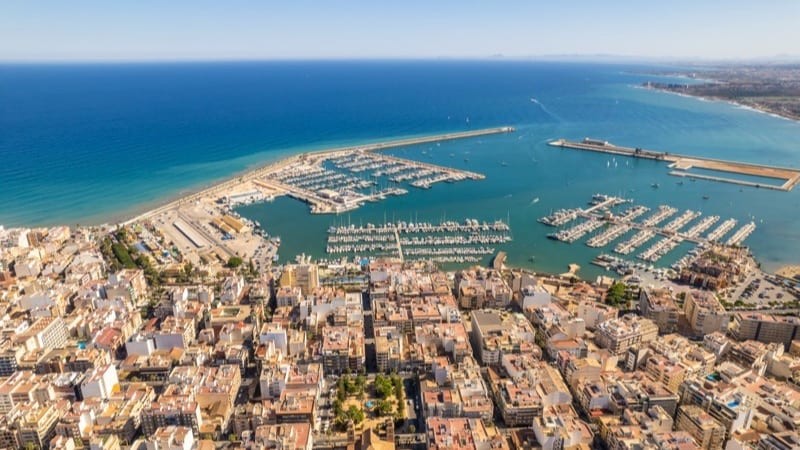

Alicante City Guide
Spain
Alicante, the gateway city of the Costa Blanca, is the most international property market in Spain. Foreign buyers account for close to half of all transactions in the province, drawn by 300-plus days of sunshine a year, a busy international airport and direct beach access. Prices have climbed sharply: the city average reached roughly 2,435-2,508 euros per square metre by early 2026, a year-on-year rise of around 16%, yet values remain affordable next to Spain's capitals and prime coastal hotspots. Rental yields are competitive at about 5.5% gross for long lets, while short-term holiday rentals in premium seafront areas can return 6-10% per annum given the year-round tourism season. Demand is broad-based (UK, German, Dutch, Scandinavian and Belgian buyers dominate the international segment), and emerging neighbourhoods such as San Blas-PAU and Villafranqueza posted growth above 22% in 2025. Nearby Costa Blanca markets like Torrevieja, La Mata and Punta Prima offer higher-yield, lower-priced alternatives. As a Eurozone destination Alicante provides currency and legal stability, but investors must weigh genuine risks: rapid price appreciation raises overheating concerns, Spain ended its Golden Visa in 2025 (removing the residency-by-purchase route), and several municipalities are tightening short-term-rental licensing.
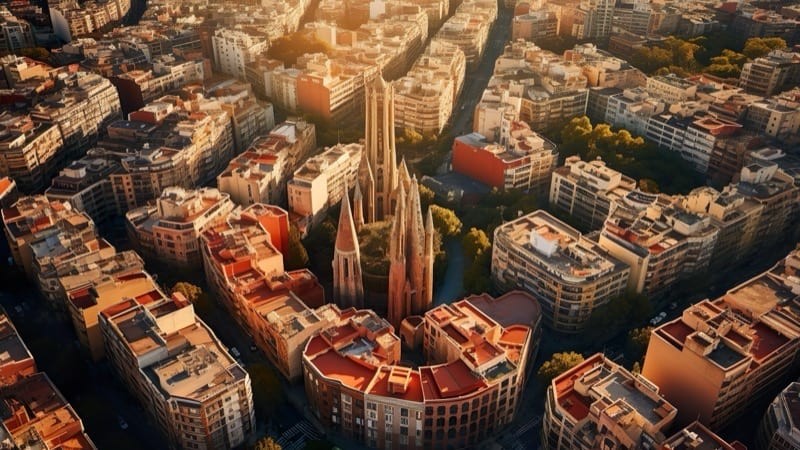
Barcelona City Guide
Spain
Barcelona, the capital of Catalonia, blends Mediterranean lifestyle, world-class beaches and the unmistakable modernisme of Antoni Gaudi (Sagrada Familia, Park Guell, Casa Batllo) with a fast-growing tech and startup economy anchored in the 22@ innovation district. It is a top global tourism destination and a magnet for international residents - foreign nationals make up around 26% of the city's population. Foreigners can buy property freely with no nationality restrictions, but the investment landscape has shifted sharply. Spain abolished its Golden Visa (residency-by-property-investment): the program closed to new applicants on 3 April 2025. Barcelona is also phasing out short-term tourist-rental apartments - the city will not renew any of its ~10,000 HUT (tourist-use housing) licences when they expire in November 2028, effectively ending legal tourist flats (a phase-out upheld by Spain's Constitutional Court). Separately, in January 2025 the central government proposed a tax of up to 100% on second-hand homes bought by non-EU non-residents; this remains a proposal, not law, and faces significant legal and political obstacles.
Madrid City Guide
Spain
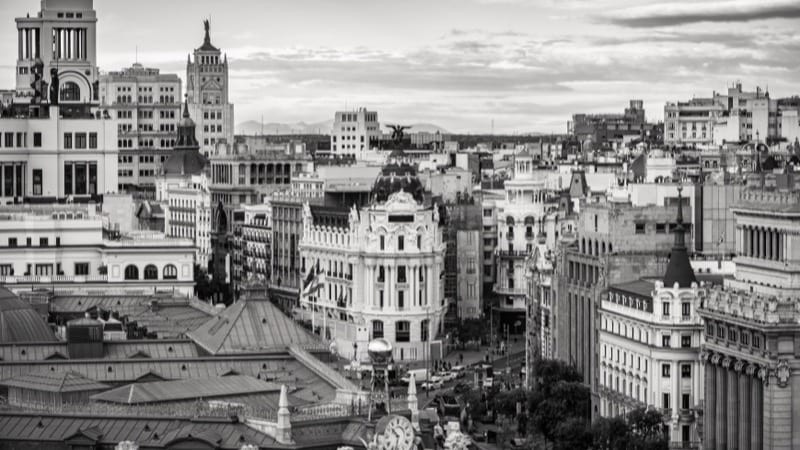
Spain's grand capital pairs imperial-era architecture with one of Europe's most dynamic 21st-century economies. From the marble-clad mansions and luxury boulevards of Salamanca, through the classical residential blocks of Chamberí, to the gleaming towers of the Cuatro Torres business district in Chamartín, Madrid offers investors an unusual combination of capital-city prestige, deep liquidity, and yield potential that compares favorably with Paris, London, and Amsterdam. As the EU's fourth-largest regional economy and home to 72% of Spain's banking activity, Madrid draws constant inflows of corporate talent, multinational headquarters, and international capital. The city's residential market entered 2026 on the back of double-digit price growth in 2024 and 2025, supported by a structural supply shortfall and accelerating in-migration. While the Golden Visa programme was terminated in April 2025, Spain's mainstream investor pathways — combined with Madrid's lifestyle, transport infrastructure, and cultural depth — continue to make the capital the most strategically important city in the Iberian peninsula for international buyers.
Marbella City Guide
Spain
Marbella is the luxury capital of the Costa del Sol (Málaga province, Andalusia), where the Sierra Blanca mountains, crowned by La Concha, meet 27 km of Mediterranean coast. Its glamour is anchored by the Golden Mile, a prestige beachfront-to-hillside corridor running west toward Puerto Banús, the superyacht marina synonymous with designer boutiques, beach clubs and nightlife. The municipality blends a whitewashed Old Town around Plaza de los Naranjos with Nueva Andalucía's 'Golf Valley' and gated villa enclaves like Sierra Blanca and Cascada de Camoján, drawing British, Scandinavian, Dutch, German, Middle Eastern and Russian HNW buyers (~36% of residents are foreign nationals). Foreigners can buy property freely with no nationality restriction, but Spain ABOLISHED its Golden Visa (residency-by-property-investment), which closed to new applicants on 3 April 2025, a purchase no longer grants residency. Short-term tourist-rental (licencia turística) rules are tightening across Spain, and a January 2025 government proposal of an up-to-100% surcharge on second-hand homes bought by non-EU non-residents remains a contested proposal, not law.
Málaga City Guide
Spain
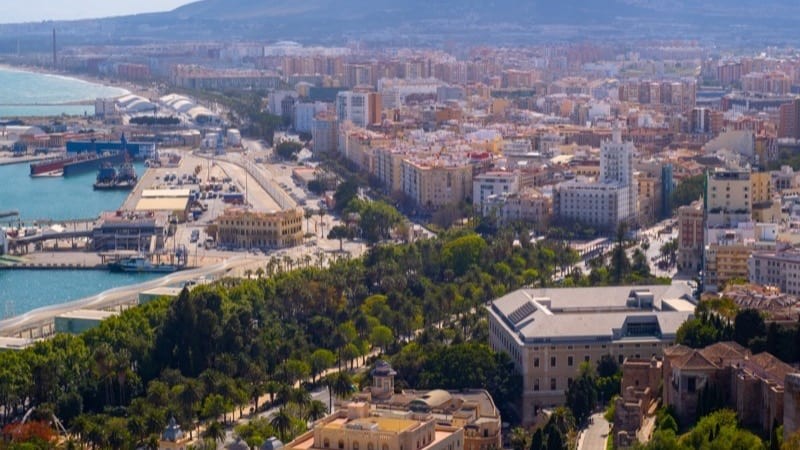
Málaga is the sun-drenched capital of the Costa del Sol and Andalusia's second city (~592,000 residents; ~1.3M metro), a Mediterranean port that has transformed from a beach gateway into one of southern Europe's most dynamic urban centres. Birthplace of Picasso, it is a museum powerhouse, the Museo Picasso, Centre Pompidou (El Cubo on Muelle Uno), Carmen Thyssen and CAC, alongside the Moorish Alcazaba, the Roman Theatre, the Gibralfaro castle and the Cathedral ('La Manquita'). A modernised cruise port, the Muelle Uno promenade and city beaches (La Malagueta, Pedregalejo) sit beside the fast-growing 'Málaga Valley' tech economy (Google, Vodafone, 600+ firms at Málaga TechPark). Foreigners can buy property freely with no nationality restriction, but Spain ABOLISHED its Golden Visa (residency-by-property-investment), which closed to new applicants on 3 April 2025, a purchase no longer grants residency. Short-term tourist-rental (licencia turística) rules are tightening across Spain, and a January 2025 government proposal of an up-to-100% surcharge on second-hand homes bought by non-EU non-residents remains a contested proposal, not law.
Seville City Guide
Spain
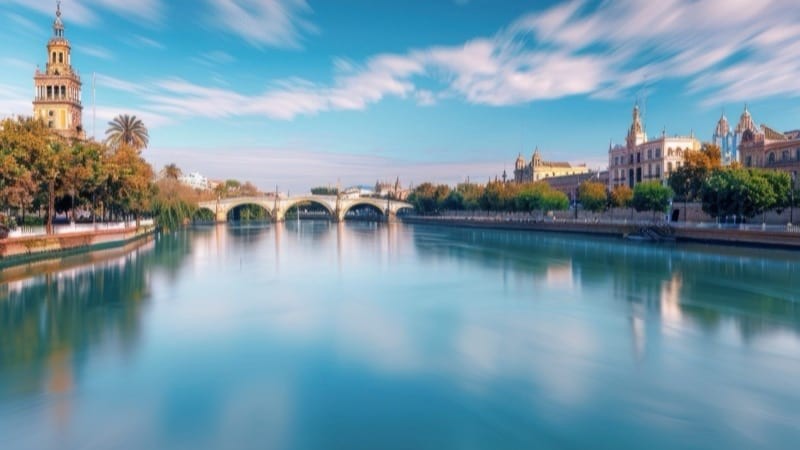
Seville, the sun-drenched capital of Andalusia, offers international buyers a rare blend of world-class heritage, a thriving tourism economy and property prices that remain well below Madrid and Barcelona. The city of roughly 688,000 (with more than 1.5 million in the wider metropolitan area) is built around landmarks such as the cathedral and Giralda, the Real Alcazar and the Plaza de Espana, all of which underpin one of Europe's most resilient tourism flows. Average residential prices sit near 2,000-2,250 euros per square metre citywide, with prime central districts (Nervion, Triana and Los Remedios) pushing toward 2,900 euros/m2 for high-spec units. Rental yields are attractive at roughly 5-6% gross, and occupancy in prime areas exceeds 95%, supported by students, hospital staff and a growing remote-worker population. Forecasts point to steady 3-5% price growth over the next year, with most new construction concentrated in Sevilla Este and Bellavista. As a Eurozone city Seville offers currency and legal stability, though Spain abolished its Golden Visa in 2025, so non-EU buyers no longer gain residency through purchase. Other headwinds include tightening short-term-rental regulation in tourist-heavy zones and affordability pressure on local buyers, both of which make district and licence due diligence essential.
Valencia City Guide
Spain
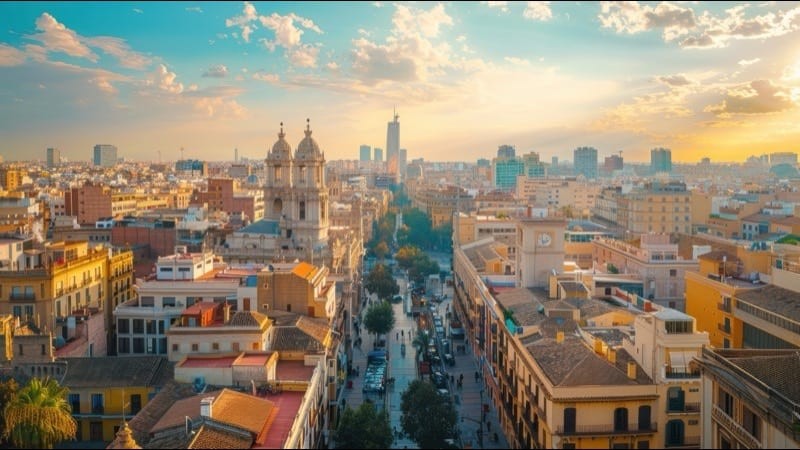
Valencia, Spain's third-largest city (~841,000 residents) and the birthplace of paella, sits on the Mediterranean where the diverted Turia River became the 9 km Turia Gardens, Europe's largest urban park, culminating in Santiago Calatrava's futuristic City of Arts and Sciences. It pairs a medieval old town (Ciutat Vella) anchored by the Cathedral, El Miguelete, the UNESCO-listed La Lonja and the Mercado Central with a working port, the Malvarrosa/Las Arenas beaches and a fast-growing tech, startup and international-expat scene that made it one of Spain's hottest markets (citywide prices up ~15–22% YoY through 2025). Foreigners can buy property freely with no nationality restriction, but Spain ABOLISHED its Golden Visa (residency-by-property-investment), which closed to new applicants on 3 April 2025, a purchase no longer grants residency. Short-term tourist-rental (licencia turística) rules are tightening across Spain, and a January 2025 government proposal of an up-to-100% surcharge on second-hand homes bought by non-EU non-residents remains a contested proposal, not law.

Colombo
Sri Lanka
Colombo is Sri Lanka's commercial capital, financial hub, and the primary gateway for international property investment in the country. With a metropolitan population of approximately 5.6 million, it is the island's largest urban centre and economic engine. The city is undergoing a dramatic transformation, anchored by the USD 14 billion Port City Colombo development — a reclaimed island and special economic zone designed to position Colombo as a regional financial centre rivalling Singapore and Dubai. The property market is in a strong recovery phase following Sri Lanka's 2022 economic crisis. Residential land prices in Colombo District rose 14.4% in the first half of 2025, with suburban areas seeing increases of up to 20%. Luxury CBD condominiums have recorded 48% price appreciation over five years (2018-2023) for pre-2015 builds, while foreign interest in Sri Lankan property has surged 33% year-on-year. Over 8,000 new residential apartment units are expected by 2026, bringing the total recognised units to more than 42,000. Colombo's appeal lies in its combination of low entry prices relative to regional peers (Bangkok, Kuala Lumpur, Singapore), 100% foreign condominium ownership with no unit quotas, and the new Golden Paradise Residence Visa programme offering 5-10 year residency from USD 75,000. The city's tourism sector is thriving — Sri Lanka recorded a historic 2.36 million visitor arrivals in 2025, a 15.1% increase — further supporting rental demand across the city.
Ella
Sri Lanka
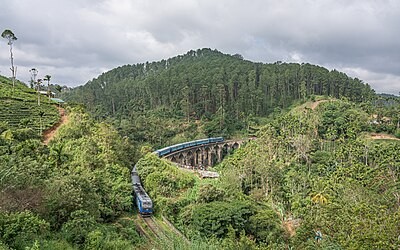
Ella is a small hill-country town in Sri Lanka's Uva Province that has become one of South Asia's most talked-about backpacker and boutique tourism destinations. The iconic Nine Arches Bridge, misty tea plantations, dramatic Ella Gap viewpoint, and the scenic Colombo-Badulla railway have made Ella a social media phenomenon, driving explosive growth in visitor arrivals and accommodation development. The hospitality investment landscape is booming, with Uga Resorts opening Uga Ghiri — a luxury 15-villa resort on the former Sutherland Estate — in mid-2026. This signals the market's evolution from backpacker guesthouses to high-end boutique and wellness retreats. Visitor spending has shifted dramatically from Colombo to inland destinations like Ella, with boutique hotels, eco-lodges, and community-based tea tourism experiences attracting increasingly affluent travelers. However, Ella faces boom-town challenges: unchecked hotel construction, road congestion, and strain on water resources threaten the tranquility that drew visitors in the first place. For 2026, the destination is being repositioned through 'soft adventure' and 'low-impact exploration' — homestays, guided hikes, and community tea tours. Investors who focus on sustainable, experience-driven hospitality rather than volume accommodation stand to benefit most from Ella's evolving market.
Galle
Sri Lanka
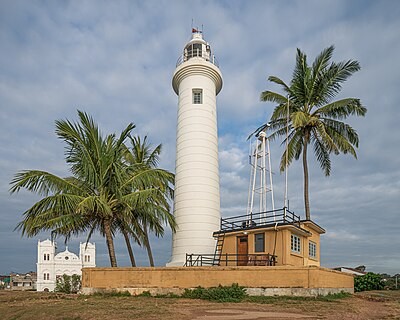
Galle is a UNESCO World Heritage city on Sri Lanka's southwestern coast, renowned for its 17th-century Dutch colonial fort, vibrant art scene, and rapidly growing boutique tourism industry. With a city population of approximately 93,000 and a district population exceeding 1.1 million, Galle is the cultural and economic capital of the Southern Province and Sri Lanka's most established heritage tourism destination. The real estate market in Galle combines historical charm with strong investment fundamentals. Luxury beachfront villas range from USD 300,000 to USD 1 million or more, with well-managed holiday rental properties achieving 8-10% annual gross rental yields. Property values have been rising steadily, with an estimated 10% annual capital appreciation in prime locations. The Southern tourism corridor from Galle to Hambantota has emerged as one of the most promising areas for leisure-based real estate development, supported by expressway connectivity, rising tourist arrivals, and increasing international hotel brand interest. Galle Fort itself is a living UNESCO World Heritage Site — a walled enclave of cobbled streets, independent boutiques, galleries, cafes, and heritage hotels occupying restored Dutch colonial buildings. The fort attracts a sophisticated international clientele and has become a magnet for boutique hotel investors, creative entrepreneurs, and lifestyle expatriates seeking a blend of history, culture, and tropical coastal living.
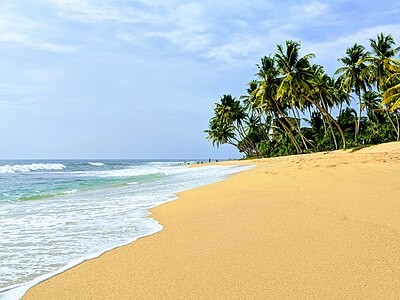
Hikkaduwa
Sri Lanka
Hikkaduwa is Sri Lanka's original surf-and-sand destination on the southern coast, renowned globally for its coral reef sanctuary, consistent surf breaks, and a vibrant beach-party atmosphere that has attracted international travelers since the 1970s. Unlike newer coastal resorts, Hikkaduwa retains an authentic charm that keeps visitors returning — and keeps property prices climbing. The property market is experiencing renewed momentum as Sri Lanka's tourism recovery drives land values upward. Hikkaduwa is popular for beachfront villas and eco-resorts, with short-term holiday rentals yielding 5-8% annually. Unlike other coastal towns that have reached peak popularity, Hikkaduwa's authentic character means buyers entering today can secure prime plots before demand drives prices significantly higher. The surf culture, coral reef snorkeling, and turtle hatcheries create a diversified tourism base less vulnerable to seasonal fluctuation. Hikkaduwa benefits from excellent connectivity via the Southern Expressway and Galle Road, placing it within two hours of Colombo and minutes from the UNESCO heritage city of Galle. The combination of established tourism infrastructure, authentic local culture, and rising land values makes Hikkaduwa one of the south coast's most balanced investment destinations — offering both lifestyle appeal and capital growth potential.
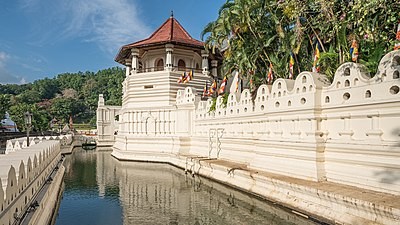
Kandy
Sri Lanka
Kandy is Sri Lanka's hill capital and the island's cultural heart, home to the sacred Temple of the Tooth Relic — one of Buddhism's most venerated sites — and surrounded by lush tea plantations, misty mountains, and the scenic Kandy Lake. The city served as the last capital of the Sinhalese kings before British colonization and remains a UNESCO World Heritage Site of immense cultural significance. The property market is gaining momentum as a compelling secondary city investment. With increasing prices in Colombo, Kandy is emerging as an affordable alternative with genuine appreciation potential. The Central Expressway, scheduled for completion by July 2026, will cut travel time from Colombo to just 90 minutes — a transformation that historically drives property appreciation of 20-30% in newly accessible regions. Land prices remain attractive, drawing both retirees and forward-looking investors. Kandy's appeal extends beyond cultural tourism. The city is a major education hub with the University of Peradeniya and numerous schools, driving consistent rental demand. The cool hill-country climate, botanical gardens, and tea estate experiences attract high-value tourists, while the emerging wellness and boutique hotel sector is creating new hospitality investment opportunities. For investors seeking Sri Lanka exposure beyond Colombo's saturated market, Kandy offers heritage-driven appreciation with infrastructure-catalyzed upside.
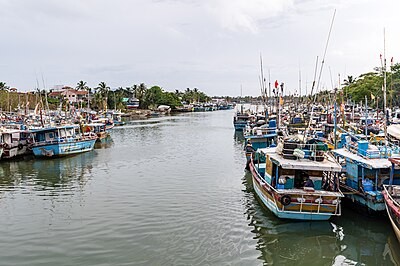
Negombo
Sri Lanka
Negombo is Sri Lanka's coastal gateway city, strategically located just 10 minutes from Bandaranaike International Airport and 35 kilometers north of Colombo. This historic fishing town has evolved into a growing tourism hub where affordable beachfront living, a vibrant fish market, and Dutch-colonial canal system attract both international tourists and property investors seeking airport proximity. The property market combines growth and affordability, with Negombo emerging as a favoured destination for overseas buyers priced out of Colombo. Coastal serviced apartment complexes targeting the tourism and vacation rental market offer both personal use and income-generation opportunities, with short-term holiday rentals yielding 5-8% annually. The new terminal at Velana International Airport — now serving over seven million passengers annually — has dramatically improved connectivity and is driving up property values in surrounding areas. Negombo's fishing heritage, lagoon ecosystem, and beach culture provide an authentic coastal lifestyle that contrasts with resort-heavy southern destinations. The city serves as a natural first and last stop for travelers, creating consistent demand for guesthouses, boutique hotels, and serviced apartments. With Sri Lanka recording 2.36 million tourists in 2025 — its highest ever — Negombo's gateway position ensures it captures a disproportionate share of the island's tourism growth.
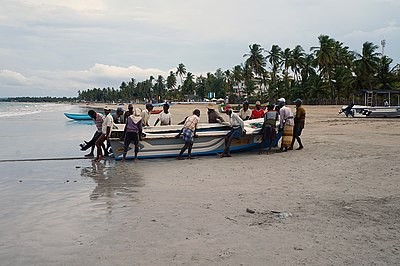
Trincomalee
Sri Lanka
Trincomalee is Sri Lanka's eastern jewel, home to one of the world's finest natural harbors and some of the island's most pristine beaches. This historic port city is experiencing a dramatic post-conflict resurgence, with its turquoise waters, whale-watching tours, and ancient Hindu temples drawing adventurous travelers and cultural tourists seeking alternatives to the developed southern coast. The property market is at an early-stage with higher risk but greater appreciation potential. The Asian Development Bank has approved a US$30 million project to enhance tourism infrastructure, while the 2026 Budget includes Rs. 1 billion for upgrading Trincomalee Airport to improve regional accessibility. The Sri Lanka Tourism Development Authority is offering over 3,000 acres to investors, with Trincomalee parcels including prime coastal plots. Entry prices remain among the lowest on Sri Lanka's coast, positioning early investors for significant capital appreciation. Trincomalee's natural assets are extraordinary: Nilaveli and Uppuveli beaches rival any in South Asia, Pigeon Island offers world-class snorkeling, and the harbor has attracted strategic interest since antiquity. The post-conflict rebuilding, combined with government-backed tourism investment and improving infrastructure, is transforming Trincomalee from a hidden gem into Sri Lanka's next major tourism destination.
Weligama
Sri Lanka
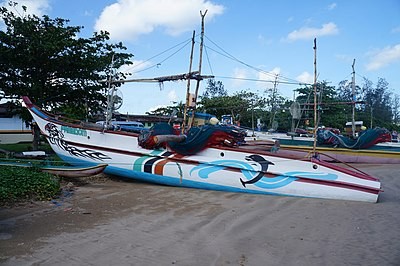
Weligama is an emerging beach destination and surf town on Sri Lanka's southern coast, located approximately 30 minutes east of Galle in the Matara District. With a population of roughly 72,500, this once-quiet fishing village has transformed into one of South Asia's most exciting coastal investment frontiers, driven by the global surf tourism boom, the rise of digital nomad culture, and Sri Lanka's post-crisis value proposition. The town's long, crescent-shaped sandy beach with shallow, consistent waves makes it the island's most popular learn-to-surf destination, while nearby breaks at Midigama, Mirissa, and Ahangama cater to experienced surfers. This surf ecosystem has spawned a vibrant hospitality scene of surf camps, boutique guesthouses, beachfront cafes, and coworking spaces. Named as 2025's most budget-friendly beach destination for digital nomads, Weligama offers a remarkably affordable cost of living — solo nomads spend approximately USD 624 per month, and coworking memberships average USD 140 per month. Property investment in Weligama ranges from boutique villa developments (USD 130,000 to USD 2.2 million) to beachfront land parcels suited for hospitality projects. While foreigners cannot own freehold land, 99-year leaseholds provide near-freehold security for villa and guesthouse investments. The combination of rising tourism, expanding infrastructure, and very low entry prices relative to established surf destinations (Bali, Portugal, Costa Rica) positions Weligama as a high-potential emerging market for lifestyle-oriented investors.

Bangkok City Guide
Thailand
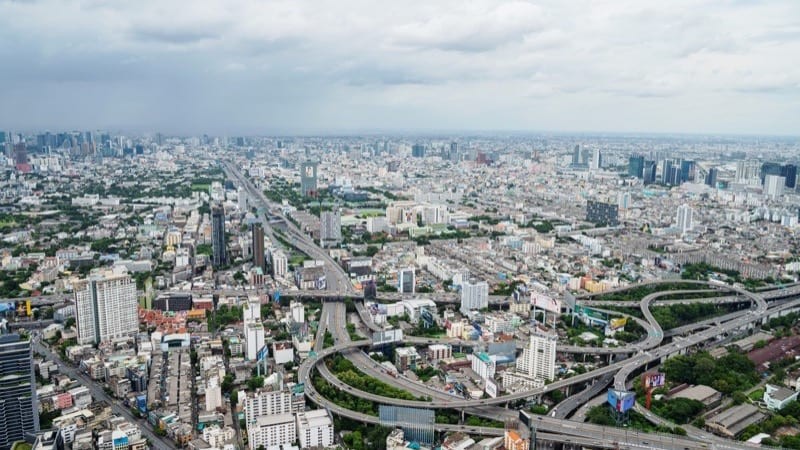
Thailand's electrifying capital where ancient temples share the skyline with gleaming skyscrapers. From the cosmopolitan Sukhumvit corridor to the hipster cafes of Ari and the luxury waterfront of the Riverside, Bangkok offers investors a world-class city at Southeast Asian prices — with yields that outperform most global capitals. Bangkok is one of the world's most visited cities, welcoming over 22 million international tourists annually. Its exceptional street food culture, world-class shopping, vibrant nightlife, and deeply spiritual Buddhist heritage create a lifestyle appeal that drives both tourism and long-term expatriate demand. For property investors, the combination of low entry prices, strong rental yields, and a transparent condominium ownership framework makes Bangkok one of the most accessible and rewarding Asian markets.
Chiang Mai City Guide
Thailand
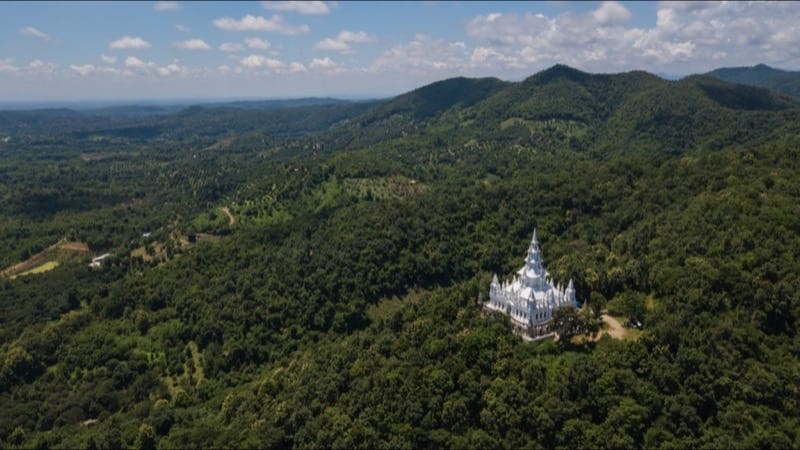
Thailand's cultural capital where 700 years of Lanna heritage meet a thriving digital nomad revolution. From the temple-studded Old City to the cafe-lined streets of Nimmanhaemin and the mountain valleys of Mae Rim, Chiang Mai offers investors extraordinary value in a city that consistently ranks among the world's most livable destinations for remote workers and retirees alike. Chiang Mai has become one of the world's top destinations for digital nomads, with a vibrant co-working scene, ultra-affordable cost of living, and a creative community that spans tech entrepreneurs, artists, and wellness practitioners. The city's over 300 Buddhist temples, thriving night markets, and proximity to elephant sanctuaries and mountain trekking create a cultural richness that draws visitors year-round. For property investors, entry prices are among the lowest in Southeast Asia, with condominiums available from under $50,000.
Hua Hin City Guide
Thailand
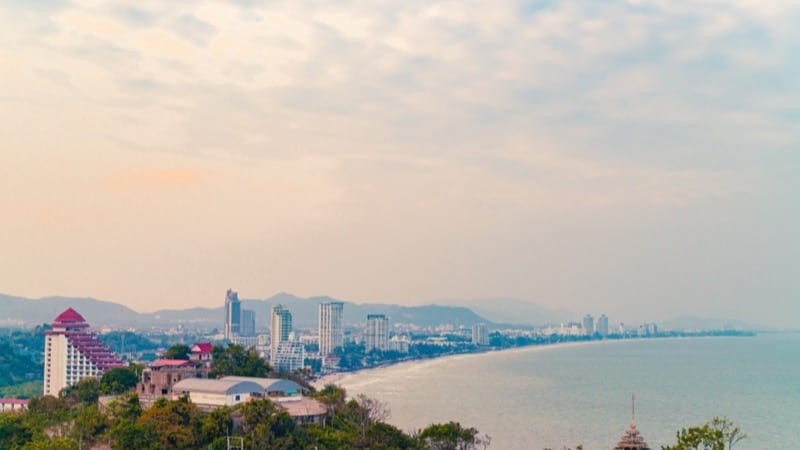
Hua Hin is Thailand's original royal seaside resort, a refined beach town roughly 200 kilometres south-southwest of Bangkok that has matured into one of the kingdom's most stable second-home and rental markets. Unlike the boom-and-bust volatility of some Thai resort destinations, Hua Hin is prized for measured, sustainable growth: property values are appreciating a healthy 3-7% annually with no oversupply overhang, and transaction volumes jumped roughly 45% in 2024. Condominium prices average around THB 87,434 per square metre, with new beachfront and downtown launches ranging from about THB 71,000 to THB 254,000 per square metre depending on project and location - landmark schemes such as InterContinental Residences, VEHHA Hua Hin, and Sasara anchoring the luxury tier. Houses average a more accessible THB 38,932 per square metre. The rental case is genuinely attractive for a Thai resort market: gross yields typically run 4-6%, with premium beachfront and central units reaching up to 7%, fed by a diverse tenant pool of European, Russian, and Chinese second-home buyers, retirees, and a growing digital-nomad contingent. A major catalyst is the airport terminal upgrade due for completion by April 2026, which is expected to restore international flights from regional hubs such as Kuala Lumpur and Singapore - reinforcing Hua Hin's appeal as a steadier, lower-volatility alternative to Phuket or Pattaya.