The 10-Point Due Diligence Framework Every Cross-Border Property Investor Should Know
ByAbhii Dabas·In short
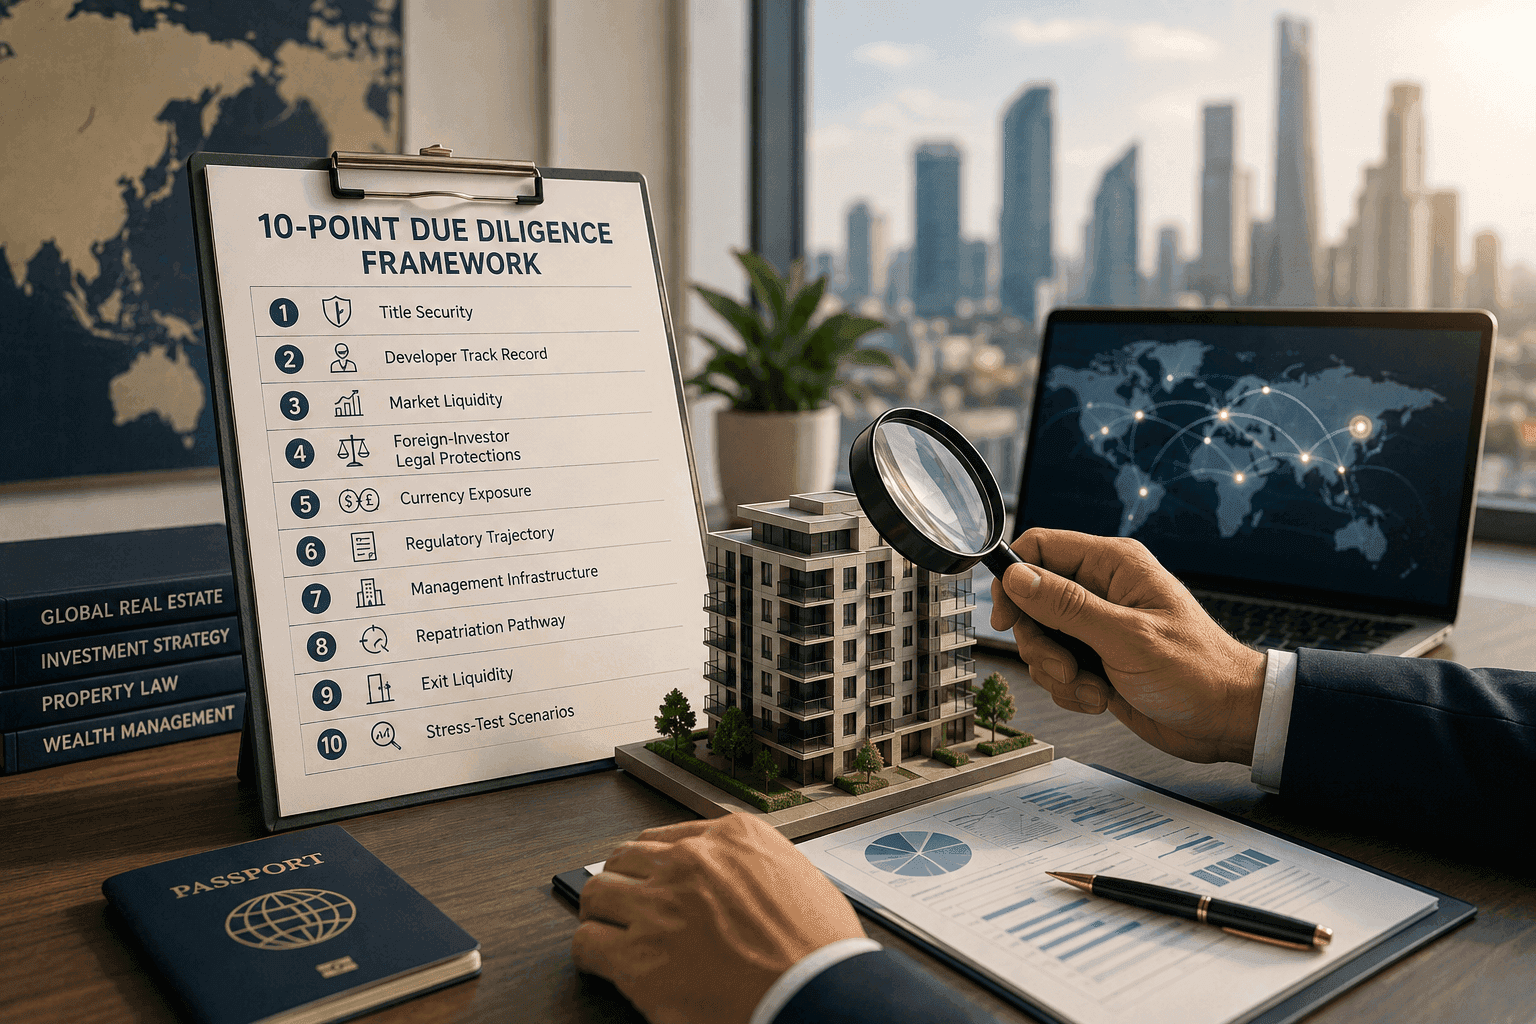
Cross-border property due diligence requires a structured framework that goes beyond a standard domestic property check. The 10-point framework Intric applies before listing any developer or asset evaluates title security, developer track record, market liquidity, foreign-investor legal protections, currency exposure, regulatory trajectory, management infrastructure, repatriation pathway, exit liquidity, and stress-test scenarios. Each point can disqualify an asset on its own.
Key takeaways
- Title security is the first check, not the last. Markets with fragmented registry systems require independent legal verification, not the developer's solicitor.
- Developer financial standing matters more in off-plan than in resale. A developer's track record on past projects predicts the likelihood of completion on the current one.
- Foreign-investor legal protections differ across markets. The strongest protection comes from established freehold systems with arbitration clauses recognised internationally.
- Management infrastructure is a market-level variable. Some markets do not have it at international standard regardless of how much the buyer is willing to pay.
- Exit liquidity should be stress-tested before purchase, not assumed.
Introduction
Cross-border property due diligence requires a structured framework that goes beyond a standard domestic property check. The 10-point framework Intric applies before listing any developer or asset evaluates title security, developer track record, market liquidity, foreign-investor legal protections, currency exposure, regulatory trajectory, management infrastructure, repatriation pathway, exit liquidity, and stress-test scenarios. Each point can disqualify an asset on its own.
What is cross-border property due diligence and why does it matter?
Cross-border property due diligence is a structured verification process that an investor (or platform) completes before committing capital to a foreign property purchase. The process goes beyond standard domestic property checks because the investor cannot rely on familiarity with the local legal system, developer ecosystem, or market norms. The risk of an undisclosed problem surfacing post-completion is materially higher in cross-border transactions than in domestic ones.
Due diligence matters because the cost of fixing problems after exchange is many times higher than the cost of catching them before. Title disputes, undisclosed liens, developer financial distress, capital control surprises, and management failures can each erase returns or destroy capital. The investor's protection is not the seller's brochure. It is the investor's own verification framework, applied consistently.
How do you verify title security when buying overseas?
Title verification in cross-border purchases requires three layers: a search of the destination country's land registry by an independent local solicitor (not the developer's solicitor), confirmation that the title is freehold or appropriate leasehold for foreign ownership, and verification that no undisclosed liens, easements, or third-party claims attach to the title. In markets with fragmented registry systems, additional verification through local government records may be required.
Title risk is highest in emerging markets with land registry systems that are not fully digitised, where land registry records depend on local government cooperation, or where foreign ownership has historically required workarounds (nominee structures, leasehold-with-renewal mechanisms). Title risk is lowest in markets with central digital registries (UK Land Registry, Japan Legal Affairs Bureau, Singapore SLA, Australia Torrens system).
“Most title disputes I have seen in cross-border property were preventable. The investor used the developer's recommended solicitor. The solicitor flagged nothing because the developer was their client. Independent verification by a buyer-side solicitor with no developer relationship is non-negotiable.”
On INTRIC now — Residences on INTRIC are open to enquiry straight from this page.
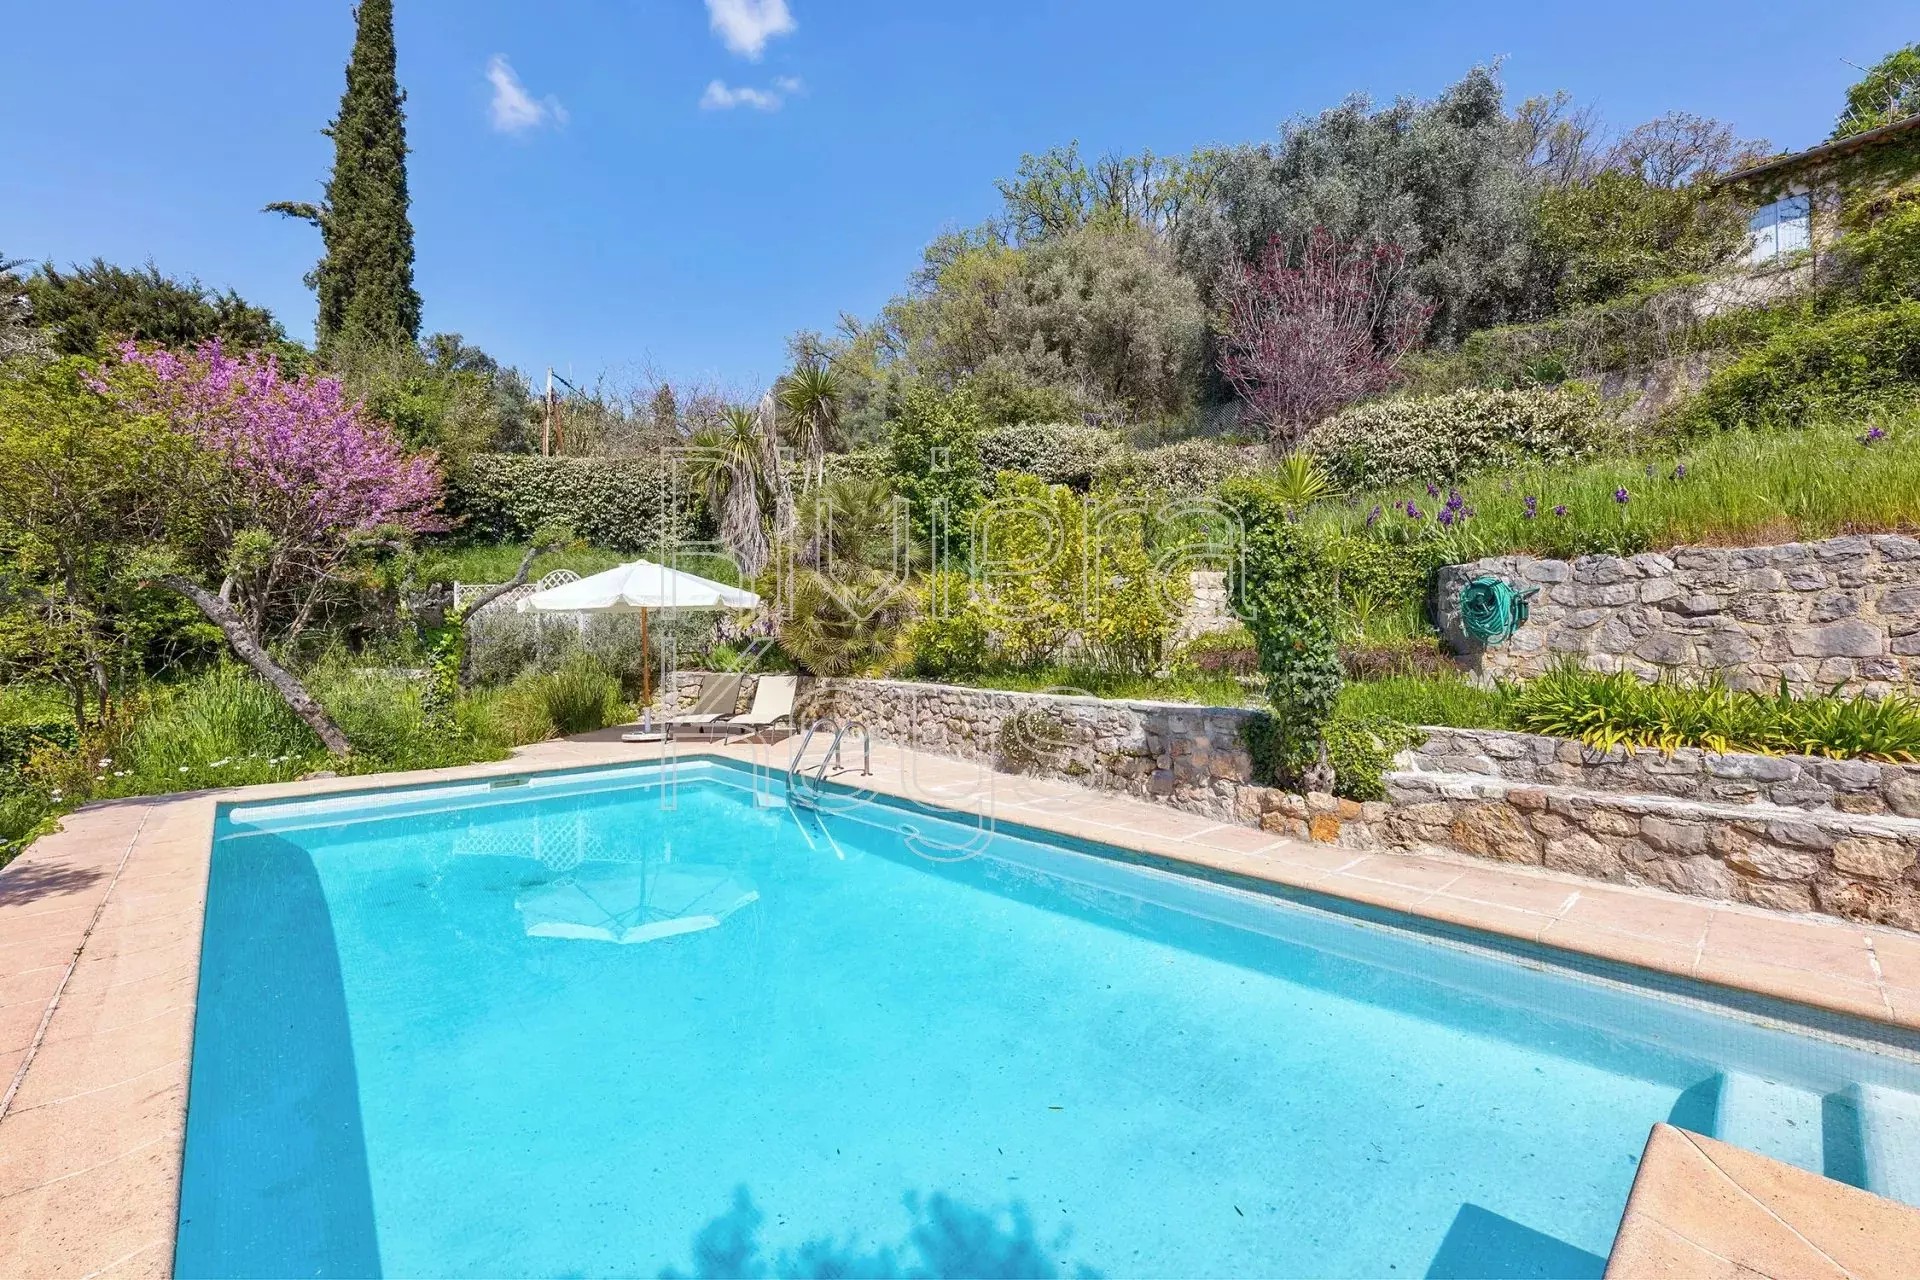
Montauroux Architect Villa
HOUSE · Montauroux, 83440, Var, Provence-Alpes-Cote d'Azur, France
EUR 950K – EUR 1.65M
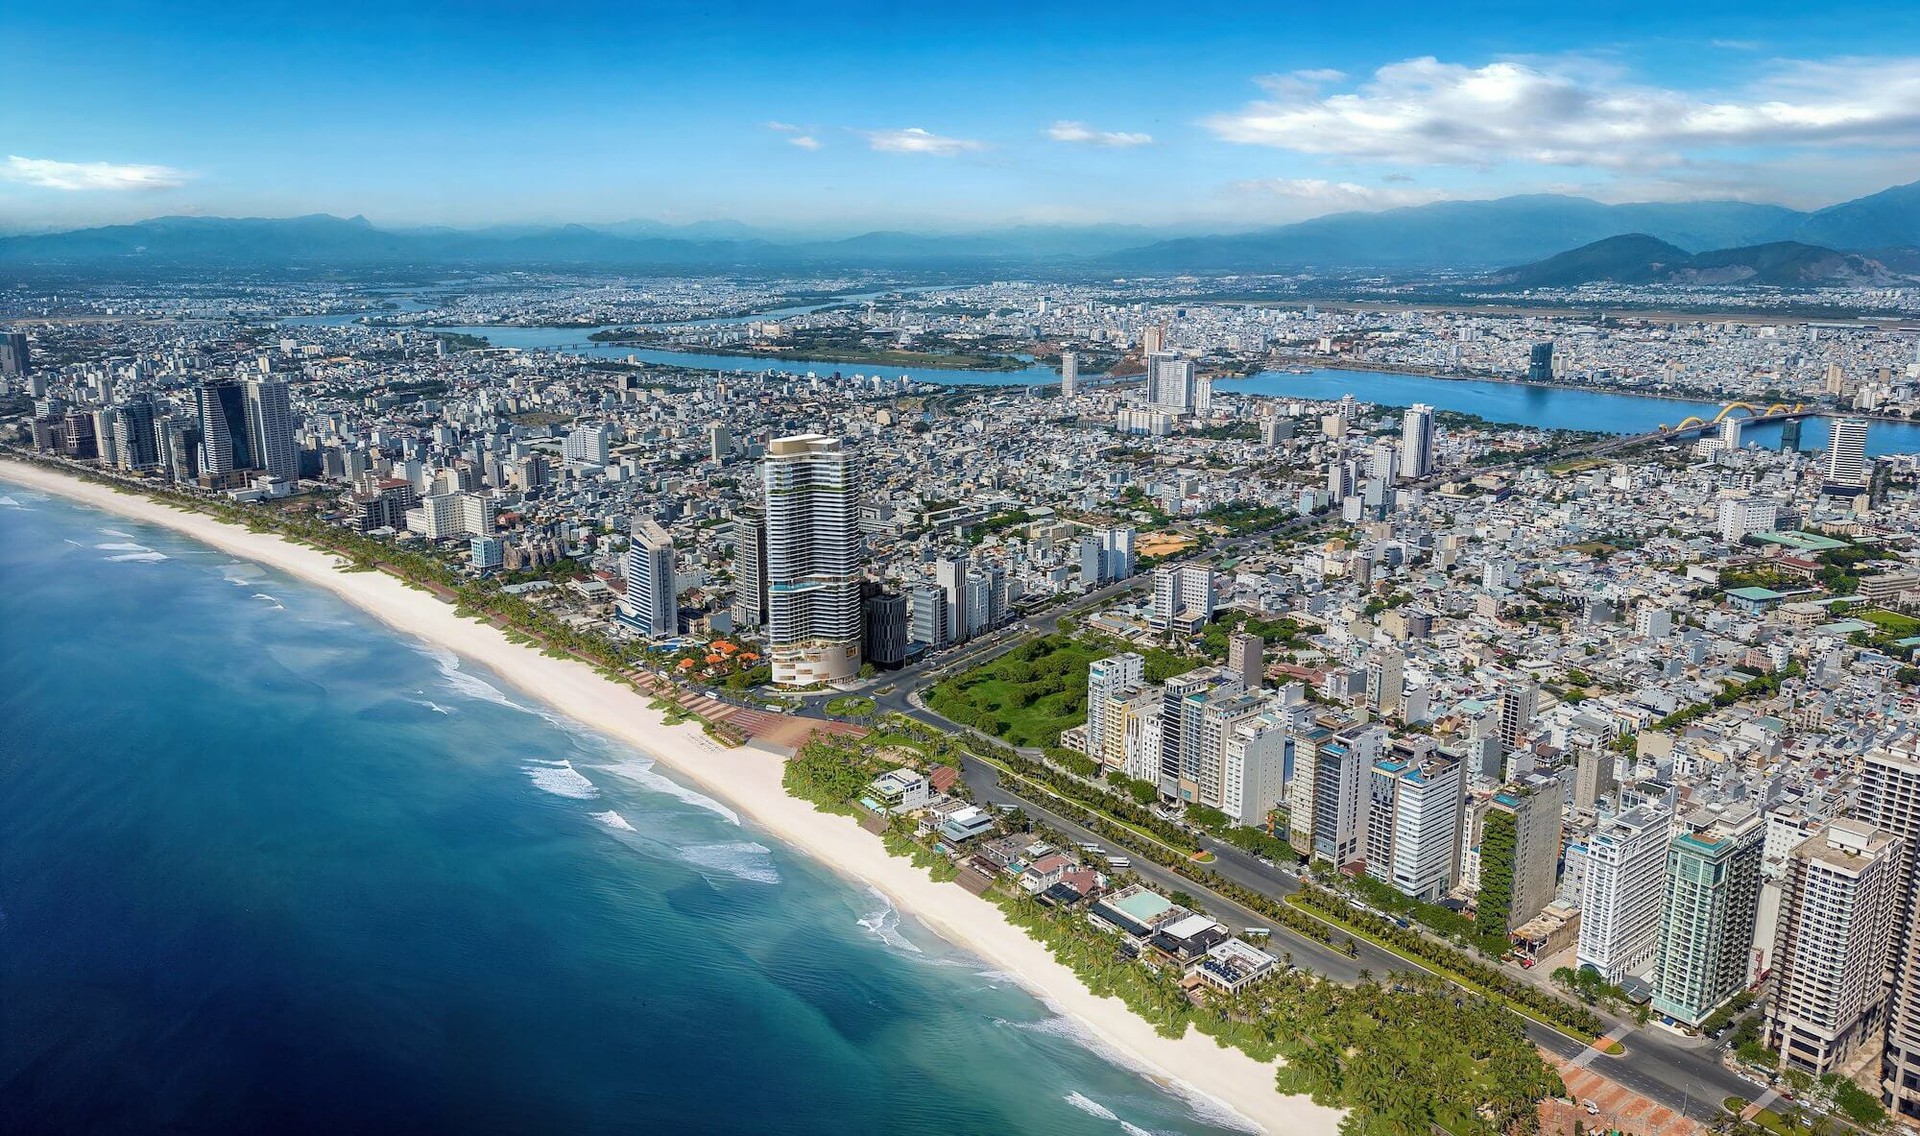
Nobu Residences
APARTMENT · POA - Son Tra, Danang, Vietnam
USD 180K – USD 2.70M
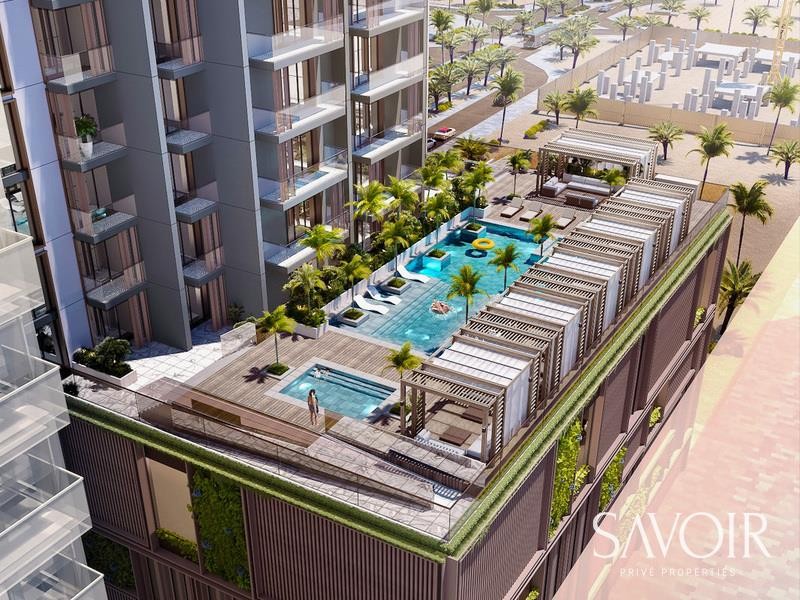
Q Gardens Lofts 2
APARTMENT · Q Gardens Lofts 2, District 12, Jumeirah Village Circle, Dubai, United Arab Emirates
From AED 597K
NEXT Address
Apartment · 11 Tbel Abuseridze Str, Batumi, 6010, Georgia
USD 50.9K – USD 191.2K
What should investors check about a developer's track record?
Developer track record verification covers three dimensions: completion history (projects delivered on time and to specification over the past 5 to 10 years), financial standing (registered company filings, debt position, ongoing project pipeline), and reputation (post-handover defect rates, owner satisfaction, post-warranty service quality). All three should be verified independently, not accepted from the developer's marketing materials.
In off-plan purchases, developer track record is the single most important determinant of whether the asset will exist as promised. A developer with weak past completion record carries materially higher default risk than gross yield calculations on the brochure account for. In resale purchases, developer reputation matters less because the asset exists, but post-warranty defect rates still affect the holding period economics.
How do you assess property market liquidity before investing?
Market liquidity is assessed by transaction volume in the specific price tier and submarket (not the city average), days-on-market for comparable resales in the past 12 to 24 months, and the depth of the resale buyer pool at the investor's likely exit price point. Markets where the only buyers at exit are other foreign investors carry materially higher liquidity risk than markets with active domestic owner-occupier or institutional demand at the same price tier.
Liquidity is often inversely related to gross yield in cross-border markets. The yield is high precisely because local demand at that price point is thin. Foreign capital supports the price on entry. When foreign capital exits, the price floor is exposed. Investors should evaluate liquidity at the price tier they expect to exit at, which may be different from the price tier they enter at if they plan to hold through capital appreciation.
On INTRIC now — Still open on INTRIC — every one of these answers enquiries directly.
Rukan Tower B
APARTMENT · Rukan Tower B, Rukan Tower, Dubai Land, UAE
From AED 555K
Riva Residences
APARTMENT · Dubai Maritime City, Dubai, United Arab Emirates
AED 2.53M – AED 5.80M
Riviera Residences
Apartment · Al Reem Island, Abu Dhabi, UAE
AED 1.90M – AED 4.85M
Rove Home
APARTMENT · Rove Home, Aljada
From AED 1.17M
What legal protections exist for foreign investors in key markets?
Foreign-investor legal protection varies significantly across Intric's corridor markets. The UK provides full legal equivalence between domestic and foreign owners, with the only differences being non-resident SDLT and IHT treatment. Japan offers comparable equivalence with minimal foreign-buyer-specific rules. Thailand restricts foreign ownership at the building level (49% condo quota) and prohibits direct land ownership. UAE permits full freehold in designated zones, with separate rules elsewhere.
The strongest protection comes from established freehold systems with international arbitration clauses recognised under the New York Convention, transparent dispute resolution timelines, and courts with experience in foreign-investor cases. The UK, Japan, Australia, and Singapore meet all three criteria. Some emerging markets meet none of them. The investor's recourse in the event of dispute is part of the asset's value, not separate from it.
What is the 10-point due diligence framework Intric applies?
Intric applies a 10-point framework to every developer and asset before listing on the platform. Each point can disqualify an asset on its own. The framework is summarised below. The full framework is shared with members and applied by Intric's curation team before any listing decision.
- Title security: independent legal verification of freehold status, lease term where applicable, and absence of undisclosed liens.
- Developer financial standing: registered filings, debt position, ongoing pipeline, and 5-year completion history.
- Comparable performance: gross and net yield achieved on comparable completed projects by the same developer.
- Foreign-investor legal protection: ownership structure permitted, dispute resolution pathway, arbitration recognition.
- Currency and macro exposure: 10-year volatility of the local currency against major reference currencies (USD, EUR, SGD).
- Regulatory trajectory: direction of foreign ownership rules, capital controls, and tax treatment over the past 5 years.
- Management infrastructure: presence and audit standard of professional property management at international service quality.
- Repatriation pathway: documented funding channel and ability to repatriate sale proceeds without administrative friction.
- Exit liquidity: transaction volume and days-on-market for comparable resales in the past 24 months at the expected exit price tier.
- Stress-test scenarios: realistic downside modelling under 20% market correction, 15% currency move, and management failure.
Frequently asked questions
What is the most common due diligence failure in cross-border property?
How long does proper cross-border due diligence take?
Does Intric handle due diligence for members or do members handle it themselves?
Which markets are highest risk for foreign investor due diligence?
Can investors apply this framework without an institutional platform?

Abhii Dabas is the Founder and CEO of INTRIC Global, the cross-border property intelligence platform for serious investors. He advises high-net-worth buyers on international real estate strategy and has evaluated residential markets across more than 40 countries.